Highnote Teams Up with Visa to Launch Agentic Commerce Capabilities

Highnote Teams Up with Visa to Launch Agentic Commerce Capabilities
  • Modern card platform Highnote unveiled its new Agentic Commerce capabilities this week.
  • Built using Visa Intelligent Commerce, Highnote’s Agentic Commerce will allow businesses to power AI-initiated payments that feature programmable controls, tokenized credentials, and dynamic authorization.
  • Headquartered in San Francisco, Highnote made its Finovate debut at FinovateSpring 2022.

Courtesy of a partnership with Visa, Highnote—a modern issuing, acquiring, credit, ledger, and money movement platform—has launched its new Agentic Commerce capabilities this week. Built using Visa Intelligent Commerce, the new offering will enable businesses to securely power AI-initiated payments with programmable controls, tokenized credentials, and dynamic authorization.

The new Agentic Commerce capabilities will allow companies to add payment capabilities to AI agents while enabling software to initiate and execute transactions with predefined rules, spend controls, and approval structures. In a statement announcing the launch, Highnote listed invoice and accounts payable automation, vendor payments, operational spend management, and AI-assisted procurement as some of the initial use cases for the new solution.

“AI is quickly moving from insight to action,” Highnote CEO John MacIlwaine said. “Businesses want AI to do more than recommend or analyze. They want it to initiate and execute real financial workflows. The challenge is making those transactions secure, controlled, and operational at scale. That’s exactly what Highnote is built to do.”

Agentic commerce enables software to participate directly in purchasing and payment decisions based on preset authorization rules. The new capabilities give firms a structured framework for enabling AI-driven transactions with real-time visibility and decisioning across the payment lifecycle. Highnote’s Agentic Commerce offering will also support emerging financial operations powered by AI, such as intelligent procurement, dynamic payment routing, supplier optimization, recurring operational spend, and industry-specific autonomous payment experiences.

“Agentic commerce is already changing how businesses operate,” said Visa VP and Head of Agentic CMS Ivy Lee. “Through Visa Intelligent Commerce, we’re enabling B2B workflows where agents can initiate and complete transactions at scale. Visa provides the underlying infrastructure that makes this possible—handling the complexity so businesses and developers can focus on building differentiated experiences, not payments.”

Headquartered in San Francisco, California, Highnote made its Finovate debut at FinovateSpring 2022. At the conference, the company demonstrated how its modern card platform with a GraphQL-based API enables businesses to make card issuance an embedded capability. The demo also featured the developer experience and financial operations interface that provides control of the payment transaction lifecycle and access to transaction processing data.

Named to the Forbes Fintech 50 for a second consecutive year, Highnote last month unveiled expanded commercial card issuing capabilities for online travel agencies (OTAs), marketplaces, and travel platforms. The new offering enables these platforms to run on Highnote’s commercial card issuing platform, using virtual card programs that are purpose-built for the challenges of travel supplier payments. Highnote’s solution combines issuing, controls, ledger, and reconciliation into a single system in order to deliver faster reconciliation, bolster supplier relationships, and improve unit economics on every transaction.


Photo by Maarten van den Heuvel on Unsplash
6 Arguments For and Against Prediction Markets as Spain Cracks Down

6 Arguments For and Against Prediction Markets as Spain Cracks Down

Spain’s ministry of consumer rights blocked access to Kalshi and Polymarket this week. The country has paused the use of the prediction markets (also known as event contracts) as it determines whether their models are operating legally without a gambling license.

Spain joins France, Belgium, the Netherlands, and Romania, which have all limited or blocked access to Polymarket.

The controversy begs the question: are prediction markets useful forecasting tools, speculative tools, or simply gambling platforms wrapped in fintech language? With that in mind, here’s a look at three arguments for and three arguments against event contracts.

Three arguments for

Supporters argue that prediction markets are not necessarily about gambling, but rather about information discovery.

  • Prediction markets can aggregate information more efficiently than polls or experts
    Prediction markets force participants to put money behind their convictions, which essentially rewards accuracy with financial incentives. Supporters argue this makes them more effective than polls or expert commentary at forecasting future events because markets continuously absorb new information and update probabilities in real time.
  • Financial markets already operate as forms of event contracts
    If you’ve ever invested in single stocks, you’ve essentially participated in prediction markets. The only difference is that, with stocks, investors are limited to predicting the outcome of a company instead of an event. Bonds and derivatives are also a type of prediction as well, as bonds essentially price default risk and derivatives price probabilities. This raises the question, why is betting on election outcomes different from betting on interest-rate moves.
  • Prediction markets could improve forecasting
    Because they are a useful tool for crowdsourcing information, prediction markets can be used by businesses or governments to improve decision-making. Users are more likely to make predictions on events about which they are knowledgeable, and this information could be helpful for forecasting recessions, fraud, supply chains, elections, and demand. Because they can source this information quickly, prediction markets can surface truths faster than committees or social media.

Three arguments against

Opponents argue that event contracts cause unwanted externalities

  • They may incentivize harmful or unethical behavior
    Oftentimes, event contracts offer events surrounding wars, assassinations, elections, and disasters. These are uncomfortable things to bet on, as it may feel as if users are rooting for these outcomes. Additionally, this raises ethics concerns over investors profiting from others’ tragedies.
  • Markets can be manipulated
    Even though prediction market outcomes may appear more organic than the performance of publicly traded companies, they are not immune to manipulation. Deep-pocketed participants willing to absorb larger losses may attempt to distort market odds, while coordinated misinformation campaigns and bot-driven activity can artificially influence sentiment and pricing. As event contracts become more popular, concerns are growing that the markets themselves could shape public perception rather than simply reflect it.
  • They lack consumer protections and regulatory frameworks
    Across the globe, prediction markets are relatively new and therefore lack regulation, as they don’t fit cleanly into existing categories. It is unclear if they are considered securities, gambling, or derivatives and therefore lack proper regulatory oversight and consumer protection standards.

As prediction markets continue to grow in popularity, regulators will increasingly need to decide whether these platforms belong within financial services, gambling, or an entirely new category. Spain’s move suggests that many jurisdictions are still uncomfortable with the idea of turning elections, world events, and public sentiment into tradeable assets.


Photo by Dante Grime Kahan

Robinhood Lets Agents Trade Stocks and Make Payments

Robinhood Lets Agents Trade Stocks and Make Payments
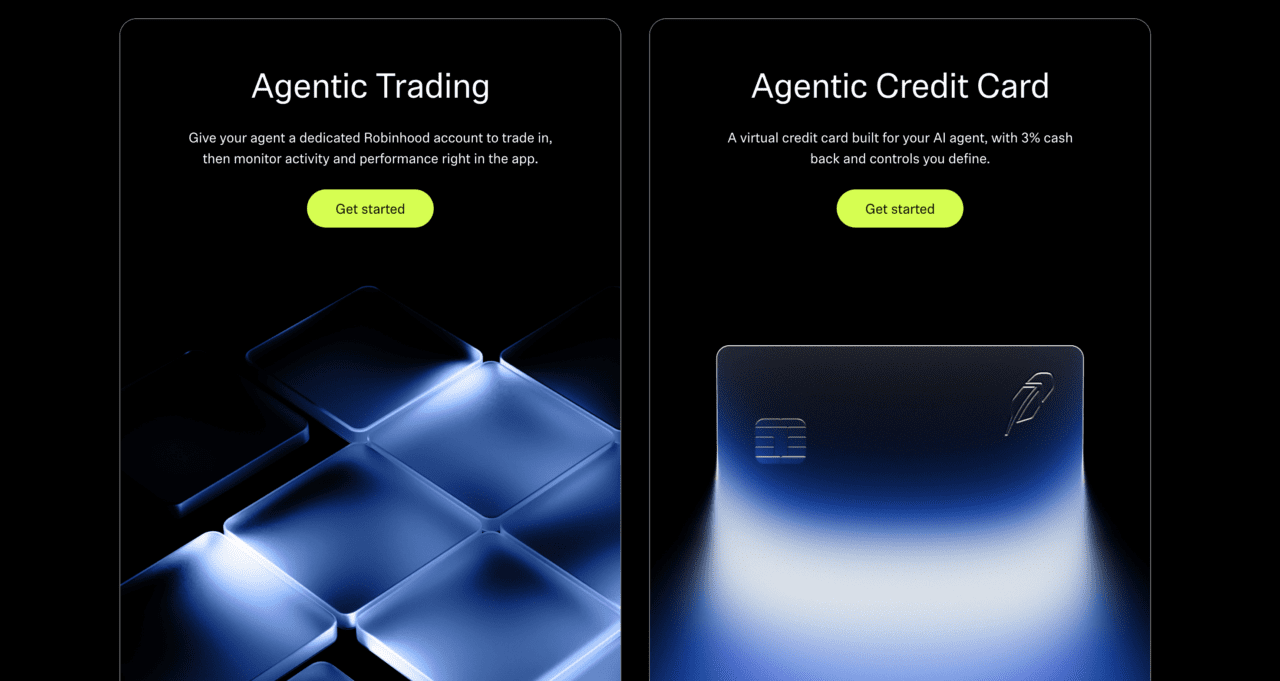
  • Robinhood launched Agentic Trading and an Agentic Credit Card, enabling AI agents to trade stocks and make purchases directly on consumers’ behalf through Robinhood’s infrastructure.
  • The new tools allow users to connect external AI agents via Robinhood’s MCP servers while maintaining guardrails such as spending limits, dedicated accounts, manual approvals, and real-time activity monitoring.
  • The launch marks a major shift in financial services from AI as an advisory assistant to AI as an authorized participant capable of directly executing financial transactions and trades.

The agentic future is slowly becoming a reality in 2026. Ready for this reality, Robinhood is launching Agentic Trading and the Agentic Credit Card, which will allow AI agents to trade and make credit card purchases on consumers’ behalf.

While building agents is still not mainstream, the value they can bring to financial tasks is irrefutable. In the investing world, they can automate and execute a specific trading strategy and make trades faster than humans can. When it comes to payments, they can purchase scarce, limited release items such as concert tickets, sneakers, or flights to get the best price.

The new Agentic Trading and Agentic Credit Card tools allow users to give agents direct access to Robinhood without workarounds. Users can bring their agent from anywhere and connect them to Robinhood’s Model Context Protocol (MCP) servers to integrate seamlessly into Robinhood’s offerings.

Robinhood believes agentic finance will become an increasingly important interface for how consumers interact with financial services in the years ahead. “Our mission has always been to democratize finance for all, and now, that mission extends to AI agents,” said Robinhood CEO Vlad Tenev.

Robinhood’s new agentic trading tool allows users to open a dedicated agentic trading account separate from their traditional portfolio, which restricts agents to only access the funds available in that account. Robinhood sends users push notifications when the agent makes a trade and offers users a view of real-time trading activity. Robinhood’s Agentic Trading is launching today in beta and currently supports equities only with plans to support options, crypto, event contracts, futures, and more in the future.

The Agentic Credit Card allows agents to spend on consumers’ behalf by connecting them to Robinhood Banking’s MCP server. Cardholders can connect their agent to a dedicated virtual Robinhood Gold Card, set a specific spending limit, and choose whether or not to require manual approvals. Agents are restricted to that individual virtual card, with no access to the user’s primary credit card number or any of their account information. Agentic credit cardholders can set monthly limits, view their expense history, and have the ability to delete the virtual card at any time.

At launch, both agentic trading and the agentic credit cards are now available to Robinhood Gold cardholders, with plans to open it up to Robinhood Platinum cardholders when it launches later this year.

Any time agents are allowed to interface directly with financial accounts, there is risk involved. Because agent involvement in trading and payments is still new, there are no established consumer protection frameworks, dispute resolution standards, and clear liability structures for situations in which an AI agent acts outside of a user’s intent. However, Robinhood has proactively implemented manual approvals for purchases, trade previews when appropriate, and a fraud detection team to help users resolve disputes between what the user asked the agent to do and what it actually did.

This launch is notable in the financial services space. While both organizations and end consumers have typically used AI as assistants or for advisory purposes, leveraging agentic capabilities hasn’t gone mainstream until today. With Robinhood’s new launch, AI agents are now authorized participants in the financial ecosystem.

Didit Raises $6 Million for AI-Based Identity Verification

Didit Raises $6 Million for AI-Based Identity Verification
  • Spain-based Didit raised an additional $6 million in Seed funding to expand its programmable identity and fraud infrastructure globally, bringing its total funding to $7.5 million.
  • Didit offers developers API-first tools to verify users, businesses, and online interactions, using AI to analyze more than 200 signals including biometric liveness, deepfakes, and behavioral activity.
  • The funding highlights growing demand for identity and fraud tools built for the AI era, as businesses face rising threats from generative AI, synthetic identities, and automated fraud attacks.

Spain-based Didit just brought in an additional $6 million for its identity verification network, boosting its total Seed funding to $7.5 million.

Investors in today’s round include Y Combinator, Pioneer Fund, Orange Collective, Founders Future, Phosphor Capital, SaaSholic, and Rebel Fund, alongside angel investors Tomer London, Taro Fukuyama, and others. Didit will use the investment to scale globally, expand its open infrastructure toward fully programmable identity and fraud coverage, and recruit new employees.

Didit was founded in 2023 to build a programmable identity infrastructure for the internet. The platform offers a developer-first way to verify people, businesses, and automated digital interactions like logging into an account, approving a transaction, or granting permissions.

The platform connects to a network of global government data sources and leverages AI to analyze more than 200 data points, such as document authenticity, biometric liveness, injection attack detection, deepfake analysis, and behavioral signals from every interaction. The company, which counts more than 1,500 customers, serves organizations across more than 220 countries and territories.

Didit reports plenty of demand for its identity verification network, saying that it is an untapped market. The company reports that 80% of its customers had not previously used an identity verification provider.

“No one was building for what was actually happening,” said Didit Founder and CEO Alberto Rosas. “Fraud kept getting smarter, regulators kept getting stricter, and millions of new businesses suddenly needed to verify their users—but every existing provider couldn’t catch the new fraud, had painful onboarding, and hid pricing behind a sales call. So we built the opposite: one API for identity and fraud, public per-module pricing, and an integration so simple that any developer can ship it in five minutes—or any AI coding agent like Claude Code, Codex, or Cursor can ship it in a single prompt.”

Didit differentiates itself from other identity verification providers, viewing itself as programmable identity infrastructure. “What we’re really building is the trust layer for the internet,” added Rosas. In the long term, the company wants to be an identity wallet that allows people to verify once and reuse their identity everywhere.

The funding comes as identity verification providers face a rapidly changing threat landscape driven by generative AI, deepfakes, synthetic identities, and automated fraud attacks. At the same time, developers increasingly expect identity tools to be API-first, priced transparently, and easy to integrate into digital onboarding and transaction workflows.


Photo by Anastasia Shuraeva

InComm, Zip Partnership Brings Buy Now, Pay Later to Gift Cards

InComm, Zip Partnership Brings Buy Now, Pay Later to Gift Cards
  • Financial services company Zip announced a new partnership with international payments company InComm Payments.
  • The partnership will bring Buy Now, Pay Later (BNPL) functionality to the gift card category.
  • Founded in 1992, InComm made its Finovate debut at FinovateFall 2011 in New York. The company is headquartered in Atlanta, Georgia. Australia-based Zip was founded in 2013 and serves customers in New Zealand and the US, as well as Australia.

Digital financial services company Zip has teamed up with global paytech InComm Payments in a partnership that will bring Buy Now, Pay Later (BNPL) installment buying to the gift and prepaid card category. The integration will enable eligible consumers to buy popular gift card brands directly through the Zip app. Available gift cards include brands representing retailers, as well as entertainment, dining, and travel providers. Eligible users will be able to select their card of choice and the denomination, and then choose how to split the cost at checkout—completing the transaction without having to leave the Zip app.

“Our priority is making shopping for gift cards quick and simple, whether consumers need a gift for a special occasion or simply want to treat themselves,” InComm Payments SVP of Financial Services Adam Brault said. “Partnering with Zip to bring more flexible payment options is an effective way to further take the stress out of the gift card shopping process.”

The partnership arrives at a time when consumer interest in BNPL options is growing rapidly. Based on data from the US Federal Reserve, the number of consumers using BNPL over the past 12 months reached 15% in 2024, climbing from 14% in 2013, and 10% in 2021. Although headquartered in Australia, Zip has 4.6 million active customers in the US and 29,000 merchant partners who will be able to take advantage of this new payment flexibility when it comes to buying gift cards.

“Short-term installment payments have become a mainstream behavior, and our customers tell us they value this flexibility across all areas of their cashflow,” Zip Chief Marketing and Customer Officer Jinal Shah said. “Shoppers deserve more say over how they manage their money, and we’re committed to expanding flexible options to more consumers.”

Founded in 2013 by Larry Diamond and Peter Gray, Zip offers innovative and people-centered financial products to customers in New Zealand and the US, as well as in its native Australia. The company provides point-of-sale credit, cashflow, and digital payment services, connecting millions of consumers with its international network of tens of thousands of merchants. Zip has more than six million active customers and 85,000+ merchants using its technology, and processes 93 million transactions annually. Cynthia Scott is Group CEO and Managing Director.

Zip’s partnership announcement with InComm follows the company’s launch of its new mobile offering, ZMobile, in April. Created in partnership with TPG Telecom, ZMobile is a prepaid mobile plan that features 4G/5G network access reaching 98.5% of the Australian population, as well as global roaming and international calling capabilities. Zip currently serves 10% of Australian adults; ZMobile will be offered to the company’s existing customers in the weeks to come.

Founded in 1992, Atlanta, Georgia-based InComm made its Finovate debut at FinovateFall 2011. Today the company manages more than one billion cards a year facilitating $65 billion in annual transaction volume. InComm boasts more than 525,000 points of retail distribution and more than 2,400 employees across 35 countries and five continents. With solutions ranging from gift cards and reloadable debit cards to cash load technology and transaction processing, InComm serves companies in financial services, e-commerce and gifting, healthcare, and more. Brooks Smith is CEO.


Photo by Joey Kyber on Unsplash

How Tokenization, AI, and Banks Can Drive the Future of Commerce

How Tokenization, AI, and Banks Can Drive the Future of Commerce

With the wealth of conversation about AI at FinovateSpring just a few weeks ago, what are some of the key takeaways on how businesses are understanding and deploying the technology?

One of the more compelling presentations on this issue was the keynote address provided by Chris Nichols. Nichols is President of Institutional Banking at SouthState Bank where he supports innovation, AI, digital assets, loan pricing, asset-liability management, open banking, payments, and fintech investing. He is also producer of the Banker-to-Banker blog. Based in Winter Haven, Florida, SouthState Bank traces its roots back to First National Bank, founded in 1933 in South Carolina. Today, the institution has more than 370 branches across eight states and, last year, completed a major $2.49 billion acquisition of Texas-based Independent Bank Group. SouthState Bank reported total assets of $66 billion as of Q3 2025.

In his keynote, Why Agentic AI is Truly a New Frontier in Financial Services & How Agentic Commerce Will Reshape the Retail Landscape, Nichols suggested that the intersection of tokenization, a technology that comes to us from blockchain technology, and agentic AI, the leading iteration of AI technology today, will radically change payments and commerce and, as an impact, change the way we order our professional and personal lives. These developments also introduce a major challenge and opportunity for banks. Here are some takeaways from his address.


Tokenization, Micropayments, and Smart Money

Nichols pointed out that tokenization and blockchain-based payments are poised to significantly reduce friction and costs for most transactions. This is huge for cross-border payments especially, but the technology would help enable 24/7 settlement, off-hour transactions, smart contracts, programmable money, and other capabilities.

It is easy to point to the cost of transactions like wire transfers and paper checks. But even instant payments as currently configured are significantly more costly than what is promised in a world of tokenized payments. In addition to payments that, in Nichols’ words, could cost less than a penny, the infrastructure that supports tokenized payments would also enable true micropayments and transactions of less than a cent. Such payments may have had little utility a few years ago, but the rise of the subscription economy and the gig workforce have created demand for a new kind of payment flexibility.

“As we think this through, we see commerce evolving dramatically,” Nichols said from the FinovateSpring stage. “If you are a content provider or another type of digital agent and you need 1/30,000th of a cent, it changes the face of commerce.”

Not only will tokenization make transactions faster and less expensive, transactions will also become intelligent. The ability to program money, to create smart contracts that are executable only when certain conditions are present, could revolutionize lending in finance, claims processing in insurance, and fractional ownership of assets in real estate—to name a few likely use cases.


Agentic Commerce’s Autonomous Participants

Interestingly, Nichols pointed out that what many of these smart contracts and programmable money technologies are likely to do is send commands not to human actors but to AI agents who will carry out the requisite tasks. Nichols used the example of planning and traveling to FinovateSpring in San Diego as work that will soon be completed almost 100% by AI agents acting on an individual’s behalf—from travel planning and hotel booking to registration fees and hotel bill.

What was especially noteworthy about Nichols’ observation was the role of discovery that these autonomous actors will play in a world in which they—the AI agents—are doing the research, inquiry, and even negotiation with various merchants, vendors, and other agents. “Yes, although humans will initially remain in control, the major debate is how much autonomy people are willing to give their agents,” Nichols said in response to an audience question. “The next evolution will likely involve validating agents independently, rather than always validating them via a human intermediary. Eventually, agents may even create other agents.”


AI Orchestration as an Opportunity for Banks

Where does this leave banks?

One major role for banks in this emerging environment is that of an orchestration platform. In this view, banks evolve into 21st century financial services facilitators, moving beyond deposits and money movement to serve as the infrastructure layer for a wide variety of financial workflows for multiple participants. The tasks of the bank would be to coordinate, automate, and secure the actions of everyone and everything from individual consumers and businesses to merchants and suppliers, and from payment rails and compliance systems to lenders and third-party platform partners—and their AI agents.

“For example, consider a property management company,” Nichols suggested. “An agent could upload lease agreements, read and structure them into smart contracts, enable renter payments, collect security deposits, and authorize recurring monthly payments. Renters could pay using credit cards, ACH, cash deposits at a branch, or deposit tokens.” Nichols explained how these funds could then be routed automatically to the property management company, which would take its share before forwarding the balance to the property owner. He pointed out that this process reduces credit risk for banks and removes the burden and potential error of the many intermediate manual processes. Nichols also noted that this was an opportunity for banks—and not just the largest institutions, either. “Agentic capabilities are making it easier than ever for smaller institutions to adapt,” he said.

“We believe banks will play a more central role in this future, often through partnerships with fintechs,” Nichols concluded. “Banks can help commercial customers move from analog sales processes to more agent-driven systems … Banks can help businesses become discoverable, move customers through the sales funnel, and handle both onboarding and follow-up processes.”

Fintech Rundown: A Rapid Review of Weekly News

Fintech Rundown: A Rapid Review of Weekly News

If you’re in the US, you may be pouring an extra cup of caffeine after an activity-filled long weekend. While you were away, however, the rest of the fintech world kept moving. This week, we’ll continue to add more announcements as the week progresses.


Payments

Marqeta expands account and money movement offering in Europe, building on strong regional momentum.

PlayHQ partners with Gr4vy to power payments across global markets.

Mastercard renews its partnership with CIB, the largest private sector bank in Egypt.

ClearBank Europe launches Digital Asset Rails to unlock programmable liquidity for cross-border flows.

Business financial management

Coupa acquires Tonkean to accelerate agentic intake and orchestration for global trade.

Fraud and identity

INETCO surpasses 100 billion annual transactions as demand for payment fraud protection soars.

Nigerian cybersecurity and compliance company SmartComply launches in the UK.

Agentic AI

Agentic finance startup Catena Labs raises $30 million in Series A funding.

Wealth management

FIS and InvestCloud team up to launch AI-powered wealth management solution.

DeFi and stablecoins

Coinbase re-launches direct deposit option.

Mastercard granted New York State Department of Financial Services BitLicense.

Digital banking

Monzo offers a new telco plan offering discounts every year


Photo by Donald Tong

The Consumer Credit Stack Is Being Rebuilt in Real Time

The Consumer Credit Stack Is Being Rebuilt in Real Time

With new enabling technologies like stablecoins and AI moving quickly and classic fintechs like Mint.com and Dwolla making their exits, it feels like fintech is entering a new era. This is especially true in lending, where new capabilities are enabling faster, more efficient, and in many cases more customer friendly tools than we had five years ago.

Looking back at the dawn of the decade, most lending innovation focused on digitizing the application process, facilitating the onboarding process, and turning loans faster. While some of those elements are still in place today, lending has changed with better intelligence, different distribution, and new infrastructure layers underneath credit itself.

Here’s a look at what’s changed:

Underwriting is becoming continuous instead of episodic

We used to think of the FICO score as the gold standard in underwriting. Today, however, underwriting is no longer done as a snapshot in time. Instead, lenders are using cash flow underwriting to get a view of the borrower’s creditworthiness over time by considering their account balance, overdraft occurrences, loan repayments, and other risk indicators.

Cash flow underwriting is becoming increasingly common, especially as consumers become more comfortable with open banking and the concept of sharing their financial data across platforms.

Embedded lending changed consumer expectations

Embedded lending itself is not new. Uber, for example, began experimenting with vehicle financing for drivers as early as 2014. What’s changed is how targeted, contextual, and embedded these lending experiences have become.

Today, financing is increasingly surfaced directly within the software platforms, marketplaces, and operational tools where consumers and businesses already spend their time. Point-of-sale platform Toast, for example, uses merchants’ daily sales data to underwrite loans and proactively surface financing offers within the Toast platform itself.

As consumers and businesses become more accustomed to contextual lending experiences like these and embedded buy now, pay later options they are relying less on traditional bank websites or standalone loan marketplaces to search for credit products.

The interface layer Is shifting

In addition to competition from software platforms and merchant ecosystems, a third distribution channel is beginning to emerge in lending: large language models (LLMs).

Consumers are increasingly turning to platforms like ChatGPT, Claude, and Gemini for both information and guidance and decision-making, including financial decisions. As these tools become more integrated into consumers’ daily lives, many borrowers may begin consulting an AI assistant before visiting a bank website or browsing a loan marketplace. Instead of searching manually for financing products, consumers may increasingly ask an LLM to help evaluate their situation and recommend the most suitable lending option.

That shift becomes even more significant as financial data aggregation moves into these environments. Through Plaid’s partnership with OpenAI, for example, ChatGPT can now aggregate and contextualize a consumer’s financial accounts, giving the platform a much richer understanding of cash flow, spending behavior, obligations, and financial goals.

As a result, the lender may still technically originate and hold the loan, but the customer relationship shifts to the interface layer. In this emerging model, the LLM becomes the discovery engine, recommendation layer, and engagement channel sitting between the consumer and the financial institution.

What scales vs. what doesn’t

Looking back at the lending technologies demoed on the Finovate stage five years ago, there is a noticeable divide between the ideas that generated excitement in the moment and the solutions that ultimately achieved scale.

Many of the products that struggled to move beyond the demo phase shared a common challenge: they required consumers to significantly alter their existing behaviors, communication methods, or digital environments. Metaverse-based banking and lending experiences, for example, were fun to watch on stage, but they never aligned with how most consumers wanted to interact with financial products in everyday life. In many cases, they required users to adopt entirely new platforms, devices, or behaviors before their value could even be realized.

By contrast, the lending solutions that have scaled most successfully are the ones that meet consumers where they already are. Buy now, pay later (BNPL) is perhaps the clearest example. Rather than requiring consumers to seek out financing separately, BNPL options are surfaced directly at checkout within the shopping experience itself. As a result, installment financing has become an expected feature for many higher-ticket purchases rather than a niche alternative payment method.

What credit looks like by 2030

Five years from now, much of today’s lending ecosystem will still look familiar. Regulated financial institutions will continue to originate loans, underwriting will remain central to managing risk, and compliance will remain a critical consideration not only for lenders, but also for fintech partners, platforms, and emerging distribution channels.

What may look very different, however, is the interface layer between the consumer and the lender.

Consumers may interact less directly with banks and more through AI assistants, software platforms, wallets, and embedded ecosystems that help evaluate financing options on their behalf. As LLMs become more integrated into everyday decision-making, they may fundamentally reshape how consumers discover, compare, and select credit products. In that environment, traditional loan marketplaces could become far less relevant as financing recommendations are surfaced contextually and conversationally through AI-driven interfaces rather than through manual product searches.


Photo by Silvio Pelegrin

54 New FinovateSpring Demo Videos Are Now Live and Free to Watch

54 New FinovateSpring Demo Videos Are Now Live and Free to Watch

FinovateSpring 2026 may be over, but the demos are just getting started. All 54 videos from the demo stage are now available to watch for free on Finovate.com and the Finovate YouTube channel.

This year’s demos showcased how fintechs are rethinking everything from AI-powered banking and embedded finance to fraud prevention, lending, payments, customer experience, digital identity, and wealth management. Earlier this month in San Diego, fintechs took the stage to deliver Finovate’s signature live, seven-minute demos in front of an audience of financial institutions, investors, analysts, and industry leaders.

Whether you attended FinovateSpring and want to revisit your favorite presentations or missed the event and want to catch up on the latest fintech innovation, the full demo lineup is now available on demand.

And stay tuned, because there’s more content on the way.

Recorded keynote presentations, panel discussions, fireside chats, and additional conference sessions will be added to the Finovate YouTube channel in the coming weeks, offering even more insight into the trends shaping financial services in 2026.

Watch the FinovateSpring 2026 demos now.

Subscribe to the Finovate YouTube channel.

5 Takeaways from Trump’s Executive Order on Fintech and Regulatory Frameworks

5 Takeaways from Trump’s Executive Order on Fintech and Regulatory Frameworks

In last week’s Finovate Weekly newsletter, I shared some thoughts on what fintechs might hope for from President Trump’s summit meeting with Chinese president Xi Jinping. While the meeting does not appear to have delivered anything of substance from a fintech or financial services perspective, Trump did sign an Executive Order (EO) shortly after returning from Beijing that actually has plenty for fintechs and financial services companies to think about—if not cheer for.

Let’s take a look at five top takeaways from the EO, titled Integrating Financial Technology Innovation into Regulatory Frameworks.


From containment to enablement

The executive order directs Federal financial regulators to review existing policies to “facilitate innovation and greater competition in the provision of financial services.” Even more directly, the order calls upon regulators to “take steps to encourage innovation by, and growth of, fintech firms and federally regulated institutions of all sizes.”

The “fintechs and friends” framing of the executive order is in and of itself telling. After years of trying to strike a balance between the needs of incumbent banks and financial services providers and insurgent fintech innovators, the EO suggests a potential shift from “containment” of fintech innovation to outright enablement.

More access to Fed payment rails

Operationally speaking, some of the biggest news in the EO might be the way it directs the Federal Reserve to review its approach to granting payment accounts and services. This includes potentially expanding access to Fed payment rails for fintechs and nonbanks. Practically speaking, this could incentivize easier access to Fed payment infrastructure, Fedwire, and settlement services typically reserved for bank intermediaries.

The EO criticizes “regulations, guidance, and policies” that it referred to as “relics of a time when financial services where predominantly provided in brick-and-mortar-centric settings.” While this potentially refers to a fairly broad range of existing directives, the tone clearly indicates a willingness to overhaul or at least revisit rules that fail to reflect our increasingly mobile, digital, and even agentic contemporary financial landscape.

Building better bank-fintech partnerships

The EO is also critical of “rules governing financial institution’s third-party risk management” which it claims unfairly favors incumbents “at the expense of innovators.” As such, the order directs regulators to examine supervisory practices, application processes, and guidance that may “unduly impede fintech firms from entering into partnerships with federally regulated institutions.”

This could positively impact opportunities for Banking-as-a-Service companies as well as sponsor bank relationships, charter applications, and more, potentially reducing some of the challenges and complexity brought on by regulatory uncertainty with regard to partnerships between banks and fintechs.

Crypto and stablecoins move toward the mainstream

With the passage of the GENIUS Act, it is clear that the administration is seeking to support, if not encourage, innovation in the digital asset space. This week’s executive order underscores that support, noting that President Trump signed an Executive Order in his first week in office that was designed to “secure” the United States’ position as the global leader in the “digital asset economy,” as well as to establish additional regulatory clarity and guidance for digital assets. Other EOs are also referenced, including the one in March 2025 that established the Strategic Bitcoin Reserve and US Digital Asset Stockpile.

Specifically, this week’s executive order directs the Federal government to “update its outdated regulations to allow integration of digital assets and other novel financial technology into traditional financial services and payment systems.” Clearly and increasingly, the Trump administration sees digital assets, blockchain technology, and stablecoins as key components of US financial system infrastructure rather than as niche products, isolated technologies, or speculative instruments.

A win for regulated fintechs?

From the wave of fintechs seeking bank charters to the increased regulatory clarity provided by recent executive orders, fintechs could be on the precipice of a “best of both worlds” scenario: a financial services industry that feels deregulated and more opportunity-rich due to what mighr actually be greater regulation and guidance. While there remains much to be seen in terms of how fintechs and nonbanks take advantage of this changing regulatory environment—from pursuing bank charters to more aggressively pursuing embedded and open finance technologies—it does seem clear that the US is positioning itself to be more competitive in a shifting, global fintech and financial services landscape


Photo by Tomasz Zielonka on Unsplash

NMI Acquires Account-to-Account Payments Infrastructure Innovator Dwolla

NMI Acquires Account-to-Account Payments Infrastructure Innovator Dwolla
  • Embedded payments infrastructure company NMI has acquired account-to-account (A2A) payment infrastructure innovator Dwolla.
  • The acquisition creates a combined entity that will process nearly $700 billion in annual transaction volume and will fortify NMI’s status as a major embedded money movement infrastructure firm.
  • Dwolla has been a Finovate alum since 2011, winning Best of Show honors in its appearances at FinovateSpring 2011 and FinovateSpring 2012.

Embedded payments infrastructure company NMI has acquired account-to-account (A2A) payment infrastructure provider Dwolla. The acquisition combines NMI’s payment acceptance, channel distribution, onboarding, and merchant lifecycle management with Dwolla’s capabilities in account-to-account infrastructure, real-time payments, open banking, and many-to-many funds flow. NMI will benefit from additional payment acceptance, orchestration, and money movement capabilities, enabling its ISO, ISV, and SaaS platform clients to accept, manage, and move money across a greater number of rails and use cases via a single infrastructure provider.

“This acquisition is a continuation of our strategy to build the most robust, white-label, embedded payments platform for our channel and enterprise partners,” NMI CEO Steve Pinado said. “Dwolla gives us modern, API-first, A2A infrastructure that strengthens our ability to help businesses accept, manage, and move money across more uses cases and more rails.” Pinado also noted that the acquisition will enable NMI to be a player in the emerging generation of money movement technologies and solutions including agentic payments and stablecoin-enabled settlement.

The acquisition creates a combined entity that will processes nearly $700 billion in annual transaction volume and fortify NMI’s status as a major embedded money movement infrastructure firm. NMI currently supports more than 6,000 technology partners with its modular, white-label platform, enabling them to provide seamless, scalable payment experiences across online, in-app, brick-and-mortar, mobile, and unattended channels. Courtesy of the Dwolla acquisition, NMI’s partners will be able to build on NMI’s capabilities to offer bank and real-time payments, and other sophisticated payment flows such as marketplace seller payouts, loan disbursements, payroll, supplier payments, and more. This will enable these companies to serve firms in industries ranging from insurance and lending to property management and healthcare.

In a statement, Dwolla CEO Dave Glaser noted how Dwolla has helped companies operate bank payments at scale thanks to an API-first infrastructure layer that unifies ACH and real-time rails while standardizing status, exception handling, and reporting. He also outlined how he thinks the combination of Dwolla and NMI will improve the payments process for businesses. “By joining NMI, we can bring those capabilities to a broader ecosystem of partners, while giving Dwolla customers access to NMI’s omnichannel payment acceptance capabilities through a single, flexible, white-label platform. Together, we can help software companies, payment professionals, and fintech innovators deliver more ways to pay and move money with less complexity.”

Founded in 2008 and headquartered in Des Moines, Iowa, Dwolla has been a Finovate alum since winning Best of Show in its Finovate debut at FinovateSpring 2011. A pioneer in peer-to-peer (P2P) and account-to-account (A2A) payments, Dwolla was among the first fintechs to offer lower-cost money transfers, direct ACH connectivity, and a developer-friendly, API-first strategy that enabled companies to embed payment capabilities into their platforms. Ahead of its time then, Dwolla has since benefitted from a surge in interest in account-to-account payments and embedded finance, facilitating more than 126 million transactions a year with an annual transaction value of more than $82 billion.

Schaumburg, Illinois-based NMI was founded in 2000. The company offers a modular payment acceptance platform and gateway that enables SaaS platforms, ISOs, banks, and other financial institutions to leverage payments to boost growth, drive loyalty, and develop new revenue streams. NMI’s technology serves more than 1.2 million active merchants, more than 235,000 connected devices, and features 150+ processor connections to give its partners flexibility to design the payment experiences that best suit their unique needs and business models. Dwolla is NMI’s most recent acquisition, having acquired Sphere Commercial Division in 2023 and Finovate alum Agreement Express in 2022.


Photo by Rihards Sergis on Unsplash

Regtech Eisen Raises $18.5 Million to Streamline Escheatment

Regtech Eisen Raises $18.5 Million to Streamline Escheatment

Eisen, a fintech that specializes in end-to-end escheatment and unclaimed property compliance automation, has secured $18.5 million in funding. The capital comes in the form of a $10 million Series A led by MissionOG and a previously unannounced $8.5 seed round led by Index Ventures. Cowboy Ventures, First Round Capital, Homebrew, and Restive Ventures also participated in the investment.

Eisen innovates in an often-overlooked area of financial services: escheatment and the recovery of unclaimed property. State law requires that abandoned funds eventually be turned over to the government in a legal process called escheatment. While each state has its own rules regarding dormancy periods, notice requirements, and remittance deadlines, the concept of escheatment is designed to help protect consumers when financial institutions lose track of them. Nevertheless, the process of retrieving those assets can be both complex and cumbersome. As such, it is little surprise that more than 30 million Americans have unclaimed property in state custody, with states holding a combined $70 billion in consumer assets: from retirement accounts and life insurance proceeds to forgotten savings accounts and emergency funds. Out of all of this, only $4.5 billion was returned to owners in 2024.

In response, Eisen’s technology streamlines the compliance lifecycle from dormancy tracking and due diligence through to state reporting, remittance, and audit defense. The company offers a Tax Compliance Suite to support 1099 filing, TIN matching, and B-notice handling, as well as disbursement services. This reflects the firm’s evolution beyond improving the escheatment process and a recognition that many of the same issues that plague escheatment also impact other compliance operations.

“We started with escheatment because the gap there is the widest, but the same operational pattern shows up across the compliance stack,” Eisen Co-founder and CEO Allen Osgood wrote in a blog post announcing the investment. “Eisen’s platform now covers escheatment, disbursement, and 1099 reporting. Operational teams use Eisen to replace manual work and prevent dormant-account risk. Executives use it to reduce regulatory exposure, retain customer assets, and protect customer trust.”

Last year, Eisen prevented more than 31% of at-risk assets from being lost to state custody. The company monitors nearly $16 billion in balances across tens of millions of accounts at firms including Adyen, Binance.US, BitGo, and PeoplesBank. Eisen’s platform integrates state-by-state requirements directly into account operations, enabling financial institutions to identify dormancy risk earlier, reduce manual compliance work, and keep more customer assets in customer accounts.

“Every dollar in state custody represents a real person who never expected their money to disappear,” Osgood added. “The rules governing dormant assets weren’t built for crypto wallets, fintech platforms, or digital-first banking. Most institutions are sitting on 5x to 10x more liability than they realize. Eisen prevents that loss before it happens.”

Founded in 2021, Eisen made its Finovate debut at FinovateFall 2024 and returned to the Finovate stage earlier this year at FinovateSpring 2026 in San Diego. At the conference, the company demonstrated its Eisen Dashboard, a real-time compliance command center that features account-level detail views with state-specific rules, eligibility and due diligence tracking by reporting year, a disbursement hub with daily reconciliation and fraud protection, and an outreach hub to manage owner communications. Eisen is headquartered in New York.


Photo by Kanhaiya Sharma on Unsplash