This site is operated by a business or businesses owned by Informa PLC and all copyright resides with them. Informa PLC's registered office is 5 Howick Place, London SW1P 1WG. Registered in England and Wales. Number 8860726.
Finovate Blog
Tracking fintech, banking & financial services innovations since 1994
Digital bank OnePay is allowing select US customers to fund their checking accounts using USDC stablecoins across 12 blockchains, automatically converting deposits into US dollars.
Stripe-owned Bridge powers the stablecoin deposit functionality, offering an alternative to traditional account funding methods such as ACH transfers.
The launch follows OnePay’s recent agentic banking and MCP integration announcements as the Walmart-backed fintech continues to expand its digital financial services offerings.
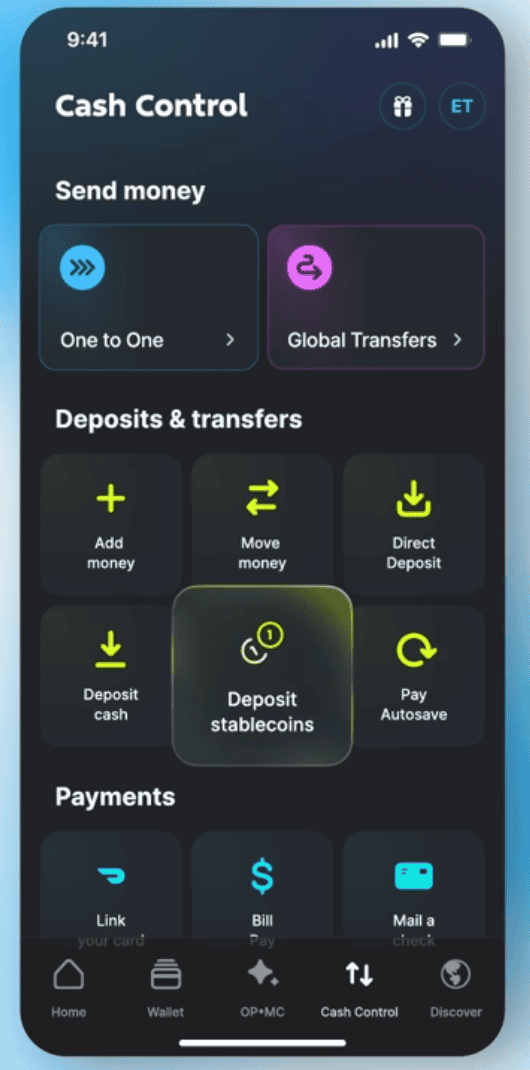
Digital bank OnePayannounced this month that it is allowing select US customers to fund their OnePay checking accounts using stablecoins and receive the value as US dollars, all without requiring a separate crypto account or wallet.
Users can fund their accounts by sending stablecoins from an external wallet to a deposit address, and OnePay converts the funds to US dollars and credits the funds to their checking account within moments, depending on the network used and required checks. The feature is launching with support for USDC across 12 blockchains, including Tempo, Base, Solana, and Ethereum. OnePay notes that it will not charge conversion fees at launch, and while it does not charge a service fee, blockchain networks may impose network fees on consumers.
Supporting the behind-the-scenes fund transfer is Stripe-owned Bridge, a stablecoin orchestration platform that creates and secures deposit addresses, monitors incoming blockchain transactions, and facilitates the conversion of stablecoins into US dollars. The integration allows OnePay to offer stablecoin deposits without requiring customers to manage a separate crypto account within the app. In this sense, Bridge provides an alternative to traditional bank account funding methods such as ACH transfers, enabling customers to move funds over blockchain networks while receiving the value in dollars in their checking accounts.
OnePay anticipates that the new stablecoin capability will support the growing number of freelancers, gig workers, and overseas employees who receive payment in stablecoins. OnePay’s new launch removes complexity for these users by enabling them to deposit crypto and receive dollars out that they can use to pay bills, send money, and save.
For OnePay, the move integrates blockchain-based payment rails into everyday banking. While stablecoins are not replacing traditional payment systems such as ACH, they are emerging as an alternative for moving money, particularly across borders. By converting stablecoins directly into spendable dollars, OnePay is leveraging blockchain infrastructure without requiring consumers to interact with cryptocurrency within OnePay. The launch is also an example of a new approach to account funding in which stablecoins serve as an underlying payment mechanism rather than a standalone financial product.
The release of this feature follows OnePay’s agentic banking announcement last month. The New York-based company will offer eligible customers the option to give their AI agent access to spend and manage funds, as well as buy and sell crypto. Also last month, OnePay added an MCP connection to allow users to connect their OnePay accounts to their AI tool.
Founded in 2019, Walmart-backed OnePay offers a range of financial services, including checking and savings accounts, debit and credit cards, buy now, pay later (BNPL) financing, and credit-building tools. The company has also expanded into investing and cryptocurrency trading, allowing customers to buy and sell stocks and digital assets through its app. OnePay partners with financial institutions and technology providers to deliver its services, including Coastal Community Bank, Lead Bank, Synchrony Bank, Klarna, and DriveWealth.
Digital banking platform Revolutannounced today that it has officially launched in New Zealand as a bank after the Reserve Bank of New Zealand registered Revolut Bank New Zealand Limited. This registration makes Revolut the country’s 27th registered bank and its first digital bank.
The new registration, which comes three years after Revolut first began operating in New Zealand as a financial services provider, allows Revolut to launch Instant Access Savings accounts, with eligible deposits up to NZ$100,000 now protected by the New Zealand Depositor Compensation Scheme (DCS). The new Instant Access Savings accounts feature a 3.50% variable introductory savings rate for four months.
“Launching our New Zealand bank marks another significant step in our mission to build the world’s first truly global bank,” said Revolut Founder and CEO Nik Storonsky. “Securing our seventh bank license and our fifth this year alone is a testament to our business model and our team. We are confident our offering will bring true competition to the New Zealand banking sector.”
Along with Revolut’s official move into New Zealand, the fintech committed to investing NZ$120 million into the local market over the next five years. Revolut aims to offer solutions that enhance the financial wellbeing of New Zealand residents and hopes to bring competition to the region’s market, which has long been dominated by traditional players.
“Becoming a bank in New Zealand marks a defining moment in our journey, achieved through a relentless focus on delivering a better financial experience for Kiwis,” said Revolut Bank New Zealand CEO Ryan Brosnahan. “Since launching here in 2023, we have experienced massive growth. It’s clear the market is primed for disruption, and this licence is the launchpad for our next chapter to build the most seamless, secure, and customer-first banking experience in New Zealand.”
With more than 80 million customers worldwide, UK-based Revolut now holds seven banking licenses and operates as a licensed bank in 34 geographies, including the UK, Europe, Australia, and now New Zealand. The company recently secured new licenses and authorizations in the UAE, Mexico, Colombia, and Peru; has advanced its US bank charter application with the OCC; and received approval to acquire Banco Cetelem in Argentina. In 2015, Revolut CEO Storonsky demoed the company’s banking platform at FinovateEurope in London.
Revolut’s entry into the New Zealand market broadens its reach as a global banking competitor. While other international digital banks, such as Brazil-based Nubank, have largely focused their expansion efforts on specific regions, Revolut is pursuing a more geographically diverse strategy. Securing banking licenses across multiple continents positions Revolut to compete directly with traditional financial institutions, rather than simply offering an alternative digital financial services platform.
Cloud-native banking platform 10x Banking and lending technology platform ezbob have partnered to help banks launch SME lending products faster.
Via the partnership, 10x Banking will provide modular core and ledger capabilities, while ezbob provides onboarding orchestration, application handling, credit decisioning, and AI agents.
Both companies are headquartered in London. 10x Banking won Best of Show in its Finovate debut at FinovateEurope 2023. ezbob made its Finovate debut at FinovateEurope 2014.
Helping banks launch SME lending products in weeks rather than months is the goal of a newly announced strategic partnership between 10x Banking and ezbob.
“Banks are too often asked to choose between a broad suite that is difficult to adapt and a collection of point solutions that never quite connect,” 10x Banking Chief Product & Technology Officer Okan Ozaltin said. “Neither gets a lender to market quickly. Bringing our core and ledger together with a specialist origination platform gives them a faster, lower-risk route to market and the flexibility to keep evolving it afterwards. SME lending is where customers can get the most value, which is why we are starting there.”
10x Banking and ezbob are focused on closing what they called “one of the most persistent digital experience gaps in UK financial services” in their partnership announcement. The companies noted that while incumbent banks have digitalized and automated simpler retail customer journeys, modernizing SME lending has been a slower process. These challenges reflect both the greater complexity of SME lending compared to retail lending and the limitations of systems built on workflow tools or legacy cores that fail to create a connected customer journey.
The partnership combines 10x Banking’s cloud-native banking platform with ezbob’s lending technology. 10x will provide the modular core and ledger, while ezbob will orchestrate onboarding, application handling, credit decisioning, and AI agents. Open integration enables specialist components to be connected without forcing a bank into a single closed suite. Shared components can be reused to introduce additional lending products instead of building a new silo each time. Together, 10x Banking and ezbob are providing banks with the ability to launch new SME lending products quickly, shortening time to market and time to value.
“We built ezbob to digitize the lending journey itself, rather than automate an internal process on top of systems that were never designed for it,” ezbob Chief Technology Officer Yaron Shoshani said. “Pairing that with a tier-one bank-grade core means a lender can launch a complete SME product, automate decisions where policy allows, and reuse the same components to add further lending products instead of building a new silo each time.”
Founded in 2016 and headquartered in London, 10x Banking won Best of Show in its Finovate debut at FinovateEurope 2023. With deployments at Chase UK, Old Mutual, and Westpac, 10x Banking’s platform provides a fast, cost-effective, and de-risked path to full modernization, enabling banks to scale, launch new products, streamline operations, leverage real-time data, and integrate seamlessly across their technology ecosystems. 10x Banking announced in October that it had partnered with intelligent document and accounts payable automation company Tungsten Automation to provide the core ledger behind Tungsten’s new embedded payments offering, Pay+. Antony Jenkins is 10x Banking’s founder, chair, and CEO.
London-based ezbob made its Finovate debut at FinovateEurope 2014. Earlier this year, the company announced that its lending platform had been selected for availability on IBM Power Cloud. This gives banks running on IBM AS/400 and IBM Power systems access to a modular, AI-driven digital lending platform without requiring a full-scale legacy core system replacement.
“Our platform’s flexibility, along with our experience deploying across public cloud, virtual private cloud, and on-premise environments, made ezbob a natural choice for this initiative,” ezbob Sales Director Francesco Manitta wrote in a LinkedIn post.
Inventory financing fintech Settle has secured up to $100 million in a forward-flow financing agreement with crypto-native structured credit platform 3Jane, beginning with $50 million in financing capacity.
The agreement will allow Settle to sell eligible loans to 3Jane on an ongoing basis, freeing up capital to originate additional loans and expand its lending operations.
The deal leverages stablecoin liquidity to finance real-world lending and follows Settle’s recent $240 million credit facility aimed at expanding its financing offerings.
Inventory financing fintech Settle has secured up to $100 million in a forward-flow agreement today. In a deal with 3Jane, the agreement provides $50 million initially with the option to expand to $100 million.
Today’s agreement follows Settle’s announcement last month that it secured a $240 million credit facility from an international financial institution and a New York-based asset manager. That facility aimed to help Settle serve larger businesses and expand its financing offerings. The company also previously secured a $280 million revolving credit facility in 2022 and a $145 million credit facility in 2023.
3Jane is a crypto-native structured credit platform that provides capital to fintech lenders through a revolving conduit powered by blockchain technology. As part of the agreement, 3Jane has already purchased $18 million of Settle’s existing loans and has committed to purchasing eligible new loans on an ongoing basis.
The forward-flow arrangement will allow Settle to recycle capital into new loan originations rather than holding existing loans on its balance sheet until maturity, enabling the company to scale its lending operations.
The deal highlights a growing connection between traditional lending and blockchain-based finance. Tapping stablecoin liquidity to fund loans to consumer brands allows 3Jane to connect digital asset capital with real-world credit demand. Additionally, the deal gives Settle an alternative source of financing as it expands its lending operations.
Founded in 2019, Settle has provided more than $4 billion in funding to thousands of consumer brands and ecommerce businesses. Its financing solutions help businesses pay for inventory purchases and supplier invoices upfront, with repayment through extended payment terms or scheduled installments. In addition to lending, Settle offers a suite of cash flow management tools, including bill pay, accounts payable automation, and invoice tracking.
Settle CEO and Founder Alek Koenig emphasized the importance of helping consumer brands finance inventory purchases before generating revenue from sales. “The forward flow with 3Jane gives us a more capital-efficient way to finance that gap at scale,” Koenig said. 3Jane CEO Jacob Chudnovsky highlighted the role of stablecoin liquidity in supporting Settle’s lending operations, noting that the financing structure is designed to lower Settle’s borrowing costs. “Settle has built a lending business serving thousands of consumer brands,” Chudnovsky said.
The big event is still months away (May 3 through 5, 2027), but we’re already looking forward to returning to Southern California for three days of live fintech demonstrations and insightful thought leadership on banking and financial services. We’ve even switched to a new venue to enable attendees to take full advantage of everything sunny Southern California has to offer.
Our spring conference will feature many familiar favorites. Our pre-event Leaders+ session is back, with an invite-only briefing and networking evening for bankers, asset managers, and insurers. We’ll also host a series of executive briefings on Women in Fintech, community banking, and credit unions. And Finovate would not be complete without our live demos, Analyst All Stars, Investor All Stars, and industry stages.
FinovateSpring 2027 will also feature a number of new attractions designed to help you stay informed on the latest innovations and emerging trends in fintech. Here’s a brief preview of what we have in store:
AI: From experimentation to application
AI is moving rapidly from experimentation to real-world application. What do banks and other financial institutions need to do in order to take their AI projects from pilot to deployment in real financial workflows? FinovateSpring will feature power panels on the agentic revolution, an executive briefing on AI deployment success stories, and keynote addresses on the rise of agentic banking, the importance of Know Your Agent (KYA), and the relationship between open banking, open finance, and AI.
Stablecoins: Opportunities and challenges for banks
The rise of stablecoins has been another significant development in banking and financial services in recent years. From facilitating cross-border payments to enabling programmable finance, stablecoins have become one of the most compelling technologies to emerge from the world of digital assets.
What does the proliferation of stablecoins mean for banks and other financial institutions? How will they affect deposits and the economics of lending, and what does it mean when customers have even more flexibility to separate deposits, payments, and financing? FinovateSpring 2027 will host an invite-only keynote on stablecoins during the Leaders+ session and feature fireside chats in the plenary on what banks need to do in order to develop a stablecoin strategy and maximize the new opportunities in digital money.
New industry stages: The Intelligent Bank / The Future of Money / Trust, Risk, and Growth
Another big change for FinovateSpring 2027 is the rebranding of our industry stages. As AI, embedded finance, open banking, and digital assets blur the lines between traditional industry boundaries, Finovate has evolved to help attendees better understand the relationships between emerging technologies and the problems they solve.
Our Intelligent Bank stage will feature keynote addresses and power panels on how to build a bank that is more adaptive and efficient, scale AI projects from proof of concept to production, overcome the challenges of legacy modernization, and understand what the wave of new bank charters tells us about the future of the banking stack. Our Future of Money stage will feature discussions on everything from agentic payments and the economics of embedded finance to use cases for stablecoins and tokenized deposits. Our Trust, Risk, and Growth stage will offer deep dives into the relationships between banks and their customers in the age of agentic AI, as well as the challenge of innovating responsibly at a time of rapid technological change.
FinovateSpring 2027 comes to the Gaylord Pacific Resort & Convention Center in Chula Vista, California, May 3 through 5. Register by Friday, November 6 and save up to $600.
It’s a new month and time for some fresh banking news and fintech developments. The biggest headline to start the week is OPay’s withdrawal from its IPO. Here’s a look at what else fintechs are up to in this week’s list of the top news. We’ll continue to update this post with news throughout the week.
Payments
Paysafeappoints gaming industry veteran Rob Schonfeld as Chief Revenue Officer.
Embedded finance platform Brim Financial has teamed up with Manulife Bank.
The bank will deploy Brim Financial’s embedded technology to provide its employees, bankers, advisors, and customer-facing teams with intelligent capabilities and seamless digital workflows.
Founded in 2016, Brim Financial made its Finovate debut at FinovateFall 2024 in New York. The company is headquartered in Toronto, Ontario, Canada.
Brim Financialannounced a partnership with Manulife Bank to help the bank transition its credit card portfolio and modernize its platform. Brim offers an intelligent, configurable operating model that combines issuing, processing, servicing, loyalty campaigns, and customer engagement capabilities. This enables banks and other financial institutions to embed cards and payments within their digital ecosystems.
The partnership will help Manulife transition away from fragmented, legacy issuer stacks and toward vertically integrated platforms. These platforms support faster product innovation, streamlined operations, and more connected customer journeys.
“Brim helps banks move beyond fragmented card and payments architectures with a more integrated approach,” Brim Financial Founder and CEO Rasha Katabi said. “Financial institutions globally are reassessing their modernization strategies and their go-to-market approach. They are recognizing the limitations of the traditional approach where attaching together multiple vendors can slow down innovation and increase costs. Partnering with Manulife Bank reflects how institutions are delivering an embedded, more efficient and future-ready platform that enables speed, control, and growth.”
Brim’s platform will enable Manulife to embed credit and payments natively within its digital ecosystem, support enterprise-wide lifecycle customer engagement at scale, accelerate product innovation and configurable launch capabilities, as well as drive operational efficiency via an integrated platform model. Brim’s embedded customer journeys will also support Manulife’s independent advisors, mortgage specialists, and customer-facing teams, helping them drive growth and enhance customer relationships.
“This partnership enables Manulife Bank to deliver a more cohesive, transparent, and personalized digital experience for our customers, supported by insights that make everyday banking simpler,” Manulife Bank President and CEO Katy Boshart said. “Brim’s modern, flexible technology strengthens our digital foundation and supports our transformation journey—creating a platform that evolves with the needs of Canadians.”
Manulife Bank of Canada (Manulife Bank) is a wholly owned subsidiary of The Manufacturers Life Insurance Company, which is a subsidiary of Manulife Financial Corporation. Established in 1993 and headquartered in Waterloo, Ontario, Manulife Bank was the first federally regulated bank opened by an insurance company in Canada. The financial institution serves customers in all Canadian provinces and territories and has C$34.8 billion in total assets as of Q2 2026.
Founded in 2016 and headquartered in Toronto, Ontario, Brim Financial made its Finovate debut at FinovateFall 2024 in New York. At the event, the company demonstrated its turnkey business and commercial cards and payments platform that enables financial institutions to offer scalable solutions to business customers as they grow. The platform integrates with existing digital banking infrastructure and features multi-product capabilities, including business and virtual cards, payments, invoicing, accounting integration, enterprise workflows, and more.
Issuer-merchant network Kipp has been acquired by an investor group led by The Lifetime Value Company (LTVCo) and its founders. Terms were not disclosed.
The acquisition will support Kipp’s US expansion, technology investments, and efforts to grow its network of issuer and merchant partners.
Kipp will continue to operate independently under its existing leadership, helping merchants recover declined transactions while giving issuers control over risk and pricing.
Issuer-merchant network Kipp has been acquired by an investor group led by The Lifetime Value Company (LTVCo) and its founders. Terms of the deal were undisclosed.
Kipp anticipates that the acquisition will offer it long-term financial backing and has made it clear that the new owners will help it pursue continued growth by providing the resources to expand its US presence, invest in its technology, and further build its partnerships with issuers and merchants.
Founded in 2021, Kipp creates a bridge between merchants and issuers by allowing merchants to pay for transactions that would otherwise be declined due to insufficient funds. It also gives issuers full control over which transactions they approve and the premium price they require to take on the additional risk. Using Kipp, up to half of transactions that otherwise would have been declined can be approved without imposing additional friction or cost to the end consumer.
“Our focus now is expanding our US issuer and merchant network and bringing more transactions onto the platform,” said Kipp CEO and Co-founder Chanan Lavi. “This acquisition gives us the long-term backing and operational resources to accelerate that work while preserving what makes Kipp valuable: issuers control their risk, merchants recover sales, and consumers pay no additional fee.”
LTVCo is a technology and information services platform that holds a portfolio of consumer brands, including BeenVerified, Bumper, and Ownerly. Adding Kipp to its lineup will expand LTVCo’s reach into the payments industry, giving the company a foothold in the issuer-merchant ecosystem while supporting Kipp’s efforts to scale its technology and partnerships in the US.
“Every unnecessary decline costs a merchant a sale and an issuer a chance to remain the customer’s preferred card,” said LTVCo CEO and Co-founder Josh Levy. “We’ve seen that firsthand. Kipp aligns both sides to recover that revenue and deliver a better customer experience. We’re committed to building Kipp for the long term, with the financial strength and resources to invest in its technology, expand its network, and support its partners at scale.”
Kipp will continue to operate independently under the leadership of its co-founders, CEO Chanan Lavi and CTO Nir Levy.
This week’s edition of Finovate Global showcases recent fintech headlines from Hong Kong.
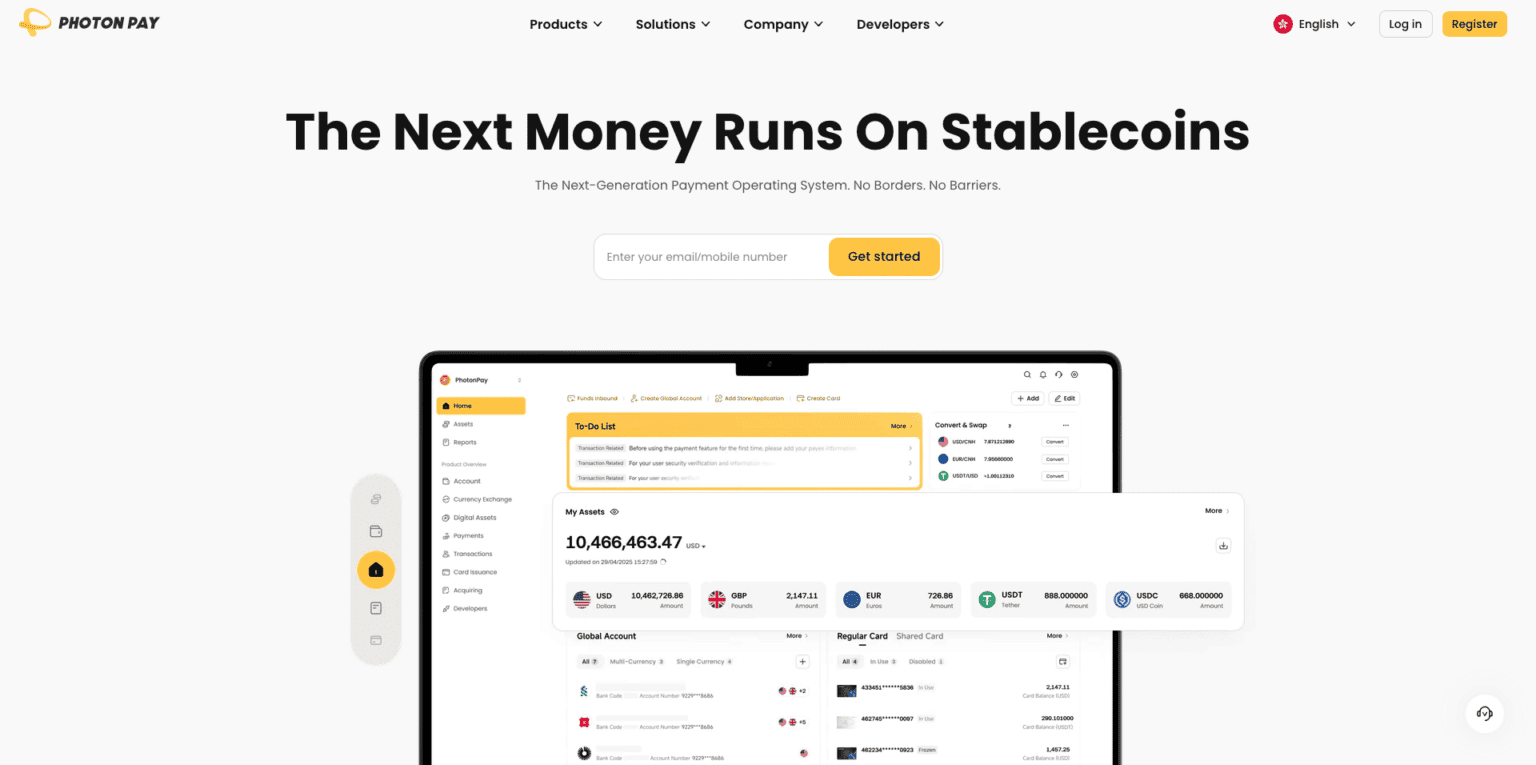
PhotonPay raises $40 million for its stablecoin-based financial operating system
Hong Kong-based fintech PhotonPay has secured $40 million in Series C funding this week. The round was led by Blockchain Capital. New investor SBI Group also participated, and existing investors IDG Capital, GL Ventures, and Lightspeed Faction provided follow-on investments. Blacksheep Technology served as the exclusive financial advisor to PhotonPay on the transaction.
The investment will support the expansion of PhotonPay’s stablecoin-centric Financial Operating System (Financial OS). The capital will enable the company to focus on enhancing its multi-asset wallet capabilities, expanding global card issuing, bolstering local clearing infrastructure in key markets, and creating an agent-ready financial execution layer.
“Moving money across borders in seconds means little if it still takes days to put that capital to work,” PhotonPay CEO and Founder Lewison Chen said. “Stablecoins are accelerating global money movement, while local clearing and global card issuing connect that liquidity to local settlement and everyday business spending. Our Financial OS brings these capabilities together, making the underlying infrastructure far less visible to businesses, even as it becomes more essential than ever.”
PhotonPay’s Financial OS combines multi-asset wallets, global money movement, foreign exchange, local clearing, and global card issuing through an integrated API-first architecture. This enables businesses to access the financial capabilities required to manage and deploy funds across markets. Stablecoins are also central to this architecture. Its multi-asset wallet connects stablecoin liquidity with fiat balances and integrates asset conversion, foreign exchange, and local clearing into a single workflow. In support of this dual-rail infrastructure, PhotonPay manages a global financial network that enables businesses to open local collection accounts in 17 markets and receive funds in more than 60 currencies.
“Connecting financial networks is only the beginning,” Chen added. “The real breakthrough is abstracting that complexity behind a unified, programmable financial layer, so businesses and AI agents can move from intent to execution within clearly defined boundaries.”
With 34 payment and financial licenses and regulatory authorizations across the Americas, Europe, and Asia, PhotonPay serves more than 200,000 businesses across 200+ countries and territories. As of August 2026, the company reported annualized transaction volume of $65 billion.
TCM Solutions partners with Tribe Payments
TCM Solutions (TCMS), a Hong Kong-based merchant acquirer, has announced a partnership with issuer and acquirer processor Tribe Payments. Through the partnership, TCMS will use Tribe’s cloud-native, API-led processing platform to launch more bespoke solutions for clients, serve a broader range of merchants, and expand into Singapore and other markets in the region.
“Our decision to partner with Tribe Payments reflects our ambition to build a scalable, future-ready acquiring business across Asia,” TCMS CEO John Lee said. “Our specialist focus on duty-free, cross-border payments and POS solutions requires a processing partner that combines robust technology with the flexibility to support our growth.”
TCMS serves merchants in several core verticals, including food and beverage groups, medical chain stores, airlines and airport duty-free retailers. Its payment systems are designed to accommodate individual outlet operations and their specific accounting requirements. TCMS’ expertise includes POS technology and Dynamic Currency Conversion (DCC), which enables eligible international customers to view and pay for transactions in their preferred currency at the point of sale.
“We are delighted to partner with TCMS as it continues to develop its acquiring business across Asia,” Tribe Payments GM Asia-Pacific Matt Weir said. “TCMS brings valuable expertise in duty-free and cross-border payments, supported by specialist POS and DCC capabilities. Our cloud-native platform is designed to provide the processing foundation, flexibility, and scalability needed to support TCMS’ ambitions, and to help deliver innovative payment solutions to merchants and their customers.”
London-based Tribe Payments offers banks, fintechs, and payment businesses a single, unified, cloud-native platform for issuer and acquirer processing, along with digital banking and account-based payment services. The company provides issuer and acquirer processing connected to Visa, Mastercard, American Express, UnionPay, JCB, and Discover. Tribe Payments also links its clients with banking partners through its Bank Connect solution, providing access to local payment rails in multiple markets and enabling businesses to generate customer IBANs or account numbers through a single API integration. Founded in 2018, Tribe Payments’ modular platform also supports digital banking, 3-D Secure, tokenization, and risk and fraud monitoring.
Hong Kong Fintech week focuses on transformation, fuel, and expansion
Hong Kong Fintech Week begins on Monday. This year, the theme of the event is “Fintech Nexus: Bridging the World, Building the Future”. That theme will be explored via three “core growth engines”: AI+, Finance+, and global expansion. The event will begin with opening remarks from John KC Lee, Chief Executive of the Hong Kong Special Administrative Region, and will feature forums on a range of topics, including AI and DeepTech, InsurTech and HealthTech, Digital Assets and Web3, among others.
The conference, which will run along with the StartmeupHK Festival 2026, anticipates hosting more than 45,000 participants from 120+ economies. More than 1,000 speakers, 800 exhibitors and startups, and more than 30 delegations are expected to attend.
Of particular interest are the three core growth engines that conference organizers have identified as central to Hong Kong’s fintech and financial services goals.
AI+ The conference agenda will examine how companies are moving beyond chatsbots to experiment with agentic aI, autonomous banking, robotics, and the economics of running large language models in regulated industries such as finance.
Finance+: The agenda will also explore how deep capital markets can be leveraged to commercialize cutting-edge innovations in areas like tokenization of real-world assets and stablecoins.
Global Expansion: The conference agenda will examine how technology firms based in mainland China to navigate international expansion and issues related to AI sovereignty. It will also help them bridge regional gaps via frameworks such as the Greater Bay Area (GBA) integration.
“As HKFW x SMUHK enters its second decade, Hong Kong begins a new chapter with its First Five-Year Plan, unveiled alongside the 2026 Policy Address,” InvestHK Director-General of Investment Promotion Alpha Lau said. “This year’s three engines—Finance+, AI+, and global expansion—reflect the city’s strategic priorities: driving innovation and economic development, transforming industries, and enabling multi-market growth. Hong Kong connects these forces, and this year’s event will bring together global innovators, investors, and enterprises to scale internationally and seize new opportunities through our city.”
Here is our look at fintech innovation around the world.
Apple Pay and Google Pay have arrived in Uzbekistan.
Pine Labs and Webxpay teamed up to bring India’s UPI to Sri Lanka.
Latin America and the Caribbean
ACI Worldwide and Circle Internet Group forged a partnership to support the integration of stablecoin settlement into existing bank infrastructure in Latin America.
Cloud-native banking infrastructure and embedded finance firm Mbanq secured an infrastructure deal with 40+ Haitian credit unions.
Mexican fintech Kapital secured approval to begin banking operations in Colombia.
Asia-Pacific
Visa and Tencent signed a Memorandum of Understanding (MoU) on agentic commerce and cross-border payments.
The central banks of Thailand and Malaysia announced their support for Singapore’s cross-border digital money initiative BLOOM, which stands for Borderless, Liquid, Open, Online, Multi-currency).
Expanding access to credit is a key component of the push for greater financial inclusion. Much of the innovation in the lending space has been focused on developing more accurate ways to find creditworthy borrowers among the unbanked and underbanked. Technology has helped, but so has a shift in lenders’ understanding of creditworthiness, particularly as more workers earn income outside traditional forms of employment as self-employed or seasonal workers, or through the often-irregular work of the gig economy.
This year at FinovateFall 2026, we talked with Jaron Murphy, Head of Partnerships at FICO Scores about why cash flow data is important, and why the distinction between a borrower’s “ability to pay” from their “willingness to pay” can be a key element in establishing creditworthiness. We also discussed the company’s UltraFICO Score partnership with Plaid, launched earlier this year, and how the combination of credit and cash flow data provides a more complete picture of a borrower’s finances.
“When you look at credit data and the credit report, it really shows what I call ‘willingness to pay.’ It’s looking at behavior to understand how willing the consumer is, based on past behavior and debt obligations, to repay this debt. There’s another part that’s always been missing though, and it’s that cash flow aspect. It’s the ability to pay, not just the willingness, but what is the consumer’s ability to pay, as well? That’s what really excites me about where we’re at today is being able to leverage cash flow data to understand consumers in new ways. And that’s what we’ve been embarking on.”
Jaron Murphy is Head of Partnerships at FICO Scores. In this capacity, he works with strategic partners across mortgage, consumer lending, and auto lending to expand the reach of FICO scoring. Murphy develops partnerships and distribution channels that get FICO Scores into new hands, whether by expanding the reach of innovative offerings like UltraFICO, partnering with existing ecosystem players, or opening up new markets.
Founded in 1956 and based in Bozeman, Montana, FICO leverages predictive analytics and data science to help financial institutions, insurers, and other companies make better operational decisions. FICO’s solutions help businesses defend themselves against fraud, advance financial inclusion, enhance risk management, improve credit access and transparency, and more. The FICO Score is the standard measure of consumer credit risk in the US and is used by 90% of the top US lenders. FICO was a Grade 4 sponsor of FinovateFall 2026.
Casap raised $56 million in Series B funding, bringing its total funding to $90 million, to expand its agentic AI platform for financial services operations.
Casap’s AI agents are delivering measurable results, helping more than 100 financial institutions reduce fraud losses, accelerate dispute resolution, and automate complex workflows while maintaining human oversight.
The funding reflects growing investor confidence in agentic AI as financial institutions move beyond basic task automation toward AI systems capable of executing complex, highly regulated workflows.
AI agent platform for financial services Casapraised $56 million this week to help combat fraud and payment disputes. The Series B funding round was led by Base10 Partners, with strategic participation from Experian and Synchrony and additional support from existing investors including Emergence Capital and Lightspeed Venture Partners.
Today’s round, which comes just over a year after Casap raised $25 million in its Series A round, brings the California-based company’s total funding to $90 million. Casap will use the funding to advance its AI platform that combines AI agents, industry expertise, and forward-deployed teams to transform operations such as disputes and fraud to collections, claims, and more.
Casap was founded in 2023 by former Robinhood executive Shanthi Shanmugam and former Chime executive Saisi Peters to streamline complex financial services operations. The company’s platform uses specialized AI agents to investigate cases, make decisions, and take action across financial institutions’ existing systems. The agents follow institution-specific policies and procedures, maintain auditable records of their decisions, and escalate cases requiring human judgment. Since launching with a focus on fraud and payment disputes, Casap has expanded into other operational areas, including collections, claims, and complex exceptions. The company has also grown its revenue tenfold over the past year, more than double its original target. Casap took home Best of Show honors for its demo at FinovateFall 2025.
“We started with disputes because it was one of the hardest problems in financial services,” said Casap CEO and Co-founder Shanthi Shanmugam. “But our ambition was always bigger than disputes. We wanted to prove that AI could do more than make work more efficient. It could fundamentally change the outcomes for financial institutions. Today we’re cutting fraud losses in half while resolving disputes in days instead of months. Now our customers are asking us to bring that same transformation to the rest of their operations.”
Casap works with more than 100 financial institutions and has helped them:
Reduce first-party fraud losses up to 51%
Achieve a 96% chargeback win rate (compared with a 60% industry average)
Reduce resolution time from as long as 90 days down to 8 days
Resolve 73% of dispute cases through agentic automation while retaining human oversight
Reduce human processing time from 45 minutes to 1 to 2 minutes
“We’ve been told for years that financial institutions will have to make a tradeoff between operational economics and experience quality,” said Base10 Partners Managing Partner Adeyemi Ajao. “Casap has shown that agentic AI technology can change that tradeoff. The same technology lowers the cost of complex work, while improving speed, quality, and consistency. Disputes proved that model in one of the hardest environments in financial services, and we believe the opportunity now is much larger.”
Casap’s latest funding round reflects growing investor confidence in agentic AI’s ability to move beyond simple task automation and deliver measurable operational outcomes in financial services. Fraud and disputes are particularly compelling use cases because they involve complex workflows, regulatory requirements, and significant manual intervention. Casap’s broader adoption across banking operations is promising because its AI agents can handle routine processes while maintaining human oversight. The company’s expansion into collections, claims, and other functions also signals a larger shift in how financial institutions may approach automation, moving from tools that assist employees to systems that can execute entire workflows.
Fintech innovation depends on more than good technology. Startups need capital, customers, and industry expertise to grow. Investors need to identify promising companies and emerging opportunities. Financial institutions need solutions that address evolving business challenges.
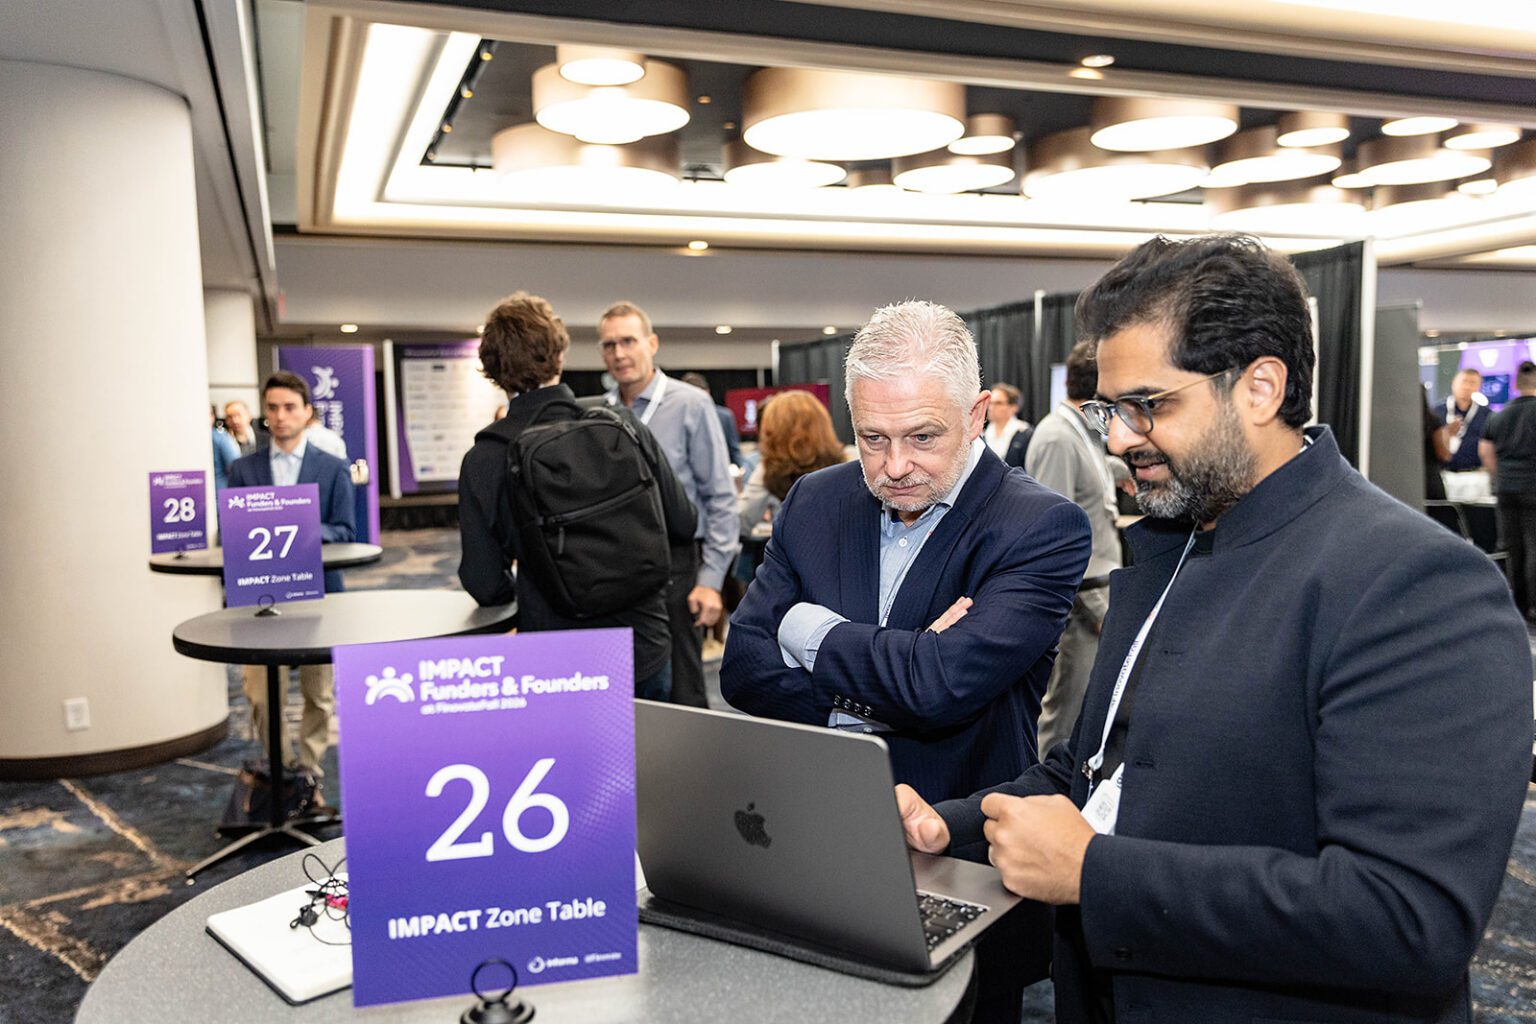
IMPACT Funders & Founders brings these groups together on May 5, 2027, in San Diego to build relationships, exchange insights, and explore what’s next in fintech. Co-located with FinovateSpring, May 3 through May 5, IMPACT also connects participants with a broader community of financial services innovators.
Connections that support growth
IMPACT brings startups, scaleups, and investors together for curated one-to-one meetings based on funding stage and investment focus. Content sessions and Pulse Check roundtables complement these conversations with industry insights, market perspectives, and peer exchange. Explore the benefits for startups.
For investors, Startup Spotlight pitches and IMPACT Zone exhibitors offer additional ways to discover promising companies, explore emerging technologies, and grow their investment pipelines. Both formats provide opportunities to connect with founders and identify businesses aligned with investment strategies. Explore the benefits for investors.
Co-location with FinovateSpring extends these opportunities across the financial services ecosystem. Access to the shared Exhibit Hall on May 5 gives financial institutions a chance to discover new fintech solutions and meet emerging technology providers, while startups can connect with potential customers and explore new routes to market.
Building on the IMPACT community
At the 2026 event, IMPACT facilitated more than 225 meetings and delivered over 275 minutes of content, with more than 200 investors and startups registered. In 2027, IMPACT will bring the fintech community together again for focused meetings, startup pitches, and industry discussions with the added opportunity to engage with FinovateSpring’s financial services audience.