Clara Raises $105 Million to Grow Latin American Corporate Spend Management Platform

Clara Raises $105 Million to Grow Latin American Corporate Spend Management Platform
  • Clara raised $105 million, comprising a $65 million Series C equity round and the renewal of a $40 million growth financing facility, bringing its total debt and equity funding to $838 million.
  • Clara will use the funding to expand its market reach and enhance its AI capabilities, including its MCP integration that enables AI agents to access financial data and execute authorized transactions.
  • The funding comes amid global growth in corporate card and spend management platforms, as providers expand beyond payments and expense tracking to offer integrated, AI-powered financial management tools.

Brazil-based spend management platform Clara raised $105 million this week. The round is comprised of $65 million in equity in a Series C round and the renewal of a $40 million growth financing facility from General Catalyst’s Customer Value Fund (CVF).

The $65 million Series C was anchored by Citius, Kaszek, and DEG, a subsidiary of Germany’s KfW Group. The round also attracted participation from 10 existing investors and three new investors, including CMT Digital and Nascent VC.

The latest investment brings Clara’s total debt and equity funding to $838 million, following several debt financing deals over the past year. In November 2025, Clara secured $70 million in structured debt financing from BBVA Spark, Covalto, and the International Finance Corporation (IFC). Three months later, the company renewed a $150 million credit facility with Goldman Sachs, bringing its total debt capacity to more than $250 million.

Clara will use today’s funding to expand its go-to-market team and strengthen the automation and AI capabilities of its platform. Clara was founded in 2020 and now helps more than 45,000 businesses automate routine work, control spending, and make better financial decisions. The company’s platform offers corporate cards, bill payments, spend management, accounts payable, and accounts receivable to help businesses make and manage payments. Along with the financing announcement, Clara said it has also surpassed $100 million in annualized net revenue and maintained positive EBITDA for more than a year.

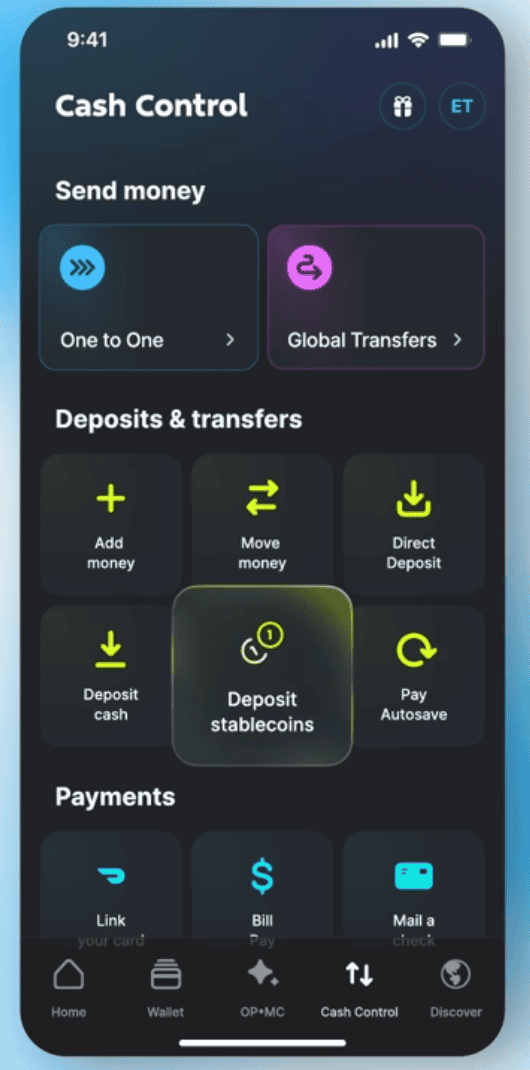
Among Clara’s capabilities is its Model Context Protocol (MCP) integration, which connects the platform with AI agents to enable customers to access real-time spending reports and forecasts using natural language, as well as execute authorized transactions autonomously. The company also offers AI-powered policy enforcement that checks employee expenses against company policies in real time, global spend management tools that allow businesses to manage expenses across countries and currencies, and fleet management solutions that support fuel payments and vehicle operations.

“Clara exists to champion Latin American businesses, and we work tirelessly to give them the tools to compete and win on the global stage,” said Clara Co-Founder and CEO Gerry Giacomán Colyer. “The region has long been underserved by financial platforms designed for other markets. We’re combining AI with local expertise to solve challenges specific to doing business here and give our customers a distinct competitive edge.”

Clara’s latest funding comes as spend management platforms increasingly look beyond corporate cards and expense tracking. By combining payments, financial data, and AI-driven automation, Clara is positioning itself to help businesses manage not just how they spend money, but how they make financial decisions.

The news of Clara’s growth comes as corporate card and spend management fintechs around the world are expanding their customer bases as well as their offerings. Companies such as Ramp and Brex in the US, Pleo and Payhawk in Europe, and Airwallex in Asia-Pacific have expanded beyond corporate cards to offer more comprehensive financial management platforms. These providers have integrated payments, expense management, accounts payable, and AI-powered automation into a single offering. Clara is following a similar trajectory in Latin America, where its regional focus and growing suite of financial tools position it to compete for businesses looking to consolidate and automate their financial operations.
Photo by Ryan

Wise Launches Interest and Stocks Products for US Customers

Wise Launches Interest and Stocks Products for US Customers
  • Wise launched Wise Interest and Wise Stocks in the US, allowing customers to earn potential returns on their balances while maintaining access to their funds for everyday spending and transfers.
  • The new investment products mark Wise’s first use of its US broker-dealer license, expanding its offerings beyond cross-border payments and traditional interest-bearing balances.
  • The launch reflects a broader fintech rebundling trend as Wise seeks to deepen customer relationships, retain more customer assets, and evolve into a more comprehensive financial services platform.

International money transfer platform Wise revealed its newest plan to retain user deposits. The UK-based company is expanding its product offering in the US to include new Wise Interest and Stocks, two new vehicles that enable users to earn a return on the funds they hold in the Wise platform.

Wise Interest invests customers’ USD balances in a BlackRock Treasury money market fund. The fund calculates returns daily and pays out interest monthly. Wise Stocks allows customers to invest their USD balances in an S&P 500 index fund to provide exposure to US equities. With both Wise Interest and Stocks, users maintain instant access to their funds and are able to transfer funds and use the funds for spending with no penalties. While Wise warns that the new products come with a risk of loss, it also notes that over 90% of returns earned may be exempt from state and local income taxes.

“In the US, earning a competitive return too often means locking your money away or juggling multiple accounts,” said Wise Head of Product for North America Vinay Nilakantan. “But with Wise Interest and Stocks, people and businesses in the US no longer have to choose between making their money work harder and actually being able to use it. They have the freedom to do both.”

Wise has been paying interest on users’ balances since 2023, when it launched Basic Interest, a tool that pays eligible US customers interest through a partner-bank arrangement. The company’s users have made good use of that feature, increasing the interest income earned by almost 17% year over year in FY26.

The announcement marks Wise’s first use of its US broker-dealer license, which the company acquired in April 2025 through its subsidiary Wise US Assets Inc., a SIPC Member that protects securities customers of its members up to $500,000 (including $250,000 for claims for cash). The launch expands Wise’s US offering beyond payments and traditional interest-bearing balance.

Wise was founded in 2011 under the name TransferWise to facilitate cross-border payments while bringing transparency to the fees involved. The company serves 19 million active customers worldwide, processing over $243 billion in cross-border transactions and saving customers more than $3.3 billion. According to Nilakantan, Wise customers have started using the platform to hold more liquidity. “People and businesses around the world are keeping more money with Wise than ever. Global customer holdings grew 40% to $39 billion last financial year alone,” said Nilakantan. “Now, we want to offer Wise customers more ways to put that money to work, without compromising the convenience and flexibility they expect from us.

Today’s announcement adds investment-based options to offer users a wider variety of choices. Wise’s customers can hold and convert more than 40 currencies, get paid in nine currencies, send money internationally with 77% of payments arriving within 20 seconds, and spend around the world with the Wise Multi-Currency Card.

Interestingly, Wise built its business on moving money across borders, but its latest strategy is focused on giving customers a reason to keep their money in one place. The move could help Wise deepen customer relationships, increase retention, and capture a larger share of customers’ financial activity. It also reflects the rebundling trend that has been taking place in fintech lately. Fintechs that initially focused on a single financial service are increasingly expanding their offerings to become more comprehensive financial platforms.

Canada Launches Real-Time Payments System, the Real-Time Rail

Canada Launches Real-Time Payments System, the Real-Time Rail
  • Payments Canada has launched its Real-Time Rail (RTR), enabling financial institutions and payment service providers to exchange, clear, and settle payments instantly, 24/7.
  • The new system includes mandatory centralized fraud prevention capabilities and is expected to generate up to $14.5 billion in cost savings and $27 billion in economic gains over the next decade.
  • RTR will roll out in phases, with more than 90% of Canadians expected to have access within the first year, laying the groundwork for new payment innovations.

For years, Canada has been considered behind when it comes to banking innovation when compared to its counterparts in the US, Europe, the UK, and even Australia. Specifically, Canada has been slow to create and adopt its own real-time payments rails.

Today, that finally changes for the Great White North. Payments Canada announced the launch of the Real-Time Rail (RTR), a national payment system that enables instant payment and settlement, real-time cash-flow visibility, and data-rich messaging on existing banking and payment channels. Specifically, the RTR will enable participating members such as financial institutions, credit unions, and payment service providers, to exchange, clear, and settle payments in real time 24 hours a day, every day of the year.

One advantage of Canada’s delayed launch is that the country has had the opportunity to learn from the experiences of earlier real-time payment systems. Notably, RTR is launching with mandatory centralized fraud prevention capabilities, including confirmation of payee and transaction risk scoring, offering a coordinated approach to mitigating fraud as instant payments become more widespread.

The RTR is owned and operated by Payments Canada, a public-purpose organization that owns and operates Lynx, a high-value payment system; the Automated Clearing Settlement System, its retail batch payment system; and now the RTR. The new real-time rails were built in partnership with CGI, Deloitte Canada, IBM Canada, and Interac Corp., and leverages ISO 20022 data-rich messaging.

“The launch of Canada’s Real-Time Rail marks the beginning of a new era for payments in our country,” said Payments Canada President and CEO Susan E. Hawkins. “As a national asset that’s designed specifically for our country, the RTR gives the payment ecosystem a modern foundation to build on. By collectively leveraging this rail, our ecosystem will unleash its full potential, enabling our members to build capabilities that drive innovation, resilience and growth for businesses and consumers across the nation.”

Payments Canada anticipates the RTR will save costs and improve economic growth in Canada over the next decade. The C.D. Howe Institute estimates that the real-time rails will generate up to $14.5 billion in cost savings from lower processing costs, reduced use of cash and cheques, and reduced float. What’s more, the RTR could generate up to $27 billion in economic gains as new functionalities are introduced in the future.

At launch, RTR is rolling out on a deliberately sequenced basis, beginning with Wealthsimple, Questbank, Peoples Trust Company, Paramount Commerce, KOHO, DoBusiness.com, Digital Commerce Bank, and Bank of America. Payments Canada plans to onboard more participants in the coming months in a rollout that will include all major Canadian financial institutions and other members. More than nine in 10 Canadians will have access to the RTR within the first year after launch.

While Canada may be late to the real-time payments game, the launch of RTR will give banks and fintechs a foundation to build more sophisticated payment experiences, particularly for businesses seeking better cash flow visibility, faster payouts, and automated reconciliation. However, as the US has demonstrated with FedNow, launching a real-time payment rail is only the first step. The real measure of success will be how quickly financial institutions adopt the system and translate its capabilities into meaningful benefits for consumers and businesses.


Photo by Alesia Kozik

Verifone Deploys Visa’s Featurespace in its Anti-Fraud Framework

Verifone Deploys Visa’s Featurespace in its Anti-Fraud Framework
  • Verifone has teamed up with Visa’s Featurespace to bring AI-powered fraud detection to its global payments network.
  • The integration uses adaptive machine learning to analyze more than 1,800 transaction attributes in real time, helping merchants reduce fraud, chargebacks, and false declines.
  • Visa acquired Featurespace in 2024. The company demonstrated its fraud detection technology at FinovateFall 2016 in New York.

Global payments technology provider Verifone has teamed up with Visa’s Featurespace to bolster its anti-fraud network. The integration brings AI-powered, real-time fraud detection to Verifone’s payments network, helping merchants identify suspicious transactions while minimizing friction for legitimate customers.

The Featurespace platform uses adaptive machine learning models to assess transactions on Verifone’s network in real time, helping merchants and payment facilitators reduce fraud, lost sales, and chargebacks. The integration adds another layer of fraud protection to Verifone’s existing infrastructure, helping merchants identify suspicious activity while reducing the risk of declining legitimate transactions.

Verifone’s risk-scoring framework evaluates more than 1,800 transaction attributes in real time, processing payments in under 100 milliseconds. By integrating Featurespace’s Adaptive Behavioral Analytics (ABA), Verifone can establish normal transaction patterns for individual merchants, cards, and accounts, identifying anomalies such as unusually large purchases or late-night transactions. The technology considers both individual transactions and broader behavioral patterns, continuously learning over time to improve fraud detection.

“Great payment security is invisible to the customer and unmistakable to the merchant,” said Verifone Head of Global Fraud and Tooling Fabian Ganster. “Fraud is increasingly shaped by AI, so the defense has to be, too. By combining Visa’s adaptive intelligence with our payments expertise, we can stay ahead of threats that change every day and give merchants and partners payments and protection from one provider they can trust.”

Featurespace was founded in 2008 at Cambridge University’s Department of Engineering, where researchers developed AI-based tools to analyze transaction data and detect fraud. Visa completed its acquisition of Featurespace in 2024. The company showcased its technology at FinovateFall 2016 in New York.

Founded in 1981, Verifone provides payment technology to merchants, fintech companies, and financial institutions. The company processes $8 trillion in transactions annually and supports an open ecosystem of more than 2,500 integrations designed to simplify payments across in-store, online, and mobile channels.

Verifone’s integration comes at a time when the sophistication and complexity of AI-powered fraud are challenging traditional fraud detection methods. Embedding Featurespace’s technology directly into Verifone’s payment gateways allows merchants to access fraud screening without adding another vendor or integrating with another third party. For Visa, the partnership demonstrates how the company is leveraging its 2024 acquisition to expand its fraud prevention capabilities.


Photo by Mikhail Nilov

Circle Reports 17% Revenue Growth as Stablecoin Payments Network Expands

Circle Reports 17% Revenue Growth as Stablecoin Payments Network Expands
  • Stablecoin issuer Circle reported $865 million in third-quarter revenue and reserve income, up 17% year over year.
  • The revenue was driven in part by $182 million from a private presale of Circle’s ARC token.
  • Circle is expanding its payments infrastructure through its planned Tazapay acquisition, Arc blockchain launch, and institutional partnerships as it seeks to diversify revenue beyond stablecoin reserves.

Digital currency platform and stablecoin issuer Circle released its third-quarter earnings this week. The New York-based company reported that its total revenue and reserve income reached $865 million in the third quarter of this year, representing a 17% increase over last year. Additionally, the fintech reported an increase in USDC transaction activity. Here’s a breakdown of what is behind these two headline figures.

Circle reported that $658 million of the $865 million in revenue and reserve income was generated via reserves. The company reported that this figure was down 8% year over year, citing lower interest rates as the cause of the drop. Of the remaining $207 million in other revenue, $182 million was the result of a private presale of Circle’s ARC token. Interestingly, without the contribution of funds from that sale, Circle’s total revenue and reserve income would have been approximately $683 million, below the 2025 reported total. While Circle is generating revenue in ways beyond interest earned on USDC reserves, the quarter’s revenue growth was not the result of an established or recurring revenue stream.

From a banking perspective, what is particularly notable about these results is that Circle’s USDC on-chain transaction volume reached $13.9 trillion in the third quarter, marking an increase of 49% from last year, while overall average USDC in circulation totaled $73.3 billion, which is up only 8% year on year. This difference in growth suggests that USDC is seeing considerably more transaction activity without a comparable increase in the amount circulating.

All of this growth comes as Circle has been expanding its payments network through acquisitions. The company announced plans to acquire global payments infrastructure company Tazapay earlier this fall. Tazapay reaches 100+ markets and brings more than $25 billion in annualized payment volume. The deal, which is set to close in 2027, will allow Circle to move beyond stablecoin issuance and into international payment and payout infrastructure.

Circle demonstrated its interest in infrastructure last quarter, launching the public mainnet of its Arc blockchain on September 16. At launch, the fintech minted the initial supply of 10 billion ARC tokens and revealed that more than 100 institutional and ecosystem builders were already participating. This infrastructure could eventually generate revenue through network participation and token-related activity.

“In Q3, we saw continued proof that institutions are building and expanding on USDC,” said Circle Co-Founder, CEO, and Chairman Jeremy Allaire. Circle highlighted several partnerships as evidence of this growing institutional adoption:

  • Visa expanded Visa Direct stablecoin pre-funding into commercial deployment, supporting eligible cross-border payouts.
  • Samsung’s Wallet enables eligible US users to send USDC-funded transfers to bank accounts in more than 60 countries.
  • Volante Technologies is collaborating with Circle to integrate stablecoin payments and settlement into banks’ existing operations.
  • Binance announced a $100 million equity investment in Circle and expanded its USDC partnership.
  • Tereina partnered with Circle to integrate USDC and EURC into enterprise payment workflows.

Taken together, these collaborations highlight that stablecoins are increasingly being integrated into existing payment systems, enterprise software, and banking infrastructure instead of being seen as separate crypto experiences.

Circle’s third-quarter results are evidence of the growing role of stablecoins in financial services. It is clear that USDC transaction activity is increasing, and given Circle’s reliance on reserve income and one-time token sales, it may need to develop more diversified, recurring revenue streams. The recent investments in payments infrastructure, acquisitions, and institutional partnerships may help Circle capture more value from transactions, rather than primarily from interest earned on the reserves backing USDC.


Photo by Landiva Weber

OnePay Taps Stripe to Power Stablecoin Deposits

OnePay Taps Stripe to Power Stablecoin Deposits
  • Digital bank OnePay is allowing select US customers to fund their checking accounts using USDC stablecoins across 12 blockchains, automatically converting deposits into US dollars.
  • Stripe-owned Bridge powers the stablecoin deposit functionality, offering an alternative to traditional account funding methods such as ACH transfers.
  • The launch follows OnePay’s recent agentic banking and MCP integration announcements as the Walmart-backed fintech continues to expand its digital financial services offerings.

Digital bank OnePay announced this month that it is allowing select US customers to fund their OnePay checking accounts using stablecoins and receive the value as US dollars, all without requiring a separate crypto account or wallet.

Users can fund their accounts by sending stablecoins from an external wallet to a deposit address, and OnePay converts the funds to US dollars and credits the funds to their checking account within moments, depending on the network used and required checks. The feature is launching with support for USDC across 12 blockchains, including Tempo, Base, Solana, and Ethereum. OnePay notes that it will not charge conversion fees at launch, and while it does not charge a service fee, blockchain networks may impose network fees on consumers.

Supporting the behind-the-scenes fund transfer is Stripe-owned Bridge, a stablecoin orchestration platform that creates and secures deposit addresses, monitors incoming blockchain transactions, and facilitates the conversion of stablecoins into US dollars. The integration allows OnePay to offer stablecoin deposits without requiring customers to manage a separate crypto account within the app. In this sense, Bridge provides an alternative to traditional bank account funding methods such as ACH transfers, enabling customers to move funds over blockchain networks while receiving the value in dollars in their checking accounts.

OnePay anticipates that the new stablecoin capability will support the growing number of freelancers, gig workers, and overseas employees who receive payment in stablecoins. OnePay’s new launch removes complexity for these users by enabling them to deposit crypto and receive dollars out that they can use to pay bills, send money, and save.

For OnePay, the move integrates blockchain-based payment rails into everyday banking. While stablecoins are not replacing traditional payment systems such as ACH, they are emerging as an alternative for moving money, particularly across borders. By converting stablecoins directly into spendable dollars, OnePay is leveraging blockchain infrastructure without requiring consumers to interact with cryptocurrency within OnePay. The launch is also an example of a new approach to account funding in which stablecoins serve as an underlying payment mechanism rather than a standalone financial product.

The release of this feature follows OnePay’s agentic banking announcement last month. The New York-based company will offer eligible customers the option to give their AI agent access to spend and manage funds, as well as buy and sell crypto. Also last month, OnePay added an MCP connection to allow users to connect their OnePay accounts to their AI tool.

Founded in 2019, Walmart-backed OnePay offers a range of financial services, including checking and savings accounts, debit and credit cards, buy now, pay later (BNPL) financing, and credit-building tools. The company has also expanded into investing and cryptocurrency trading, allowing customers to buy and sell stocks and digital assets through its app. OnePay partners with financial institutions and technology providers to deliver its services, including Coastal Community Bank, Lead Bank, Synchrony Bank, Klarna, and DriveWealth.

Settle Secures Up To $100 Million as Stablecoin Liquidity Enters SMB Lending

Settle Secures Up To $100 Million as Stablecoin Liquidity Enters SMB Lending
  • Inventory financing fintech Settle has secured up to $100 million in a forward-flow financing agreement with crypto-native structured credit platform 3Jane, beginning with $50 million in financing capacity.
  • The agreement will allow Settle to sell eligible loans to 3Jane on an ongoing basis, freeing up capital to originate additional loans and expand its lending operations.
  • The deal leverages stablecoin liquidity to finance real-world lending and follows Settle’s recent $240 million credit facility aimed at expanding its financing offerings.

Inventory financing fintech Settle has secured up to $100 million in a forward-flow agreement today. In a deal with 3Jane, the agreement provides $50 million initially with the option to expand to $100 million.

Today’s agreement follows Settle’s announcement last month that it secured a $240 million credit facility from an international financial institution and a New York-based asset manager. That facility aimed to help Settle serve larger businesses and expand its financing offerings. The company also previously secured a $280 million revolving credit facility in 2022 and a $145 million credit facility in 2023.

3Jane is a crypto-native structured credit platform that provides capital to fintech lenders through a revolving conduit powered by blockchain technology. As part of the agreement, 3Jane has already purchased $18 million of Settle’s existing loans and has committed to purchasing eligible new loans on an ongoing basis.

The forward-flow arrangement will allow Settle to recycle capital into new loan originations rather than holding existing loans on its balance sheet until maturity, enabling the company to scale its lending operations.

The deal highlights a growing connection between traditional lending and blockchain-based finance. Tapping stablecoin liquidity to fund loans to consumer brands allows 3Jane to connect digital asset capital with real-world credit demand. Additionally, the deal gives Settle an alternative source of financing as it expands its lending operations.

Founded in 2019, Settle has provided more than $4 billion in funding to thousands of consumer brands and ecommerce businesses. Its financing solutions help businesses pay for inventory purchases and supplier invoices upfront, with repayment through extended payment terms or scheduled installments. In addition to lending, Settle offers a suite of cash flow management tools, including bill pay, accounts payable automation, and invoice tracking.

Settle CEO and Founder Alek Koenig emphasized the importance of helping consumer brands finance inventory purchases before generating revenue from sales. “The forward flow with 3Jane gives us a more capital-efficient way to finance that gap at scale,” Koenig said. 3Jane CEO Jacob Chudnovsky highlighted the role of stablecoin liquidity in supporting Settle’s lending operations, noting that the financing structure is designed to lower Settle’s borrowing costs. “Settle has built a lending business serving thousands of consumer brands,” Chudnovsky said.


Photo by Pavel Danilyuk


LTVCo Agrees to Acquire Issuer-Merchant Network Kipp

LTVCo Agrees to Acquire Issuer-Merchant Network Kipp
  • Issuer-merchant network Kipp has been acquired by an investor group led by The Lifetime Value Company (LTVCo) and its founders. Terms were not disclosed.
  • The acquisition will support Kipp’s US expansion, technology investments, and efforts to grow its network of issuer and merchant partners.
  • Kipp will continue to operate independently under its existing leadership, helping merchants recover declined transactions while giving issuers control over risk and pricing.

Issuer-merchant network Kipp has been acquired by an investor group led by The Lifetime Value Company (LTVCo) and its founders. Terms of the deal were undisclosed.

Kipp anticipates that the acquisition will offer it long-term financial backing and has made it clear that the new owners will help it pursue continued growth by providing the resources to expand its US presence, invest in its technology, and further build its partnerships with issuers and merchants.

Founded in 2021, Kipp creates a bridge between merchants and issuers by allowing merchants to pay for transactions that would otherwise be declined due to insufficient funds. It also gives issuers full control over which transactions they approve and the premium price they require to take on the additional risk. Using Kipp, up to half of transactions that otherwise would have been declined can be approved without imposing additional friction or cost to the end consumer.

“Our focus now is expanding our US issuer and merchant network and bringing more transactions onto the platform,” said Kipp CEO and Co-founder Chanan Lavi. “This acquisition gives us the long-term backing and operational resources to accelerate that work while preserving what makes Kipp valuable: issuers control their risk, merchants recover sales, and consumers pay no additional fee.”

LTVCo is a technology and information services platform that holds a portfolio of consumer brands, including BeenVerified, Bumper, and Ownerly. Adding Kipp to its lineup will expand LTVCo’s reach into the payments industry, giving the company a foothold in the issuer-merchant ecosystem while supporting Kipp’s efforts to scale its technology and partnerships in the US.

“Every unnecessary decline costs a merchant a sale and an issuer a chance to remain the customer’s preferred card,” said LTVCo CEO and Co-founder Josh Levy. “We’ve seen that firsthand. Kipp aligns both sides to recover that revenue and deliver a better customer experience. We’re committed to building Kipp for the long term, with the financial strength and resources to invest in its technology, expand its network, and support its partners at scale.”

Kipp will continue to operate independently under the leadership of its co-founders, CEO Chanan Lavi and CTO Nir Levy.


Photo by Ann H

Casap Raises $56 Million as AI Agents Take on Fraud and Payment Disputes

Casap Raises $56 Million as AI Agents Take on Fraud and Payment Disputes
  • Casap raised $56 million in Series B funding, bringing its total funding to $90 million, to expand its agentic AI platform for financial services operations.
  • Casap’s AI agents are delivering measurable results, helping more than 100 financial institutions reduce fraud losses, accelerate dispute resolution, and automate complex workflows while maintaining human oversight.
  • The funding reflects growing investor confidence in agentic AI as financial institutions move beyond basic task automation toward AI systems capable of executing complex, highly regulated workflows.

AI agent platform for financial services Casap raised $56 million this week to help combat fraud and payment disputes. The Series B funding round was led by Base10 Partners, with strategic participation from Experian and Synchrony and additional support from existing investors including Emergence Capital and Lightspeed Venture Partners.

Today’s round, which comes just over a year after Casap raised $25 million in its Series A round, brings the California-based company’s total funding to $90 million. Casap will use the funding to advance its AI platform that combines AI agents, industry expertise, and forward-deployed teams to transform operations such as disputes and fraud to collections, claims, and more.

Casap was founded in 2023 by former Robinhood executive Shanthi Shanmugam and former Chime executive Saisi Peters to streamline complex financial services operations. The company’s platform uses specialized AI agents to investigate cases, make decisions, and take action across financial institutions’ existing systems. The agents follow institution-specific policies and procedures, maintain auditable records of their decisions, and escalate cases requiring human judgment. Since launching with a focus on fraud and payment disputes, Casap has expanded into other operational areas, including collections, claims, and complex exceptions. The company has also grown its revenue tenfold over the past year, more than double its original target. Casap took home Best of Show honors for its demo at FinovateFall 2025.

“We started with disputes because it was one of the hardest problems in financial services,” said Casap CEO and Co-founder Shanthi Shanmugam. “But our ambition was always bigger than disputes. We wanted to prove that AI could do more than make work more efficient. It could fundamentally change the outcomes for financial institutions. Today we’re cutting fraud losses in half while resolving disputes in days instead of months. Now our customers are asking us to bring that same transformation to the rest of their operations.”

Casap works with more than 100 financial institutions and has helped them:

  • Reduce first-party fraud losses up to 51%
  • Achieve a 96% chargeback win rate (compared with a 60% industry average)
  • Reduce resolution time from as long as 90 days down to 8 days
  • Resolve 73% of dispute cases through agentic automation while retaining human oversight
  • Reduce human processing time from 45 minutes to 1 to 2 minutes

“We’ve been told for years that financial institutions will have to make a tradeoff between operational economics and experience quality,” said Base10 Partners Managing Partner Adeyemi Ajao. “Casap has shown that agentic AI technology can change that tradeoff. The same technology lowers the cost of complex work, while improving speed, quality, and consistency. Disputes proved that model in one of the hardest environments in financial services, and we believe the opportunity now is much larger.”

Casap’s latest funding round reflects growing investor confidence in agentic AI’s ability to move beyond simple task automation and deliver measurable operational outcomes in financial services. Fraud and disputes are particularly compelling use cases because they involve complex workflows, regulatory requirements, and significant manual intervention. Casap’s broader adoption across banking operations is promising because its AI agents can handle routine processes while maintaining human oversight. The company’s expansion into collections, claims, and other functions also signals a larger shift in how financial institutions may approach automation, moving from tools that assist employees to systems that can execute entire workflows.

Hyphenate Raises $45 Million for Autonomous Finance

Hyphenate Raises $45 Million for Autonomous Finance
  • Autonomous finance platform Hyphenate raised $45 million in Series A funding, bringing its total funding to $54 million.
  • Hyphenate uses AI agents to automate financial operations, including cash reconciliation, invoicing, and subledger management, helping businesses reduce repetitive work and audit exceptions.
  • The funding reflects growing investor interest in agentic AI that executes financial workflows, potentially shifting finance teams toward strategic oversight and creating new opportunities for banks and fintechs.

Autonomous finance platform Hyphenate (formerly known as Maximor) announced a $45 million Series A round. The investment was led by Nexus Venture Partners, with participation from B Capital and existing investors including Foundation Capital, BoldCap, and Gaia Ventures. 

Today’s funding brings Hyphenate’s total funding to $54 million since it was founded in January of last year. The company will use the capital to scale faster and take its agents deeper across the finance function and into strategic finance.

“What makes Hyphenate compelling is that autonomy is already showing up in customer operations,” said Abhishek Sharma, Managing Director at Nexus Venture Partners. “Finance has an unusually high bar for accuracy, controls, and auditability. Hyphenate has built around that bar from the beginning, and the expansion we are seeing inside customers shows what becomes possible once the system earns the right to take on more work.”

Hyphenate’s platform leverages AI agents to automate finance workflows in which agents reconcile cash, process sales orders, run invoicing, and maintain subledgers. While the agent moves the close forward, human finance teams intervene in cases in which judgment changes the outcome. Hyphenate aims to help its clients’ finance operations run independently and continuously to enable teams to spend their time on the decisions that actually move the business.

The company’s agents process financial workflows spanning hundreds of entities, thousands of bank accounts, and millions of transactions every day. Its customers report 90% less repetitive finance work and 75% fewer audit exceptions.

“Every finance team carries a long list of work it does because somebody has to,” said Ramnandan Krishnamurthy, co-founder and CEO of Hyphenate. “Our customers are watching that list shrink in production. Once a team sees the system handle one workflow to an auditor’s standard, they hand it the next one. That is the pattern this company is built around, and this round lets us run it across the whole function.”

Hyphenate’s autonomous finance platform is well-positioned to attract investor interest. AI platforms that move beyond generating insights to actually take action are particularly valuable, especially when used for repetitive, rules-based tasks like reconciliation, reporting, and accounting.

As platforms like Hyphenate take on more operational responsibilities, we may start to see the role of corporate finance teams shift from executing routine processes to overseeing exceptions, managing controls, and making strategic decisions. If this evolution takes place, banks could integrate banking activities, payments, and financial data directly into AI-driven workflows to position themselves and their infrastructure as an essential component of autonomous finance.

Banks Structure $63 Billion Anthropic AI Financing, Deepening Exposure to AI Infrastructure

Banks Structure $63 Billion Anthropic AI Financing, Deepening Exposure to AI Infrastructure
  • Bank of America, Citigroup, Morgan Stanley, and Blackstone have committed $63 billion to finance Broadcom AI computing equipment that will be leased to Anthropic.
  • The arrangement highlights the growing role of banks and private credit investors in financing AI infrastructure, as demand for computing capacity continues to accelerate.
  • The deal presents new opportunities for financial institutions while raising concerns about equipment depreciation, uncertain future demand, and broader financial stability risks.

Four major financial institutions have agreed to a $63 billion financing arrangement that will fund the purchase of AI computing infrastructure for Anthropic. Under the agreement Bank of America, Citigroup, Morgan Stanley, and Blackstone will contribute to a newly formed a special-purpose vehicle (SPV) that will purchase Broadcom AI accelerators and networking equipment and lease them to Anthropic. The transaction is part of an existing Broadcom–Anthropic compute agreement.

The three banks will arrange the primary financing, while Blackstone will provide additional financing and Broadcom will help protect lenders against potential losses in the value of the underlying assets. The $63 billion represents committed financing and does not represent the value of equipment deliveries, which are expected to be completed in 2027.

The scale of the SPV is impressive. At $63 billion, the financing commitment is larger than many major corporate acquisitions. While equipment leasing and asset-backed financing are nothing new, the size of this arrangement demonstrates how AI infrastructure investment is creating demand for financing on a scale that few individual lenders could accommodate. The deal also illustrates how banks and private credit investors are eager to participate in building out AI infrastructure.

Historically, Anthropic has mostly relied on equity funding and strategic investments from technology companies to finance its AI development and infrastructure expansion. Amazon has invested billions in the company, while Anthropic raised $30 billion in a Series G round in February 2026 and another $65 billion in Series H funding in May.

Just as with today’s financing arrangement, both of the previous venture capital rounds were intended to support the company’s growing computing infrastructure needs. Today’s arrangement represents a different financing approach, bringing banks and private credit investors into the picture to finance the physical equipment supporting Anthropic’s AI operations.

For financial institutions, the deal highlights the growing opportunity to finance AI infrastructure. “The rapidly growing demand for AI is creating an enormous opportunity to finance compute capacity at scale,” said Blackstone President and COO Jon Gray.

Broadcom President and CEO Hock Tan echoed that optimism, pointing to the growing demand for AI computing power. “Fundamentally, the need for AI compute continues to grow at an extraordinary pace. This validates that there is capital available to finance such growth and that Broadcom is uniquely positioned to enable it.”

The financing arrangement follows Bank of Japan’s October financial stability report, which examined how AI infrastructure investment and nonbank financing could transmit risks through the financial system. While the growing demand for computing power presents new lending opportunities for banks, it also introduces risks tied to rapidly depreciating technology, uncertain future demand, and the potential for a slowdown in AI investment. Financial institutions are right to be wary of committing more capital to AI infrastructure, as they will need to balance the opportunity for growth against the possibility that the underlying assets may lose value faster than anticipated.


Photo by Jan van der Wolf

Tech Mahindra Acquires Finastra’s Cash Management Product Suite

Tech Mahindra Acquires Finastra’s Cash Management Product Suite
  • Tech Mahindra has acquired Finastra’s Cash Management product suite, including its cash management, virtual accounts, and liquidity management solutions.
  • Tech Mahindra plans to continue supporting existing customers while investing in the products to expand its banking technology portfolio.
  • The deal strengthens Tech Mahindra’s position as a banking software provider while allowing Finastra to streamline its portfolio and focus on its core businesses.

India-based consulting services company Tech Mahindra announced it has acquired the Cash Management product suite of financial services software company Finastra.

Under the agreement, Finastra is offloading Fusion Cash Management (FCM), Fusion Virtual Accounts (FVA), and Fusion Liquidity Management (FLM). Specifically, Tech Mahindra has acquired the intellectual property associated with the FCM, FVA and FLM products along with IP and capabilities across CashPlus, Global CashPlus, APIs, payables, receivables, balance and transaction reporting, liquidity management, cash-flow forecasting, and virtual accounts. Tech Mahindra anticipates that adding these capabilities will help grow its Banking, Financial Services and Insurance (BFSI) solutions portfolio.

Additionally, Tech Mahindra made it clear that the products aren’t going anywhere. The company will provide continued investment, innovation, and support for the cash management tools, and will continue providing Finastra’s existing customers with access to and support for the products.

Overall, Tech Mahindra anticipates that the acquisition will put it in a better position to help banks meet evolving demands for cash, liquidity, and transaction banking capabilities. “The acquisition of Finastra’s Cash Management product suite strengthens our banking products portfolio and expands our ability to support financial institutions across critical cash and liquidity management needs,” said Tech Mahindra SVP, Banking Group and Chief Product Officer, Financial Services Anil Venuturupalli. “Through this acquisition, we are creating a strong foundation for continued innovation. Our focus is on evolving these capabilities to help banks address the growing demand for intelligent, connected and efficient cash management solutions.”

Founded in 2017 through the merger of Misys and D+H, Finastra serves 7,000 customers, including 80% of the top 50 global banks, with software spanning lending, payments, and retail banking. The company, which appointed Chris Walters as CEO last year, has been streamlining its portfolio. Today’s deal follows its sale of its Treasury and Capital Markets division to an affiliate of private equity firm Apax Partners approximately 18 months ago.

“This is a good next step for these products, and, most importantly, for the customers who rely on them,” said Finastra Head of Partnerships and Cross Selling Sales Ruchir Purwar. “Tech Mahindra brings deep banking and technology expertise and already knows our business well. We’re confident they are well positioned to take these solutions forward and continue supporting customers as their needs evolve.”

Tech Mahindra is a subsidiary of the Mahindra Group, a multinational conglomerate founded in 1945. With more than 150,000 employees across 90 countries, Tech Mahindra provides IT consulting and digital transformation services spanning AI, cloud infrastructure, analytics, engineering, and business process solutions.

For Tech Mahindra, today’s acquisition will allow it to move beyond consulting and implementation services to own more of the technology banks rely on for their day-to-day operations. Meanwhile, the deal will allow Finastra to streamline its portfolio, allowing it to focus on its remaining core banking, lending, and payments businesses.


Photo by Tima Miroshnichenko