This site is operated by a business or businesses owned by Informa PLC and all copyright resides with them. Informa PLC's registered office is 5 Howick Place, London SW1P 1WG. Registered in England and Wales. Number 8860726.
Finovate Blog
Tracking fintech, banking & financial services innovations since 1994
Verifone has teamed up with Visa’s Featurespace to bring AI-powered fraud detection to its global payments network.
The integration uses adaptive machine learning to analyze more than 1,800 transaction attributes in real time, helping merchants reduce fraud, chargebacks, and false declines.
Visa acquired Featurespace in 2024. The company demonstrated its fraud detection technology at FinovateFall 2016 in New York.
Global payments technology provider Verifone has teamed up with Visa’sFeaturespace to bolster its anti-fraud network. The integration brings AI-powered, real-time fraud detection to Verifone’s payments network, helping merchants identify suspicious transactions while minimizing friction for legitimate customers.
The Featurespace platform uses adaptive machine learning models to assess transactions on Verifone’s network in real time, helping merchants and payment facilitators reduce fraud, lost sales, and chargebacks. The integration adds another layer of fraud protection to Verifone’s existing infrastructure, helping merchants identify suspicious activity while reducing the risk of declining legitimate transactions.
Verifone’s risk-scoring framework evaluates more than 1,800 transaction attributes in real time, processing payments in under 100 milliseconds. By integrating Featurespace’s Adaptive Behavioral Analytics (ABA), Verifone can establish normal transaction patterns for individual merchants, cards, and accounts, identifying anomalies such as unusually large purchases or late-night transactions. The technology considers both individual transactions and broader behavioral patterns, continuously learning over time to improve fraud detection.
“Great payment security is invisible to the customer and unmistakable to the merchant,” said Verifone Head of Global Fraud and Tooling Fabian Ganster. “Fraud is increasingly shaped by AI, so the defense has to be, too. By combining Visa’s adaptive intelligence with our payments expertise, we can stay ahead of threats that change every day and give merchants and partners payments and protection from one provider they can trust.”
Featurespace was founded in 2008 at Cambridge University’s Department of Engineering, where researchers developed AI-based tools to analyze transaction data and detect fraud. Visa completed its acquisition of Featurespace in 2024. The company showcased its technology at FinovateFall 2016 in New York.
Founded in 1981, Verifone provides payment technology to merchants, fintech companies, and financial institutions. The company processes $8 trillion in transactions annually and supports an open ecosystem of more than 2,500 integrations designed to simplify payments across in-store, online, and mobile channels.
Verifone’s integration comes at a time when the sophistication and complexity of AI-powered fraud are challenging traditional fraud detection methods. Embedding Featurespace’s technology directly into Verifone’s payment gateways allows merchants to access fraud screening without adding another vendor or integrating with another third party. For Visa, the partnership demonstrates how the company is leveraging its 2024 acquisition to expand its fraud prevention capabilities.
This week’s edition of Finovate Global showcases recent fintech headlines from Hong Kong.
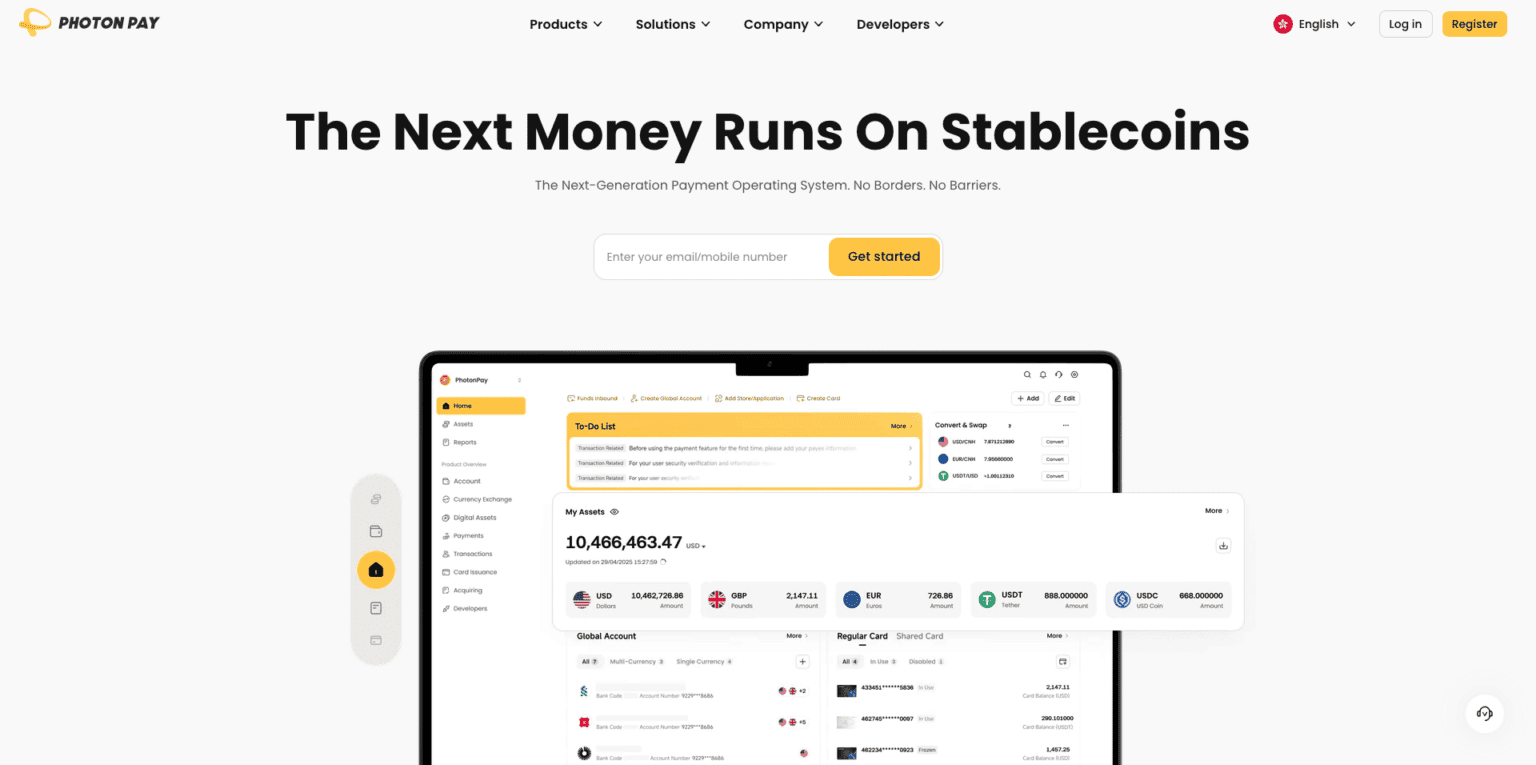
PhotonPay raises $40 million for its stablecoin-based financial operating system
Hong Kong-based fintech PhotonPay has secured $40 million in Series C funding this week. The round was led by Blockchain Capital. New investor SBI Group also participated, and existing investors IDG Capital, GL Ventures, and Lightspeed Faction provided follow-on investments. Blacksheep Technology served as the exclusive financial advisor to PhotonPay on the transaction.
The investment will support the expansion of PhotonPay’s stablecoin-centric Financial Operating System (Financial OS). The capital will enable the company to focus on enhancing its multi-asset wallet capabilities, expanding global card issuing, bolstering local clearing infrastructure in key markets, and creating an agent-ready financial execution layer.
“Moving money across borders in seconds means little if it still takes days to put that capital to work,” PhotonPay CEO and Founder Lewison Chen said. “Stablecoins are accelerating global money movement, while local clearing and global card issuing connect that liquidity to local settlement and everyday business spending. Our Financial OS brings these capabilities together, making the underlying infrastructure far less visible to businesses, even as it becomes more essential than ever.”
PhotonPay’s Financial OS combines multi-asset wallets, global money movement, foreign exchange, local clearing, and global card issuing through an integrated API-first architecture. This enables businesses to access the financial capabilities required to manage and deploy funds across markets. Stablecoins are also central to this architecture. Its multi-asset wallet connects stablecoin liquidity with fiat balances and integrates asset conversion, foreign exchange, and local clearing into a single workflow. In support of this dual-rail infrastructure, PhotonPay manages a global financial network that enables businesses to open local collection accounts in 17 markets and receive funds in more than 60 currencies.
“Connecting financial networks is only the beginning,” Chen added. “The real breakthrough is abstracting that complexity behind a unified, programmable financial layer, so businesses and AI agents can move from intent to execution within clearly defined boundaries.”
With 34 payment and financial licenses and regulatory authorizations across the Americas, Europe, and Asia, PhotonPay serves more than 200,000 businesses across 200+ countries and territories. As of August 2026, the company reported annualized transaction volume of $65 billion.
TCM Solutions partners with Tribe Payments
TCM Solutions (TCMS), a Hong Kong-based merchant acquirer, has announced a partnership with issuer and acquirer processor Tribe Payments. Through the partnership, TCMS will use Tribe’s cloud-native, API-led processing platform to launch more bespoke solutions for clients, serve a broader range of merchants, and expand into Singapore and other markets in the region.
“Our decision to partner with Tribe Payments reflects our ambition to build a scalable, future-ready acquiring business across Asia,” TCMS CEO John Lee said. “Our specialist focus on duty-free, cross-border payments and POS solutions requires a processing partner that combines robust technology with the flexibility to support our growth.”
TCMS serves merchants in several core verticals, including food and beverage groups, medical chain stores, airlines and airport duty-free retailers. Its payment systems are designed to accommodate individual outlet operations and their specific accounting requirements. TCMS’ expertise includes POS technology and Dynamic Currency Conversion (DCC), which enables eligible international customers to view and pay for transactions in their preferred currency at the point of sale.
“We are delighted to partner with TCMS as it continues to develop its acquiring business across Asia,” Tribe Payments GM Asia-Pacific Matt Weir said. “TCMS brings valuable expertise in duty-free and cross-border payments, supported by specialist POS and DCC capabilities. Our cloud-native platform is designed to provide the processing foundation, flexibility, and scalability needed to support TCMS’ ambitions, and to help deliver innovative payment solutions to merchants and their customers.”
London-based Tribe Payments offers banks, fintechs, and payment businesses a single, unified, cloud-native platform for issuer and acquirer processing, along with digital banking and account-based payment services. The company provides issuer and acquirer processing connected to Visa, Mastercard, American Express, UnionPay, JCB, and Discover. Tribe Payments also links its clients with banking partners through its Bank Connect solution, providing access to local payment rails in multiple markets and enabling businesses to generate customer IBANs or account numbers through a single API integration. Founded in 2018, Tribe Payments’ modular platform also supports digital banking, 3-D Secure, tokenization, and risk and fraud monitoring.
Hong Kong Fintech week focuses on transformation, fuel, and expansion
Hong Kong Fintech Week begins on Monday. This year, the theme of the event is “Fintech Nexus: Bridging the World, Building the Future”. That theme will be explored via three “core growth engines”: AI+, Finance+, and global expansion. The event will begin with opening remarks from John KC Lee, Chief Executive of the Hong Kong Special Administrative Region, and will feature forums on a range of topics, including AI and DeepTech, InsurTech and HealthTech, Digital Assets and Web3, among others.
The conference, which will run along with the StartmeupHK Festival 2026, anticipates hosting more than 45,000 participants from 120+ economies. More than 1,000 speakers, 800 exhibitors and startups, and more than 30 delegations are expected to attend.
Of particular interest are the three core growth engines that conference organizers have identified as central to Hong Kong’s fintech and financial services goals.
AI+ The conference agenda will examine how companies are moving beyond chatsbots to experiment with agentic aI, autonomous banking, robotics, and the economics of running large language models in regulated industries such as finance.
Finance+: The agenda will also explore how deep capital markets can be leveraged to commercialize cutting-edge innovations in areas like tokenization of real-world assets and stablecoins.
Global Expansion: The conference agenda will examine how technology firms based in mainland China to navigate international expansion and issues related to AI sovereignty. It will also help them bridge regional gaps via frameworks such as the Greater Bay Area (GBA) integration.
“As HKFW x SMUHK enters its second decade, Hong Kong begins a new chapter with its First Five-Year Plan, unveiled alongside the 2026 Policy Address,” InvestHK Director-General of Investment Promotion Alpha Lau said. “This year’s three engines—Finance+, AI+, and global expansion—reflect the city’s strategic priorities: driving innovation and economic development, transforming industries, and enabling multi-market growth. Hong Kong connects these forces, and this year’s event will bring together global innovators, investors, and enterprises to scale internationally and seize new opportunities through our city.”
Here is our look at fintech innovation around the world.
Apple Pay and Google Pay have arrived in Uzbekistan.
Pine Labs and Webxpay teamed up to bring India’s UPI to Sri Lanka.
Latin America and the Caribbean
ACI Worldwide and Circle Internet Group forged a partnership to support the integration of stablecoin settlement into existing bank infrastructure in Latin America.
Cloud-native banking infrastructure and embedded finance firm Mbanq secured an infrastructure deal with 40+ Haitian credit unions.
Mexican fintech Kapital secured approval to begin banking operations in Colombia.
Asia-Pacific
Visa and Tencent signed a Memorandum of Understanding (MoU) on agentic commerce and cross-border payments.
The central banks of Thailand and Malaysia announced their support for Singapore’s cross-border digital money initiative BLOOM, which stands for Borderless, Liquid, Open, Online, Multi-currency).
Visa has teamed up with crypto payments network Mesh to enable customers to spend their crypto and stablecoin balances as they would fiat currency. The two are combining Visa’s global acceptance network with Mesh’s orchestration infrastructure to allow consumers to pay in-store and online from the crypto and stablecoin balances in their wallet apps.
Mesh was founded in 2020 to enable easy payment across hundreds of exchanges, wallets, and providers. Today, the fintech has more than 200 enterprises using its network. According to Crypto.com, there are 774 million crypto owners across the globe, but they spend hardly any of the crypto they hold because of the friction involved to convert it to fiat currency. That’s because customers have traditionally had to cash out their crypto to a bank account and wait or sign up for a payment card tied to a single platform. Among Mesh’s customers are Kalshi, Tools for Humanity, Félix Pago, Majority, and KAST.
“Crypto never had a spending problem—it has a last-mile problem, and until now, closing it meant getting a separate card,” said Mesh CEO and Co-founder Bam Azizi. “Mesh handles the funding and conversion, so a balance becomes purchasing power at the moment of payment, with nothing for the user to move and nothing for the merchant to change. We think your money should be spendable right where it already lives. With Visa and Mesh, it is.”
Visa’s payment network exceeds 175 million merchant locations across more than 200 countries and territories, creating a large footprint where consumers can spend funds that were previously difficult to spend. In 2025, the payment network processed $14.2 trillion in payments volume. The company most recently demoed at FinovateFall 2025 in New York.
“Consumers increasingly expect to use their money however and wherever they choose,” said Visa Global Head of Growth Rubail Birwadker. “Working with Mesh helps expand how digital asset balances can connect to the trusted payment experiences consumers and merchants rely on every day.”
Customers can use funds held across eligible digital wallets and platforms that enable them to pay from their balance for in-person and online purchases wherever Visa is accepted. Meanwhile, Visa provisions a credential in the background that will allow the shopper to make a purchase without having to sell, transfer, or preload funds. Merchants receive a payment in the standard way, without having to install new hardware or make changes to their checkout flow.
Mesh and Visa will announce availability, supported devices, and participating platforms as rollout details are finalized.
In the future, Mesh plans to extend beyond crypto and stablecoins to help consumers spend funds from “wherever consumers hold value.” This could eventually include other forms of digital assets and stored value, further reducing the barriers between where consumers hold their money and where they can spend it.
Agentic shopping is taking over the headlines, but are consumers really ready to hand over their credit cards to a bot? Visa recently sponsored a report that measures consumers’ attitudes toward agentic commerce.
The research was conducted by The Harris Poll in May of 2026 and surveyed 2,065 US adults to provide insight into how consumers are navigating the next evolution of AI shopping and payments. The report found that 72% of respondents have used an AI assistant, 23% trust generative AI to handle payments on their behalf, and 61% would trust Visa to handle agentic transactions.
The findings from The Harris Poll’s research reveal four key takeaways for the future of agentic commerce:
Payment providers could retain influence even if AI owns the customer interface
Visa’s research suggests that consumers distinguish between the technology that helps them shop and the payment providers they trust to facilitate transactions. So while they may use an AI agent to recommend a new pair of shoes, compare prices, and select a retailer, when it comes time to pay, many still prefer the protections and peace of mind offered when using a familiar, established payment provider.
The implication: Banks and payment networks may not need to own the entire AI shopping experience to remain relevant. Their competitive advantage could depend on providing trusted payment infrastructure that sits behind the shopping experience.
Trust could become a competitive advantage for incumbent banks
As it is still a new concept, much of the conversation around agentic commerce has focused on the enabling technology, such as APIs, tokenization, agent authentication, and payment execution. And for good reason: figuring out the logistics of the payment that leverages a constantly evolving field of technology with multiple players is complicated.
However, Visa’s research suggests that consumer confidence could be just as important as technical capability. This element of consumer trust and confidence creates a lot of opportunity for established financial institutions that may feel locked out of participating in agentic commerce.
The implication: Fortunately for banks and payment providers, they already have relationships with consumers, established fraud protections, and experience in handling disputes. Each of these elements is a differentiator as AI agents begin initiating transactions.
Agentic commerce could reinforce existing payment infrastructure
Stablecoins have been taking over discussions in banking and fintech, as their low-cost, speedy rails have the potential to improve the overall customer experience while driving down costs. Additionally, their programmable, blockchain-based infrastructure could make stablecoins an attractive payment option for certain agentic commerce use cases. However, as Visa’s study implies, if consumers prioritize familiar, trusted payment brands, card networks may have an advantage in the early stages of adoption.
The implication: This prioritization shows that lower transaction costs and technical efficiency may not be big enough reasons for consumers to adopt unfamiliar payment experiences. For fintechs building alternative payment solutions, trust and consumer protections may be just as important as price and convenience.
The opportunity in autonomous transactions is in making transactions feel safe
Agentic commerce is still in its early stages, and we still have a lot to learn when it comes to best practices. However, the findings in Visa’s study imply that successful agentic payments will require clear permissions, spending limits, authentication, and dispute resolution.
The implication: If shoppers do not feel safe in allowing agentic AI to make payments on their behalf, they will continue to shop via traditional ecommerce methods. However, Visa is already developing infrastructure through its Visa Intelligent Commerce initiative that will offer authentication, transaction security, and consumer controls. Consumers may be more willing to embrace agentic commerce when trusted financial services providers establish the necessary safeguards, rather than leaving the experience to a fragmented group of unfamiliar players.
There are still a few weeks left of summer, but the final day of August often serves as the unofficial end of summer for many—with kids returning to school and Labor Day around the corner.
As the week begins, Finovate’s Fintech Rundown is highlighting a handful of fintech funding announcements in payments, wealth management, and capital markets, as well as interesting partnership news in DeFi and identity verification involving fintechs from Singapore and South Korea.
Visainks a strategic partnership with South Korean fintech Dunamu to develop stablecoin payments, international remittance services, and AI-powered e-commerce solutions.
Credit unions
Baton Rouge Telco Federal Credit Union launches AI-powered smart financial calculators courtesy of its partnership with Appli.
Lending
RateZiplaunches live US bank rate and mortgage rate app in ChatGPT.
Digital payments and data security company Bluefinannounced it has partnered with Visa on a new card-present acceptance tool. The new offering combines Bluefin’s PCI-validated point-to-point encryption (P2PE) solution with Visa Acceptance Solutions to bring increased security to in-person payment acceptance.
The in-store payment acceptance tool offers merchants, software providers, and enterprises a unified approach to accepting payments by combining payment acceptance, PCI-validated security, tokenization, device lifecycle management, and enterprise payment infrastructure into a single solution. Bluefin will power the P2PE piece, while Visa’s Visa Acceptance Solutions is taking on the payment processing, tokenization, and global payment services elements.
“Enterprise organizations are no longer looking for individual payment technologies—they’re looking for infrastructure that enables secure commerce across every channel,” said Bluefin Founder and Chief Strategy Officer Ruston Miles. “Our collaboration with Visa Acceptance Solutions reflects a shared vision that secure payment acceptance should be delivered as an integrated platform rather than a collection of independent components.”
Bluefin was founded in 2007 to bring security to payments by developing technology to devalue sensitive data at the point of entry. Since then, the company has expanded to focus on broader data security infrastructure that protects sensitive data in motion across systems, platforms, and environments. Combining P2PE, vaultless tokenization, and orchestration powers Bluefin’s new model for securing transactions.
The new tool will bring Bluefin clients simplified deployment, centralized device management, developer APIs and SDKs, and reduced PCI compliance scope. While Bluefin is launching the payment acceptance tool with select Ingenico Lane series devices, the tool is capable of expanding to additional ecosystems.
“By combining Visa Acceptance Solutions with Bluefin’s card-present security infrastructure, we’re helping organizations simplify deployment, reduce complexity, and build a stronger foundation for the future of enterprise commerce,” added Miles.
Teaming up with Visa helps Bluefin consolidate traditional, fragmented technology stacks. Rather than separately integrating payment acceptance, processing, encryption, tokenization, and device management, it offers merchants the option to access those capabilities through a unified platform. This raises the bar from offering an individual piece of the payments stack to helping businesses abstract the complexity of managing payments across channels.
Bluefin works with more than 300 partners and 40,000 businesses and protects more than $350 billion in transactions annually. The Atlanta, Georgia-based company showcased its payment technology at FinDEVr 2014 under the name Bluefin Payment Systems.
Digital payments giant Visa has agreed to acquire fraud and financial crime prevention platform BioCatch for $2.4 billion in cash.
The acquisition will add to Visa’s existing cyber, fraud, risk, and security solutions and provide greater defense against newer threats including account takeover and money mule fraud.
BioCatch was founded in 2011. The company made its Finovate debut at FinovateFall 2014 in New York.
Visa has inked a definitive agreement to acquire behavioral and device intelligence innovator BioCatch. Visa will purchase the company from funds advised by Permira and other shareholders for $2.4 billion in cash. The move will add to Visa’s current array of cyber, fraud, risk, and security solutions and is expected to be especially helpful in managing threats such as account takeovers, scams, money mules, and application fraud.
Subject to customary closing conditions, including receipt of all relevant regulatory approvals, the acquisition is expected to close by the end of Visa’s fiscal Q2 of 2027.
“Real-time insights into customer intent continue to grow increasingly essential for institutions to establish trust within digital banking sessions,” BioCatch CEO Gadi Mazor said. “For more than a decade, we’ve demonstrated behavior’s unique ability to distinguish the criminal from the legitimate. In the last couple of years, we’ve shown how real-time intelligence-sharing networks between our customers can amplify the power of our behavioral intelligence further still. Together with Visa, we’re even better positioned to advance our mission of making the world a safer place to transact and protect consumers from financial crime.”
BioCatch offers AI and machine learning-based solutions that analyze thousands of application, behavioral, device, and network signals such as keystrokes and mouse activity, touch gestures, and device handling. This enables BioCatch’s technology to detect fraud and distinguish between legitimate and fraudulent users in real time. BioCatch’s models provide continuous monitoring to assess user intent and identify signs of potential coercion or manipulation throughout the digital banking session. More than 350 financial institutions around the world leverage BioCatch’s technology to protect 760+ million users from fraud and financial crime.
Visa’s acquisition of BioCatch comes at a time when AI, biometrics, identity, cyber defense, and fraud prevention are converging. To this point, in addition to this week’s transaction, Visa has launched its Visa Vulnerability Agentic Harness solution, an open-source, AI security tool to help customers spot and mitigate vulnerabilities at scale. Visa noted in a statement that, over the last five years, the company has invested more than $13 billion in technology and infrastructure to secure its payments ecosystem and drive fraud rates lower.
“Account takeovers and scams cost the global economy over $1 trillion annually and AI is enabling these attacks at unprecedented scale,” Visa’s president of value-added services Andrew Torre said. “BioCatch will help our clients stop fraud before it reaches the point of payment. This acquisition is part of our strategy to help clients prevent cyber threats upstream, building trust into every transaction.”
Founded in 2011 and headquartered in New York, BioCatch made its Finovate debut at FinovateFall 2014. In the years since then, the company has grown into a major financial crime prevention platform analyzing 18 billion user sessions per month and protecting 1.7 billion devices. In 2025 alone, BioCatch assessed more than $17 trillion in transactions and prevented $4 billion in fraud.
August is off to an auspicious start in the fintech world, with news of acquisitions in behavioral biometrics and regtech, and good news for a pair of firms seeking approval to initiate digital asset operations in New York and the UK, respectively. Be sure to swing by Finovate’s Fintech Rundown all week long for the latest updates and fintech headlines!
Wealth management
Asset and wealth management software specialist ZILOlaunches its digital transfer agency platform, integration mutual fund administration with digital asset capabilities.
Payments
London-based financial services provider Teyaunveils new payments card machine.
Robinhoodreceives authorization from the UK’s Financial Conduct Authority (FCA) to offer cryptocurrency services in the country.
Capital markets tokenization platform Licuidoannounces strategic investment from Ripple.
Unlimit Crypto, a division of financial infrastructure company Unlimit, secures a Crypto-Asset Service Provider license from the Cyprus Securities and Exchange Commission.
Regtech
Enterprise financial controls and reconciliation automation company AutoRekacquires UK-based compliance platform Grath.
Credit unions
Appli, maker of AI-powered smart financial calculators, inks partnership with Florida-based Connect Credit Union.
After a thrilling weekend of World Cup matches, fans in the US are readying for this evening’s big contest against Belgium. To help you while away the hours until then, here’s a look at some of the top fintech headlines that are coming across our radar today. Be sure to check back with Finovate’s Fintech Rundown all week long for the latest updates.
Digital banking
Cloud-native core banking and payments platform Thought Machinesurpasses $100 million total revenue milestone.
Digital banking platform for small businesses Bluevineexpands its services to selected foreign-resident owners of US businesses.
Back office
VyStar Credit Union expands partnership with FMSI to advance branch performance strategy.
Agentic AI
BBVAcompletes its first AI agent-initiated transaction on behalf of a cardholder.
The first month of summer is upon us! Whether your plans over the next several weeks include time away in exotic locations or sticking to the grindstone, Finovate’s Fintech Rundown is here with the fintech news you need to know. Be sure to check back all week long for the latest updates!
Lending
FinastralaunchesData Insights 2.0, an analytics solution that helps lenders transform complex data into actionable insights.
Baker Hilllaunches one-click loan participation exchange with Participate to help financial institutions scale commercial lending.
Experianbrings personal loan shopping to ChatGPT with new AI-powered experience.
Cross Riverextends $250 million forward-flow commitment for Figure’s crypto-backed loans.
Liliembeds business credit solutions to help small businesses access capital faster.
Embedded finance
Embedded payments and financing solutions provider Adyenteams up with venue management platform ROLLER.
Germany embedded finance fintech Rivertysecures regulatory approval for a Luxembourg banking license and plans to initiate operations in July 2026.
Jack Henrypartners with Woodforest National, a $9 billion, multi-state bank based in The Woodlands, Texas.
Brazil’s Nubankintroduces new offering for customers between 16 and 18 years old called NuCel that combines 5G mobile connectivity with a savings feature.
Payments
European Pay by Bank network TrueLayeracquires Dutch consumer payments company In3.
Modern card platform Highnote unveiled its new Agentic Commerce capabilities this week.
Built using Visa Intelligent Commerce, Highnote’s Agentic Commerce will allow businesses to power AI-initiated payments that feature programmable controls, tokenized credentials, and dynamic authorization.
Headquartered in San Francisco, Highnote made its Finovate debut at FinovateSpring 2022.
Courtesy of a partnership with Visa, Highnote—a modern issuing, acquiring, credit, ledger, and money movement platform—has launched its new Agentic Commerce capabilities this week. Built using Visa Intelligent Commerce, the new offering will enable businesses to securely power AI-initiated payments with programmable controls, tokenized credentials, and dynamic authorization.
The new Agentic Commerce capabilities will allow companies to add payment capabilities to AI agents while enabling software to initiate and execute transactions with predefined rules, spend controls, and approval structures. In a statement announcing the launch, Highnote listed invoice and accounts payable automation, vendor payments, operational spend management, and AI-assisted procurement as some of the initial use cases for the new solution.
“AI is quickly moving from insight to action,” Highnote CEO John MacIlwaine said. “Businesses want AI to do more than recommend or analyze. They want it to initiate and execute real financial workflows. The challenge is making those transactions secure, controlled, and operational at scale. That’s exactly what Highnote is built to do.”
Agentic commerce enables software to participate directly in purchasing and payment decisions based on preset authorization rules. The new capabilities give firms a structured framework for enabling AI-driven transactions with real-time visibility and decisioning across the payment lifecycle. Highnote’s Agentic Commerce offering will also support emerging financial operations powered by AI, such as intelligent procurement, dynamic payment routing, supplier optimization, recurring operational spend, and industry-specific autonomous payment experiences.
“Agentic commerce is already changing how businesses operate,” said Visa VP and Head of Agentic CMS Ivy Lee. “Through Visa Intelligent Commerce, we’re enabling B2B workflows where agents can initiate and complete transactions at scale. Visa provides the underlying infrastructure that makes this possible—handling the complexity so businesses and developers can focus on building differentiated experiences, not payments.”
Headquartered in San Francisco, California, Highnote made its Finovate debut at FinovateSpring 2022. At the conference, the company demonstrated how its modern card platform with a GraphQL-based API enables businesses to make card issuance an embedded capability. The demo also featured the developer experience and financial operations interface that provides control of the payment transaction lifecycle and access to transaction processing data.
Named to the Forbes Fintech 50 for a second consecutive year, Highnote last month unveiled expanded commercial card issuing capabilities for online travel agencies (OTAs), marketplaces, and travel platforms. The new offering enables these platforms to run on Highnote’s commercial card issuing platform, using virtual card programs that are purpose-built for the challenges of travel supplier payments. Highnote’s solution combines issuing, controls, ledger, and reconciliation into a single system in order to deliver faster reconciliation, bolster supplier relationships, and improve unit economics on every transaction.
The first quarter of 2026 comes to a close tomorrow. And amid the rush of end-of-month, end-of-quarter news, don’t forget that April Fool’s Day, April 1st, is right in the middle of the week.
Every year there are a handful of fintechs that like to take advantage of the occasion by having a little fun with the press, so it’s always a good idea of have a bit of extra skepticism if you come across a headline that seems a little sensational over the next few days. Here on the Fintech Rundown, we promise to do our level best to keep you fool-free!
Digital banking
Metro Credit Union to deployTyfone’snFinia Digital Banking Platform.
Corgi Insuranceacquires Corgi.com domain en route to building its fully-integrated, AI-powered insurance carrier.
Digital communications
AI-powered digital communications governance and archiving technology partner Shieldunveils new enhancements to its Shield Archive solution.
Lending
Worth, a fintech platform that helps financial institutions onboard and undewrite small and medium-sized businesses, raises $30 million in Series A funding.