This site is operated by a business or businesses owned by Informa PLC and all copyright resides with them. Informa PLC's registered office is 5 Howick Place, London SW1P 1WG. Registered in England and Wales. Number 8860726.
Finovate Blog
Tracking fintech, banking & financial services innovations since 1994
Visa is acquiring Brazil-based Pismo for $1 billion in an all-cash deal.
The purchase will help Visa add core banking capabilities and support banks in connecting to emerging payment rails.
Pismo has raised $118 million.
Visa is doubling down on financial infrastructure with its latest acquisition. The company announced today it has purchased payments infrastructure platform Pismo for $1 billion. The all-cash deal is expected to close by the end of this year.
Brazil-based Pismo was founded in 2016 and offers its core banking, payments, and lending solutions across Latin America, Asia Pacific, and Europe. The company has seen an impressive amount of growth since 2020. In total, the company services almost 80 million accounts and 40+ million payment cards for its end customers. Annually, Pismo processes around 50 billion API calls for transactions totaling $40 billion. Among its clients are Citi, Itaú, Revolut, N26, Nubank, and Cora. Prior to today’s acquisition, Pismo had raised $118 million.
Visa anticipates Pismo will help it in providing core banking and issuer processing capabilities across debit, prepaid, credit and commercial cards via cloud native APIs. Visa will also be able to leverage Pismo’s platform to provide banks support and connectivity to emerging payment rails.
“Through the acquisition of Pismo, Visa can better serve our financial institution and fintech clients with more differentiated core banking and issuer solutions they can offer their customers,” said Visa Chief Product and Strategy Officer Jack Forestell.
The Pismo deal marks Visa’s first acquisition in two years. Prior to today’s announcement, Pismo’s most recent acquisitions took place in 2021, when the company bought Currencycloud for $883 million (£700 million) and Tink for $2.15 billion (£1.8 billion).
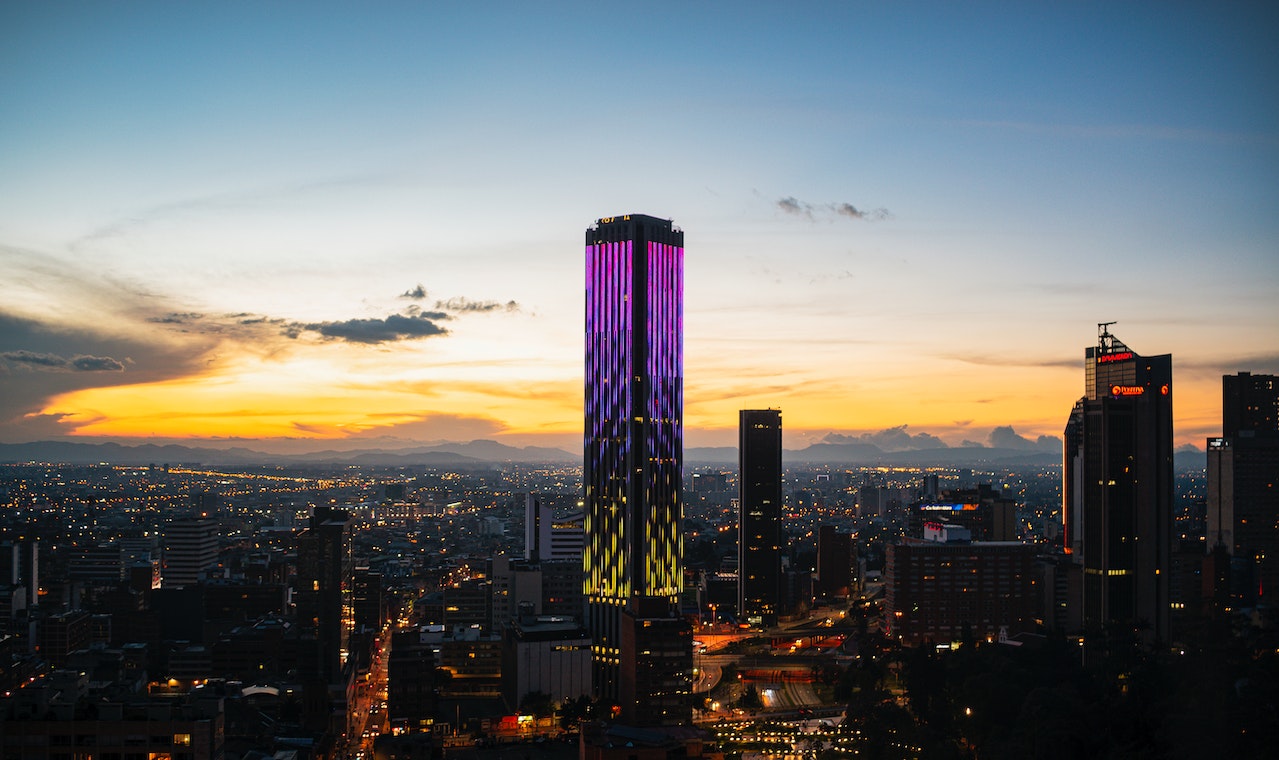
This week’s edition of Finovate Global looks at recent fintech news from Colombia.
The largest Spanish-speaking country in South America, Colombia is located in the northwest corner of the continent. With a population of more than 52 million, Colombia has the third largest economy in South America and the fourth largest in Latin America. More than 11 million people live in the country’s capital city of Bogota.
Earlier this year, the Colombian government indicated its support for open banking and open finance. Specifically, the government included the establishment of an open banking scheme as part of its National Development Plan. The fact that the current government endorsed an initiative that began with the previous administration was seen as an especially constructive sign for the future of open banking and open finance in Colombia.
One way to keep up with fintech news from Colombia is via Colombia Fintech. With information in both Spanish and English, Colombia Fintech is an association of fintech companies based in Colombia. The association provides news on Colombian fintechs, updates on relevant developments on the government and regulatory front, as well as opportunities for networking. Colombia Fintech counts more than 240 members in its community. The association was formed in 2016.
As for recent Colombian fintech news, Bogota-based payments and data security company Intexusannounced a partnership with security software company Entrust this week. Intexus will use Entrust’s digital card and instant issuance technology to support its card-as-a-service solution. The partnership is designed to enable banks and credit unions in Latin America to benefit from a unified payment card program.
“We have long been in the digital era and today’s consumers are accustomed to having resources at their fingertips instantaneously,” Intexus CEO David Rojas said. “Our partnership with Entrust allows us to simplify payment enablement for our bank and credit union customers throughout Latin America so they can focus on building relationships with their cardholders and members.”
Intexus serves clients in eight Latin American countries and issues more than 100,000 cards a month. The company was founded in 1997. Entrust provides solutions to help businesses offer trusted experiences for identity, payments, and data. Founded in 1969, the company has been a Finovate alum since 2015 when it presented its technology as part of our developers conference, FinDEVr SiliconValley.
Speaking of partnerships between Finovate alums and Colombian financial interests, we also learned this week that Ripple has entered into a new collaboration with the country’s central bank. As reported in CoinDesk, Banco de la República will test the effectiveness of Ripple’s CBDC platform to enhance Colombia’s high-value payments system. The pilot is being conducted in partnership with the country’s Ministry for the Information and Communications Technologies (MinTIC). Spanish blockchain company Peersyst Technology is also participating.
The goal of the project is to demonstrate the platform’s ability to improve the speed and reduce costs for large scale, wholesale payments, RTGS systems and similar operations, Joe Vollono, a director of CBDC business development at Ripple indicated. The project is scheduled to continue through the end of the year, and is being conducted in a controlled environment without compromising public resources.
As noted in The Paypers coverage of the announcement, Ripple previously partnered with Colombia last year to put land titles on the blockchain as part of a land redistribution program. Peersyst Technology was also a part of this initiative to permanently store and authenticate property titles on Ripple’s public blockchain.
Founded in 2012, Ripple made its Finovate debut as OpenCoin at FinovateSpring the following year. Rebranded as Ripple in 2015, the company has since grown into an innovative payment protocol and exchange network. Use cases of the company’s technology range from cross-border payments to crypto liquidity to CBDCs. Ripple’s customers include Novatti, Modulr, and Siam Commercial Bank. Chris Larsen is CEO.
Here is our look at fintech innovation around the world.
This week’s edition of Finovate Global takes a look at recent fintech developments involving companies headquartered in France.
First up is news that European Buy Now, Pay Later firm Alma has partnered with BNP Paribas and new Finovate alum Numeral to automate payments.
“As part of our goal to create the most fluid and seamless experience for both merchants and customers, paying our 11,000 and growing merchants reliably and efficiently is critical,” Alma COO and co-founder Guillaume Desloges said. “Numeral enables us to scale with confidence and focus on our core business.”
Alma Finance and Strategy Senior Manager Simon Shohet explained that the integration of Numeral into both its systems as well as BNP Paribas’ systems, audit trails, and approval rules will enable automation of the process of managing “thousands of daily payments at scale.” Shohet added, “Thanks to Numeral, we can focus on the most critical incidents and rapidly solve merchant’s issues.”
Alma plans to eventually use Numeral’s platform to become a SEPA participant via BNP Paribas. This would enable Alma to issue IBANs in its own name, a strategic advantage for the firm.
Numeral made its Finovate debut at FinovateEurope in London earlier this year. At the conference, the Paris-based company showed how financial institutions can leverage Numeral’s platform to automatically send, receive, and reconcile SEPA payments. The platform also enables financial institutions to manage payment errors via SEPA R transactions. The company is on track to process €5B in 2023.
Also this week, we learned that Revolut will begin offering customer credit products in France at the end of the month. The company announced that consumer loans will be available to Revolut’s more than two million French users starting on May 30th.
Revolut currently offers lending products in other European markets. These markets include Ireland, Lithuania, and Romania. Mortgage products are not part of the current package. But Revolut VP of Growth Antoine Le Nel said that these products are in the pipeline.
Thanks to Revolut’s embrace of open banking, prospective borrowers will be able to apply for loans without having to deal with hardcopy paperwork. Instead, applicants will get virtual “instant feedback” on their loan requests. Loans come with zero opening fees and are available from as low as €1,000 to as high as €50,000. Terms range from three months to 84 months and interest rates range from a low of 3.9% to 21.12%.
France has earned a reputation for being friendly to the cryptocurrency industry. This week’s news of a partnership between Canada’s Advanced Payment Solutions (APS), Cyprus’ Armenotech, and France’s Tempo France is another modest testament to this.
Back in at the beginning of the year, Armenotech and payments company Tempo Finance teamed up to develop an ecosystem supported by the Stellar blockchain. This week, we learn that London-based Advanced Payment Solutions has joined the pact.
APS CEO Serik Igbayev highlighted the importance of giving businesses the ability to work with traditional and digital assets. And in a statement, Igbayev praised the partnership with Armenotech for playing a key role in making this happen. “Clients increasingly demonstrate a demand for services that would enable them to operate both traditional and digital assets, combining various payment methods,” Igbayev said. “We have successfully been using state-of-the-art Armenotech solutions to meet this demand.” These solutions included tools that facilitate the conversion between fiat and digital assets, as well as products for fraud protection, security, KYC, and ALM.
Tempo France is serving as the corporate payment operator for the alliance. Founded in 2008 and headquartered in Paris, Tempo France provides a fast and secure bridge between cash and cryptocurrencies. The company offers online, offline, and digitally backed remittances to nearly 100 countries with more than 300 physical agent locations. Alla Zhedik is CEO.
Here is our look at fintech innovation around the world.
Visa is launching Visa+, a peer-to-peer payments interoperability tool.
PayPal and Venmo are piloting the launch.
Visa partners DailyPay, i2c, TabaPay, and Western Union will also integrate Visa+ within their platforms.
Fintech has solved a lot of problems by creating a multitude of different peer-to-peer (P2P) payment apps. In so doing, however, it has also created a problem– the platforms are not interoperable. Many people use different payment apps, and they don’t all work together. Visa is seeking to solve this issue with its new launch, Visa+, which helps users move money between different P2P payment apps.
Piloting the launch of Visa+ are PayPal and Venmo. After setting up a personalized payment address linked to their Venmo or PayPal account, users of either app can send and receive payments between the two platforms. Visa+ serves as the backend infrastructure behind the transfer.
PayPal and Venmo users will be able to begin using Visa+ later this year. Visa partners DailyPay, i2c, TabaPay, and Western Union will also integrate Visa+ within their platforms. The addition of new apps and platforms will not only increase the reach of Visa+, but it will also have the potential to add new use cases– such as payouts for gig workers, creators, and online marketplace sellers.
“Consumers continue to seek simple and seamless ways to digitally move money between friends and family, including the ability to send money between different payment platforms,” said Visa Global Head of New Payment Flows Chris Newkirk. “We are thrilled to partner with like-minded innovators to broaden the reach of P2P payments across platforms. Through this collaboration, Visa+ can help break down barriers for payment app users as they connect, engage and move money.”
While PayPal and Venmo are as good a starting point as any for P2P payments interoperability, there are many other players– Square Cash, Zelle, Google Wallet, and Apple Wallet– that should be added to maximize the utility of Visa+ and make it an everyday tool for U.S. users. Visa expects to launch Visa+ with select partners in late 2023. The company is planning general availability in mid-2024, so we may see additional partners in the later launch.
The new agreement enables Wirex to issue its crypto debit and prepaid cards to more than 40 countries.
The company is working on finalizing another partnership that will facilitate card issuance in Australia.
Cryptocurrency payments company Wirex unveiled a strategic partnership with Visa this week. The agreement makes Wirex a member of Visa in the U.K. and in the Asia Pacific region and will enable the fintech to issue its crypto debit and prepaid cards to more than 40 countries.
The two players began their partnership at Wirex’s launch in 2015, when the U.K.-based company unveiled its crypto-enabled Visa card. The payment card enables users to buy, hold, exchange, and sell 150 currencies– from traditional to cryptocurrencies. Additionally, Wirex customers can use their Visa card to spend their currency holdings at live rates at more than 80 million locations where Visa is accepted.
In addition to the live crypto-to-fiat conversion, Wirex offers free international ATM withdrawals, zero monthly fees, free fiat-to-fiat exchanges, and up to 8% back in crypto rewards on every purchase.
“It’s great to strengthen our partnership with Visa, who have played an important role in allowing us to bridge the gap between the traditional and digital economies,” said Wirex APAC Regional Managing Director Svyatoslav Garal. “Visa’s proven commitment to safety, security and innovation will help us to continue developing a next-generation app and card.”
The partnership aligns well for payments giant Visa, which is working to position its brand in the Web3 space. “Visa wants to bring more payment options to consumers by connecting digital currencies with our network of banks and merchants,” said Visa Head of Digital Partnerships, Asia Pacific Matt Wood. “We’re excited that Wirex is expanding their focus on Asia Pacific, making it easy and seamless for people to spend their crypto balance at the millions of merchants that accept Visa in the region.”
Wirex was founded 2014 by Pavel Matveev and Dmitry Lazarichev. Since then, the company has raised $27.8 million in funding and facilitated more than $20 billion in crypto transactions. Wirex, which expanded to the U.S. last year, said it plans to make a partnership announcement “in the coming weeks” that will facilitate card issuance in Australia.
Good news for fintech startups in developing markets! Quona Capital recently announced that it has closed its latest fintech fund, its third, at $332 million. The venture capital firm, which specializes in emerging markets, noted that the amount raised topped its target of $250 million. The new fund, Fund III, will be focused on companies that are developing technologies that expand access to financial services for consumers and businesses in regions ranging from Latin America and India to Southeast Asia, MENA, and Africa.
“Since our earliest days, Quona has been dedicated to expanding the frontiers of financial inclusion – investing with conviction in markets and technology-enabled models improving access and quality of financial services for the masses,” Quona co-founding managing partner Monica Brand Engel said in a statement. “Our prior fund performance, robust pipeline of inclusive fintechs, and growing LP interest in our offerings are ringing endorsements of our view on the prospects of impact-oriented venture investing in emerging markets.”
With aggregate capital of more than $745 million, Fund II is the firm’s third fund since Quona Capital was launched in 2015. Those contributing to the fund as investors include global asset managers, insurance companies, both investment and commercial banks, endowments, foundations, family offices, and more. And while many of the investors in Fund III have invested in Quona Capital funds previously, the new fund did receive capital from 20 new investors, as well.
According to Quona Capital, the startups in its portfolio have served nearly nine million small and medium-sized businesses and over 30 million retail customers. Quona Capital startups have raised nearly $4 billion in capital and generated more than $800 million in revenues. Among these firms are India-based consumer lending company ZestMoney, Southeast Asia-based fintech marketplace ula, and long-time international remittance firm and long-time Finovate alum Azimo – which was acquired by Papaya Global earlier this year.
Here is our look at fintech innovation around the world.
Central and Southern Asia
Indian neobank ZikZuk acquired tax e-filing platform TaxSpanner.
National Bank of Pakistan turned to Finastra to enhance its trade finance operations.
Lentra, a fintech based in India, secured $60 million in Series B funding for its loans-as-a-service business for banks.
Latin America and the Caribbean
AstroPay introduced its Mastercard prepaid card in Brazil.
Mexico-based B2B payments company Mendel raised $60 million in new funding.
Brazil’s Agrolend, which provides credit to the country’s farmers, secured $27 million in Series B funding.
Asia-Pacific
Ant Group introduced its Buy Now, Pay later offering in Hong Kong.
Vietnam-based Sacombank partnered with Temenos to enhance digital banking.
Philippines-based neobank Tonik unveiled its all-digital lending products, Flex Loan and Big Loan.
Sub-Saharan Africa
Nigerian fintech Paga unveiled its Visa-branded card this week.
Pan-African paytech Cellulant secured a Payment Systems Operator license from the National Bank of Uganda
Samsung South Africa launched its digital wallet, Samsung Wallet.
Central and Eastern Europe
Polish fintech Ramp locked in $70 million in Series B funding to build payment rails for cryptocurrency investors.
Co-investment platform for European startups SeedBlink secured licensing from the Romanian Financial Supervisory Authority (ASF).
Genome, an Electronic Money Institution based in Lithuania, partnered with Entrust to simplify digital payments.
Middle East and Northern Africa
UAE-based Wio Bank went live with Mambu’s cloud-native banking platform.
Pyppl, a financial services platform based in the UAE, raised $20 million in Series B funding.
Saudi Arabia’s central bank presented its open banking framework.
Visa is expanding its integration with Square’s instant transfer feature into Canada.
Square’s Canadian merchant clients can access their funds in real time, instead of waiting for the next business day.
Instant transfers are enabled by Visa Direct, a VisaNet processing capability that facilitates real-time delivery of funds.
One of the themes at FinovateFall earlier this month was how organizations can leverage real time data. When it comes to the movement of money, timing is everything. So it’s no surprise to see Visa’s announcement this week that it will expand its integration with Square’s instant transfer feature into Canada.
Under the new integration, Square’s Canadian merchant clients can now access their funds faster than the next business day. When they link an eligible debit card, Square’s Canada-based merchant clients can transfer funds instantly to an external bank account.
Used for rapid merchant settlement, Square’s instant transfers are enabled by Visa Direct, a VisaNet processing capability that facilitates real-time funds delivery directly to bank accounts. As a result, businesses experience increased cash flow, which can be a major pain point, especially for small businesses.
“Cash flow management and more immediate access to funds is critical for small businesses to survive and thrive in a rapidly evolving payments ecosystem,” said Visa Canada’s VP and Head of New Payments Jim Filice. “Together with Square, we’re committed to supporting Canadian small businesses and helping to identify solutions that can benefit them by delivering fast, reliable and secure access to funds.”
Western Union is bolstering its partnership with Visa by expanding its integration with Visa Direct.
Visa Direct is Visa’s real-time money movement network.
The expansion will bring Visa Direct to Western Union’s U.S. clients, enabling them to send money in near-real-time to Visa debit cards in Colombia, El Salvador, Jamaica, Romania, and Thailand.
Money transfer firm Western Union is building on its partnership with Visa this week. The Colorado-based company is expanding its integration with Visa Direct, Visa’s real-time money movement network.
Under the agreement, the pair will bring Visa Direct to Western Union’s U.S. clients, enabling them to send money in near-real-time to Visa debit cards in Colombia, El Salvador, Jamaica, Romania, and Thailand. Western Union and Visa first teamed up in 2019 to enable Western Union customers in more than 20 countries across Europe to send and/or receive funds directly to Visa debit card holders.
“Western Union and Visa share a vision for modern money movement, one that ensures cross-border payments are reliable, efficient and transparent, with convenience and the customer’s channel of choice at the center of our customer experience,” said Western Union President of the Americas Gabriella Fitzgerald. “Our partnership with Visa underscores the benefits that collaboration brings to realizing this shared vision for our joint customers around the globe.”
Visa first launched Visa Direct in Europe in 2017 as a real-time payments platform to allow companies to leverage Visa’s global reach and scale for cross-border payments. In addition to Western Union, nearly 550 partners, including Adyen, The Bancorp, Fiserv, and Stripe support Visa Direct solutions.
“Visa is transforming cross-border payments with Visa Direct by helping to bring the ability to securely send and receive funds in near-real-time to more use cases around the world,” said Senior VP North America Head Yanilsa Gonzalez-Ore. “Through this partnership, we are using Western Union’s digital capabilities to help US customers send money to their family and friends and provide a means to help with bills, as a gift, or for an emergency.”
Founded in 1851, Western Union is one of the oldest cross-border money transfer pioneers. The company’s global financial network bridges more than 200 countries and territories and approximately 130 currencies. In a partnership earlier this year, Western Union integratedMarqeta’s payment cards solution into its digital wallet and digital banking platform in Europe.
A $50 million investment will help Egyptian digital payments company Paymob expand into new markets in both the Middle East and Africa. The round was led by Kora Capital, PayPal Ventures, and Clay Point, and represents the largest ever Series B round in Egyptian fintech history.
“Central Bank of Egypt initiatives that are continuously being introduced in the market to support fintech companies were key to Paymob’s growth,” company founder and CEO Islam Shawky said. “The Central Bank has created a regulatory framework to help fintech flourish and participate in making Egypt’s digital financial inclusion ambitions a reality.”
Processing more than 85% of the market share of transactions in Egypt with its mobile wallet technology, Paymob serves customers in five markets including Palestine, Pakistan, and Kenya. The investment comes as Paymob reports strong 2021 growth, including year-on-year growth in merchant partners and monthly volumes of 4x as of December. The company has onboarded more than 10,000 merchants in less than two years en route to a goal of onboarding one million SMEs.
This week’s funding brings Paymob’s total capital to more than $68.5 million.
South African bank Capitec announced that it was teaming up with two Finovate alums, Entersekt and nCino.
“Capitec has embraced an agile and innovative approach to growth,” nCino CEO Pierre Naudé said. “We’re glad Capitec saw a partner in nCino and look forward to providing the bank with industry-leading technology and a flexible platform that will help drive the sustainability and growth of its business banking operations.”
nCino made its Finovate debut in 2017 at FinovateEurope. The company’s flagship offering, its cloud-based Bank Operating System, provides a complete end-to-end banking solution that combines CRM, loan origination, workflow, ECM, business intelligence, and reporting all in a single location. nCino’s technology replaces disparate point solutions and manual processes with a modern, digitally-optimized experience.
The technology will enable Capitec to spot high risk e-commerce transactions in real-time, enhancing security without interfering with the customer experience. Entersekt’s EMV 3D Secure solution is pre-integrated with NuDetect from NuData Security – also a Finovate alum – which leverages behavioral biometrics and machine learning to help tell the difference between authentic users and potential fraudsters.
“We are constantly looking for ways to offer the best security possible without impacting our customers’ experiences,” Capitec Bank Marketing and Communications Executive Francois Viviers said. “By implementing Entersekt’s EMV 3D Secure solution with behavioral analytics from NuData Security, we are able to provide an additional level of protection for our e-commerce transactions. This also allows our team to continue to innovate, keeping our customers secure and Capitec at the forefront of digital banking innovation in South Africa.”
Entersekt demonstrated its technology as part of our developers conference, FinDEVr, in San Francisco in 2014. The company, headquartered in Cape Town, South Africa, finished 2021 with a “significant investment” from Accel-KKR. This spring, Entersekt announced partnerships with edtech Mindjoy and the MiDO Foundation to promote financial literacy, as well as a collaboration with credit union service organization (CUSO) Bonifii to bring context-aware authentication solutions to credit unions.
Here is our look at fintech innovation around the world.
Visa is bringing its Installment Solution to Air Canada, allowing customers to pay for their qualifying purchases over time.
According to Visa’s recent survey, a third of Canadians interested in using installments plans would do so for travel and entertainment.
Air Canada will be among the first group of airlines to use Visa’s BNPL tool.
If you’re looking to fly now, pay later in the friendly Canadian skies, you’re in luck. Visaannounced this week it will collaborate with Air Canada to bring its Visa Installment Solution, a buy now, pay later (BNPL) solution to the Canadian airline.
Air Canada, Canada’s largest airline, will be among the first group of airlines to use Visa’s BNPL tool. The Visa Installment Solution offers eligible cardholders a more flexible way to pay for qualifying purchases. At checkout, customers can opt to convert their purchase into smaller, equal payments made over time. With Visa’s Installment Solution, the card issuer sets attributes such as the duration of the installment plan, interest, and fees.
Keith Wallis, senior director Distribution and Payments, Air Canada expects the additional payment option will elevate the customer experience. “Visa is one of the most trusted brands in Canada and their close collaboration with major Canadian financial institutions provides a unique opportunity to deliver an exceptional shopping experience to our mutual customers,” Wallis said.
According to Visa’s recent survey, a third of Canadians interested in using installments plans would do so for travel and entertainment. In fact, BNPL is on the rise across the board. A separate survey found that one third of shoppers use BNPL at least once a month, while 9% of consumers surveyed use it more than once a week.
Last August, Visa announced it was collaborating with payment solutions company i2c, which is using the Visa Installment Solution to launch BNPL capabilities for their participating issuers in North America. The partnership offers merchants an accelerated path to providing consumers with a BNPL option at checkout. Visa has also formed partnerships with Moneris, CIBC, Commerce Bank, Desjardins Group (Desjardins), Equinox Payments, ScotiaBank Versapay, HSBC, ANZ, GHL Systems Malaysia, Quest Payment Systems, Home Credit Bank, Russian Standard Bank, Cybersource, FIS, Global Payments, and TSYS to enable the Visa Installments Solution.
While much of the financial world is united in its efforts to distance itself from Russia as the country’s leader, Vladimir Putin, orders his forces continue their invasion of neighboring Ukraine, many of those in the cryptocurrency world are decidedly more ambivalent.
Is this a function of the underlying libertarian spirit that powers much of the enthusiasm for digital assets? Or is this just a reflection of a relatively young industry that is not yet ready to take on the responsibilities that its growing role in the financial world will eventually demand?
First, the ask. At the beginning of the week, Ukrainian Vice Prime Minister and Minister for Digital Transformation Mykhailo Fedorov took to social media to ask cryptocurrency exchanges to block transactions from Russia. Federov’s request was not just directed at the Russian government, or the country’s notorious oligarchs, but for everyday Russian users of cryptocurrencies, as well.
“It’s crucial to freeze not only the addresses linked to Russian and Belarusian politicians,” Federov wrote on Twitter, “but also to sabotage ordinary users.”
In the same way that some people have criticized the international sanctions regime against Russia for allowing a loophole when it comes to energy – specifically banning oil and gas exports from Russia – Federov and others have warned that not restricting, if not outright eliminating, Russian access to cryptocurrencies is a critical flaw in the effort to financially squeeze the Russian economy.
In response to this request, many nations have taken action. France’s Finance Minister, Bruno le Maire, said that the EU would include cryptocurrencies in its sanctions. The Financial Conduct Authority in the U.K. has reminded its U.K.-based and regulated cryptocurrency companies of their obligations to respect the sanctions policy against Russia. Even those cryptocurrency firms that are not regulated have been encouraged to support the sanctions regime. “We would urge unregulated member(s) to take action to ensure your platforms do not become a loophole for sanctioned Russians,” U.K. cryptocurrency organization Crypto UK said in a statement.
In the U.S., while some lawmakers have encouraged the government to help ensure that Russians are not using cryptocurrencies to skirt sanctions, the Biden Administration appears less concerned about that threat – at least on the large scale. Carol House, director of cybersecurity for the National Security Council said this week that “the scale that the Russian state would need to successfully circumvent all U.S. and partners’ financial sanctions would almost certainly render cryptocurrency as an ineffective primary tool for the state.” If anything, it seems that U.S. authorities are somewhat more concerned about potential theft and cybersecurity issues surrounding cryptocurrency companies than they are of Russians using these firms and exchanges for what would otherwise be legitimate purposes.
The response from cryptocurrency companies – including some of the largest firms like Binance and Kraken – have suggested that while they are comfortable blocking the accounts of sanctioned Russians, banning all Russians from their platforms is, for these companies, a bridge too far. At least for now.
“We are not political, we are against war, but we are here to help the people,” Binance founder and CEO Changpeng Zhao said, explaining his company’s position. “There are a few hundred individuals that are on the international sanctions list in Russia, mostly politicians, and we follow that very, very strictly.” But Zhao added that Binance draws a line “between the Russian politicians who start wars and the normal people, many normal Russians do not agree with war.”
Similarly, Kraken CEO Jesse Powell tweeted, “I understand the rationale for this request (to block Russians from Kraken’s platform) but, despite my deep respect for the Ukrainian people, Kraken cannot freeze the accounts of our Russian clients without a legal requirement to do so.”
That said, Powell noted, “Russians should be aware that such a requirement could be imminent.”
Additionally, it should be added many cryptocurrency companies are not agnostic to the conflict in the Ukraine and have lent their support to the Ukrainian cause. Federov expressed his, and his country’s, appreciation for the efforts of firms like Polkadot, which donated $5 million, as well as Solana and Everstake, which have created a joint effort called Aid for Ukraine in partnership with the country’s Ministry of Digital Transformation.
“This will certainly contribute to the Ukrainian victory as well as support civil people,” Federov said on Twitter earlier this week. “We will win – the best people (are) with us.”
FinovateEurope 2022 is only a few weeks away. Register today to save your spot at our annual European fintech conference: March 15 digitally and live in London on March 22 and 23.
Here is our look at fintech innovation around the world.
Selling nearly 290 million shares priced at $9 in its initial public offering on the New York Stock Exchange this week, Brazilian digital bank Nubank has raised $2.6 billion, reaching a market value of $41 billion. An alumni of Finovate’s developer’s conference FinDEVr in 2016, Nubank is now the most valuable financial institution in Latin America in addition to being the world’s biggest digital bank. CEO David Vélez, who co-founded the company in 2013 with an initial investment of $2 million from Sequoia Capital and Kaszek Ventures, now owns a stake in the company worth $8.9 billion at the IPO price.
“We don’t think the banking branch will survive the way it is,” Vélez said to CNBC this week. “It is too costly to serve the majority of users, especially in emerging markets where you have a very high cost of operations, so a lot of that physical infrastructure will probably disappear.” Vélez predicted that most financial services providers will transition into digital entities in the next five to ten years because of this, leading to an increased focus on customer service as well as lower costs and interest rates.
With more than 48 million customers in Brazil, Mexico, and Colombia, and onboarding more than two million new customers a month on average, Nubank offers financial products for spending, savings, investments, loans, and insurance. The company claims to have provided more than five million people with their first credit card or bank account as of September 30, and to have saved its customers more than $4 billion (R$27 billion) in bank fees and more than 113 million hours of waiting time since inception.
Vélez said that the capital from the IPO will help fuel Nubank’s expansion in Mexico and Colombia, en route to becoming a truly pan-Latin American banking services provider. “There is a lot of opportunity to build the next generation of financial services, so we will continue to invest and grow for a very long time,” Vélez said an interview with the Financial Times.
FinovateEurope 2022 is right around the corner. If you are an innovative fintech company with new technology to show, then there’s no better time than now and no better forum than FinovateEurope. To learn more about how to demo your latest innovation at FinovateEurope 2022 in London, March 22-23, visit our FinovateEurope hub today!
Here is our look at fintech innovation around the world.
CinetPay, a digital finance platform serving merchants in French-speaking Africa secured $2.4 million in seed funding from 4DX Ventures and Flutterwave.
Online fraud prevention company SEON inked an agreement with a pair of African neobanks, Carbon and FairMoney.
South African device identity and authentication solutions provider Entersektannounced a “significant investment” from U.S. private equity firm Accel-KKR.
German biometrics and digital identity verification company Passbase secured $10 million in Series A funding, as well as another $3.5 million in seed-2 investment.