5 Things JPMorgan’s AI Agent Warning Means for Banking

5 Things JPMorgan’s AI Agent Warning Means for Banking

On JPMorgan’s third quarter earnings call yesterday, CEO Jamie Dimon expressed concern about AI agents, while CFO Jeremy Barnum discussed the risks of credential sharing and screen scraping.

JPMorgan has one of the largest technology budgets in the banking sector, with plans to spend almost $20 billion on technology overall in 2026. But the C-suite executives’ comments are in no way a rejection of agentic AI as an enabling technology. The bank is already using agentic AI to automate workflows, improve employee productivity, and streamline internal processes. “Internally, we use agents to do things here, and we are going to continue to do that,” Dimon said on the call. “And we do. We will use it for customers, but our focus would always be do a great job for customers.”

But when it comes to consumer use of agentic AI, the bank said it is restricting certain methods external agents use to access customer accounts. Barnum said the bank is blocking insecure access where it can and working toward safer alternatives.

This stance has five implications banks should consider as they weigh their own attitudes toward the use of external agents.

Agentic AI could reignite the screen-scraping debate

For years, the banking industry has been moving away from screen scraping and toward more secure, API-based data sharing. However, as consumers begin using AI agents capable of navigating banking websites like human customers, the industry’s progress toward standardized, permissioned data access could face a new challenge.

Agentic AI introduces a new version of the old screen-scraping debate, as third parties may be able to access customer information without relying on bank-approved APIs. JPMorgan, which clashed with Plaid in 2025 over the terms of API-based access to consumer-permissioned financial data, has already shown interest in controlling how third parties interact with its systems. And while cybersecurity concerns are one reason the bank is wary of opening up access, the value of the data is another. Consumers’ transaction histories and account balances are valuable sources of information, particularly for AI agents capable of analyzing spending patterns, recommending financial products, and influencing financial decisions.

While some banks may seek to restrict external agents, others may view secure agent access as an opportunity to improve the customer experience. Either way, the rise of agentic AI could accelerate demand for standardized, secure, permissioned access that allows AI agents to interact with banking systems without undermining the open banking infrastructure the industry has spent years building.

Banks could lose control of the customer relationship

If consumers begin using AI assistants to manage their finances, those agents could become the primary interface between customers and their banks. For example, an AI agent might compare savings rates, and either recommend switching providers, or initiate a transfer on a consumer’s behalf without the consumer ever opening a banking app.

On the earnings call, JPMorgan’s executives acknowledged the competitive implications of AI and fintech while emphasizing the value of the bank’s established customer relationships. However, those relationships could become less influential if consumers increasingly rely on AI agents to make financial decisions. Instead of choosing a bank based on its mobile app, brand recognition, or existing relationship, consumers could delegate more of their financial management to agents that prioritize interest rates, fees, and product features. In this scenario, banks risk becoming interchangeable providers of financial products rather than the primary destination for managing money.

We’re slowly approaching a world in which consumers don’t need to take action, but can instead give their agent permission to take action on their behalf. In this new reality that doesn’t rely on consumers to take small actions like transferring funds to multiple different bank accounts per week in order to maximize yield, banks may need to compete on the quality and accessibility of their financial products, not just on their digital banking experiences.

Consumer authorization may not be enough to protect consumers

The rapid pace of AI development has raised concerns about whether safeguards can keep up. Additionally, it is a complicated enough technology that everyday consumers do not understand implications or risks, despite giving AI agents permission to access their financial accounts. Especially in the early stages of the technology, where guardrails and standards are still in formation, an agent could easily misinterpret instructions, expose sensitive information, or initiate an unintended transaction.

JPMorgan’s executives specifically raised concerns about customers sharing credentials and the potential liability associated with agent activity. When consumers share their banking credentials with an AI agent, they may be granting it access to far more information and functionality than is necessary to complete a particular task. If an agent makes a mistake, determining who is responsible for the mistake is complicated. If an AI agent transfers funds to the wrong account, for example, who is liable?

As consumer adoption increases, there will likely be growing demand for granular permissions, transaction limits, agent authentication, revocable access, and clearer liability frameworks. It is also an example of how authorization and authentication are not the same thing. An agent may be properly authenticated but still attempt an action beyond what its user intended. Know Your Agent (KYA) technologies could help bridge that gap by verifying an agent’s identity, establishing the scope of its permissions, and helping to keep its actions within authorized boundaries.

Banks may favor their own AI agents over third-party platforms

In the early 2010s, fintechs introduced a competitive tension to the banking scene. Banks were worried about losing customers to fintechs, which offered new technologies and more intuitive user interfaces. As banking-as-a-service gained popularity, however, it created new opportunities for banks and fintechs to collaborate rather than compete. Agentic AI is bringing a similar tension back as banks want to use AI to improve their services, but they may be less comfortable allowing outside agents to interact with customer accounts.

This tension could encourage banks to steer consumers back to their own websites and mobile apps by building their own financial assistants or partnering with a network of approved AI providers. Offering agentic capabilities within their existing digital banking environments will help banks offer customers the convenience of AI-powered financial management while maintaining greater control over data access, security, and the customer experience. However, this approach still has limitations, as it still may not allow consumers to use their preferred third-party AI assistants.

Third-party technology providers that can demonstrate strong security, governance, and integration capabilities may have an advantage over those relying on unrestricted website access. Instead of competing directly with banks for the customer relationship, these providers could position themselves as trusted partners that enable secure agent-to-bank interactions. Just as banking-as-a-service created new opportunities for collaboration between banks and fintechs, agentic AI could give rise to a new category of infrastructure providers focused on agent authentication, permission management, and secure financial transactions.

Trust can be both a competitive advantage and an obstacle

Banks have spent decades establishing customer trust, especially when it comes to protecting their personal information. JPMorgan’s priorities are a reflection of preserving this trust, as its executives identified trust as a competitive asset. However, as Barnum pointed out, trust doesn’t excuse banks from delivering good customer experiences.

So how can banks balance trust with improving the customer experience in the age of agentic AI? If they impose too many restrictions on third-party agents, they risk frustrating consumers who want more convenient financial management tools. However, if they allow an agent free-for-all on their sites, they risk exposing customer data, enabling unauthorized transactions, and ultimately eroding the trust they’ve worked so hard to establish.

Here’s the takeaway: the institutions that succeed may be those that balance security with interoperability, rather than simply blocking external innovation. To be clear, JPMorgan did not state that it plans to permanently shut out all external AI agents. Instead, its executives indicated that the bank is working on safer ways to enable access. “We are building tools to [protect customers from risks associated with agents] too,” added Dimon. “In the meantime, we are not gonna allow just any agent to come, outside agent to come inside the company because it is just too risky for clients and for JPMorgan.”
Photo by Caden Garcia

Ocrolus Adds Document Fraud Detection to Mortgage Workflows

Ocrolus Adds Document Fraud Detection to Mortgage Workflows

Ocrolus, a vertical AI workflow and analytics platform for lenders, has announced that its document fraud detection solution, Ocrolus Detect, will now be included at no additional cost for all its mortgage customers. Ocrolus Detect reviews bank statements, pay stubs, and tax forms for tampering. Underwriters see the results of the review in the Ocrolus platform or the Encompass embedded viewer where they already review the file.

Ocrolus has leveraged its integration with Resistant AI to enable Detect to spot documents that are created or edited by generative AI. Unfortunately, Generative AI makes it easy and inexpensive to produce false financial documents across different types of lending. Ocrolus has determined that 12% of loan applications processed via its platform contain suspicious activity. Detect determines both what a document says and how it was created, and gives each document an authenticity score with reason codes to indicate to the underwriter where the issue was located and why it was flagged.

This latter point is key. Detect identifies specific issues in flagged documents and gives lenders an explainable result. This can help lenders meet new AI governance requirements from Freddie Mac and Fannie Mae that went into effect earlier this year. To this end, Ocrolus has also integrated with Fannie Mae’s Income Calculator and Freddie Mac’s AIM Check, and maintains a formal AI governance program with controls mapped to both frameworks. The controls are audited every year by independent third parties and through application security testing.

Lenders using Detect have already reported positive results. JMAC Lending, a wholesale lender based in Costa Mesa, California, analyzes every file in its Encompass pipeline with Detect. In doing so, JMAC prevented nearly $2 million in fraudulent loan volume in the first months of use. The lender reported that in one instance, Detect uncovered a bank statement showing a $300,000 deposit in an account that held only $1,200.

“The conversation with lenders has moved from ‘Can AI do this?’ to ‘Can I trust it enough to put it into production?'” Ocrolus General Manager of Mortgage Nadia Aziz said. “Fraudulent bank statements and income documents can now be created in minutes and are becoming harder to distinguish from the real thing. Fraud screening should be built in, not an added expense for lenders. Detect shows underwriters exactly why a document was flagged, and the underwriter makes the call.”

Founded in 2014 and headquartered in New York, Ocrolus won Best of Show in its FinovateFall appearance in 2021 and most recently demoed its technology on the Finovate stage at FinovateFall 2023. At the conference, the company showed how its AI-driven document automation platform optimizes credit decisions in small business, mortgage, and consumer lending, enabling firms to automate financial analysis and help borrowers access the financing they need faster and on the best possible terms. Ocrolus’ platform analyzes 750,000 credit applications a month, and its technology powers digital lending experiences for more than 500 customers, including SoFi, PayPal, Square, and Zillow. Sam Bobley is co-founder and CEO.


Photo by Tierra Mallorca on Unsplash

Stablecore’s Nick Elledge on Making Stablecoins “Feel Like Banking”

Stablecore’s Nick Elledge on Making Stablecoins “Feel Like Banking”

Stablecoins have emerged as one of the most interesting developments in the DeFi industry, with the potential to reshape payments more broadly. Stablecoins are cryptocurrencies pegged to a reserve asset, typically a fiat currency such as the US dollar, and are designed to combine the technological advantage of digital currencies with the relative price stability of traditional money. They have become increasingly attractive because they can facilitate fast, low-cost transactions—especially across borders—and help bridge the gap between decentralized finance and traditional finance.

What are the opportunities for banks and other financial institutions when it comes to embracing stablecoins and, importantly, what are the risks? Are stablecoins just the latest fad from the cryptocurrency world (remember NFTs?) or, as with AI, could they offer financial institutions more efficient ways to serve a wider range of customers and members?

To discuss this and other issues surrounding stablecoins and digital assets, we spoke with Nick Elledge, Co-founder and Chief Operating Officer for Stablecore. Headquartered in Dallas, Texas, and founded in 2025, Stablecore offers a platform that enables community and regional banks, as well as credit unions, to deliver instant payments, stablecoins, tokenized deposits, and digital asset solutions from within their own current banking environment. The company won the “Excellence in Stablecoins, Tokenized Deposits, and Tokenized Assets” category of the 2026 Finovate Awards.


Congratulations on winning the “Excellence in Stablecoins, Tokenized Deposits, and Tokenized Assets” category of the 2026 Finovate Awards. What does this recognition mean for Stablecore and what do you think ultimately set Stablecore apart?

Nick Elledge: This recognition validates something we have believed from the start: money movement across the U.S. banking system will require infrastructure for stablecoins and tokenization.

Our team deliberately built a platform only for regulated American banks and credit unions. It means a great deal to see our team’s work recognized by Finovate. Many thanks to the Finovate team and the panel of judges.

What sets us apart is that we only focus on banks and credit unions. You cannot waltz in off the street and do that—it takes deliberate focus to serve the technology, compliance, and risk needs of the banking market.That focus is what has led to our success. This is a unique and robust platform in the banking market.

Tell us about the problem you set out to solve. What was missing from the market, and how did that shape your approach?

Elledge: Despite the interest in stablecoins and tokenized deposits, most institutions had no credible, compliant way to offer any of it because their existing tech stacks did not support digital assets. That reality shaped our approach at Stablecore.

We treated compliance as a first-class feature: a policy engine that controls which stablecoins, transaction types, limits and customer segments are enabled; blockchain screening through Chainalysis, TRM Labs and Notabene; and transaction data feeding Nasdaq Verafin and LexisNexis so digital assets flow through the AML and BSA workflows a financial institution already runs.

We also give clients pre-built model risk assessments and disclosure templates built for examiners. Essentially, we addressed integration and implementation the way a bank would, so onboarding to Stablecore would be as turnkey as possible.

What have you learned from bringing your offering to market? Are there particular results, customer outcomes, or milestones that demonstrate its impact?

Elledge: The biggest lesson is that institutions want stablecoins to feel like banking, not like crypto. Customers (retail and commercial) should be able to hold stablecoins as native account balances, send money globally in seconds, and move between fiat and digital assets without friction. This leads to stronger relationships between banks and their customers.

We also confirmed our belief in the power of network effects. Joining the Jack Henry Fintech Integration Network and announcing our partnership with Q2 Innovation Studio put these capabilities in front of thousands of institutions through platforms they already use. More recently, Velera and Nasdaq Verafin—a huge name in anti-financial crime management—announced us as key technology partners. Plus, we have the endorsement of six state banking associations. This evolving network has opened up so many important conversations between bankers and Stablecore.

For our clients, the outcomes are non-interest income from transaction fees, deposit retention from customers who might otherwise flock to crypto and fintech apps, and new deposits from customers bringing stablecoin holdings back into the banking system.

Additionally, we have heard directly from our clients that Stablecore can be a bridge to creating and maintaining relationships with a new generation of digital natives who expect to hold and move money on-chain—the importance of this cannot be overstated.

Looking at the broader stablecoin, tokenized deposit, tokenized asset landscape, what is changing most significantly right now, and how is that influencing your strategy?

Elledge: The conversation inside banks has shifted from “whether” to “how.” As the regulatory framework matures, boards and examiners are asking practical questions about compliance, custody and risk, which is where our work starts. At the same time, individuals and businesses are already using stablecoins through crypto platforms, so institutions that wait risk losing deposits and relationships.

We are also seeing stablecoins, tokenized deposits and instant payment rails converge. Institutions will not want a separate system for each. Instead, they will require a level of smart, agentic payment routing that optimizes for speed, cost, and context. That’s what we’re building inside of Stablecore—a way to manage multiple rails (including FedNow and RTP) from one centralized, compliant interface. We’ve also designed our architecture for broader tokenized assets such as securities, loans and treasuries. Our strategy is to be the single infrastructure layer that lets a bank or credit union add the next rail or asset class without rebuilding.

What’s next for Stablecore? What should we expect to see from you over the next 12 to 18 months?

Elledge: We expect that more clients will turn on tokenized deposits via Stablecore. Deposits are critical for relationships in banking and this is the next evolution. Additionally, Stablecore will deliver a better, smarter payments manager. We can and will empower banks and credit unions to manage stablecoins side by side with instant payments like FedNow and RTP , with one policy engine and one compliance view. This will be a huge win for our clients.

Lastly, look for more announcements on the expansion of our alliance network across the banking tech stack and more endorsements and preferred vendor relationships. Our focus will remain consistent. We’re building for U.S. banks and credit unions and ready to help them embrace the digital assets era.

Splitit Plans to Launch White-Label Credit Card

Splitit Plans to Launch White-Label Credit Card
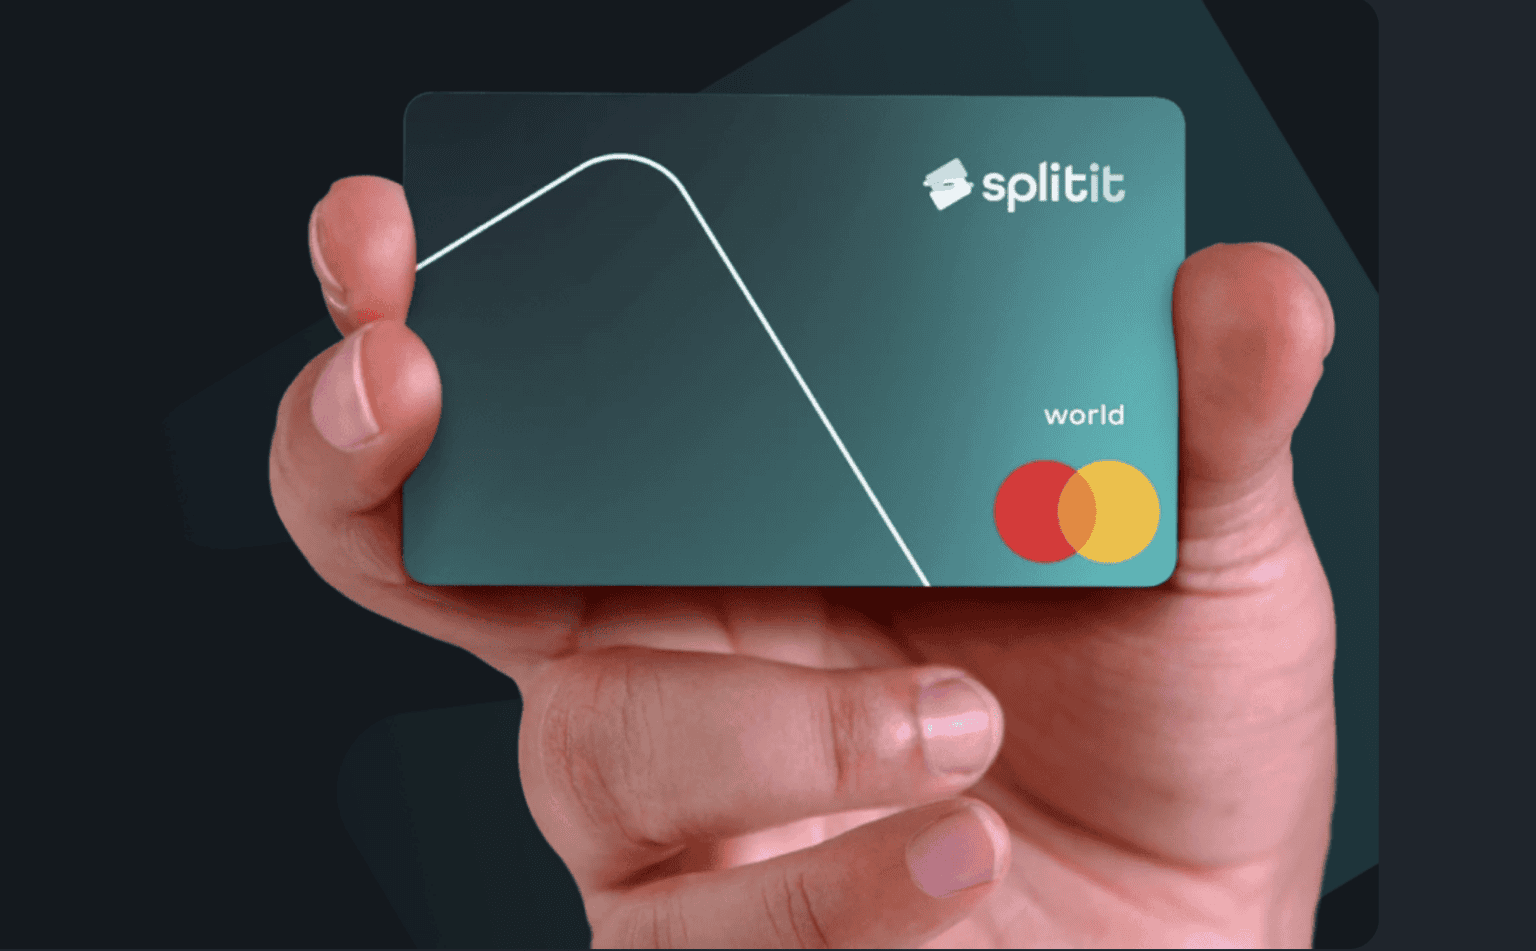
  • Splitit unveiled plans for the Splitit World Mastercard, a white-label credit card that combines traditional credit card functionality with flexible installment payments.
  • The card allows consumers to automatically split purchases above a customizable spending threshold into monthly installments, with the option to adjust repayment plans.
  • The offering, expected to become available in early 2027, will help mid-sized banks and credit unions compete with BNPL providers while maintaining ownership of their customer relationships.

Georgia-based BNPL solutions provider Splitit unveiled plans for the Splitit World Mastercard, a new white-label credit card that offers the flexibility of installment plans.

Shoppers can use the new credit card to make everyday purchases and use the app to set their own spending threshold. Any purchases over that amount can be automatically split into monthly installments to repay. Throughout the month, cardholders can switch a purchase to pay-in-full or they can adjust the installment plan before the statement is due.

Splitit World Mastercard combines Mastercard’s network infrastructure with Splitit’s installment technology. Because banks bring their own customers and brand, the new card offering allows banks to expand their lending and payment offerings to provide greater choice and flexibility while maintaining ownership of the customer relationships.

“The Splitit World Mastercard is a new type of credit card built for banks and credit unions that resembles the simplicity of debit for consumers and pairs it with the flexibility of installments,” said Splitit CEO Nandan Sheth. “Banks already have the relationship, the brand and the primary account. What many of them lack is a way to offer installment plans at the point of purchase without having to build a lending business from scratch. Our white-label card gives them that, under their own name.”

Splitit plans to begin shipping its World Mastercard to financial institutions in early 2027.

Splitit was founded in 2012, went public in 2019, and went private again in 2023 after it was acquired by Motive Partners. With an overall goal to simplify flexible payments, the company launched a partner program called the Agentic Commerce Partner Program in 2025. The new initiative allows autonomous shopping agents to make payments using card-linked installments.

The launch marks an interesting evolution for Splitit, which, for 16 years, has focused on enabling installment payments using consumers’ existing credit cards rather than issuing new credit products. Bringing installment functionality directly into a white-label credit card gives mid-sized banks and credit unions a way to compete with standalone BNPL providers without building their own installment infrastructure.

Notably, the approach also allows financial institutions to retain ownership of the customer relationship rather than ceding that engagement to third-party financing providers. This ownership question has become a hot topic lately, especially as consumers have started to turn to AI tools or other third party players to address their financial needs.

Financial Education Platform Zogo Goes Live in Canada

Financial Education Platform Zogo Goes Live in Canada
  • A partnership between BMO Financial Group and financial education platform Zogo will help boost financial literacy among young adults in Canada.
  • The partnership targets young adults between the ages of 18 and 24 and provides practical lessons and quizzes to help users build financial knowledge that will have real-world applications in their lives.
  • Founded in 2018 and headquartered in Austin, Texas, Zogo won Best of Show in its Finovate debut at FinovateFall 2019.

Financial literacy platform Zogo has arrived in Canada.

BMO Financial Group announced this week the launch of Zogo in Canada. The new offering brings Zogo’s interactive, gamified financial literacy experience to eligible students throughout Canada. Designed for young adults aged 18 to 24, the partnership will help them develop their financial knowledge in order to make informed financial decisions throughout their lives.

Zogo features practical lessons and quizzes to help users learn about budgeting, saving, credit, and money management. Through the Zogo mobile app, BMO clients can complete financial lessons, earn points, and redeem rewards while building practical skills they can apply to their everyday lives.

“Bringing this experience to Canada alongside BMO makes this partnership especially meaningful for us,” Zogo President Ben Brooks said. “BMO’s commitment to helping the next generation make financial progress is evident in the care its team has put into this launch. Together, we’re making financial education more accessible, engaging and rewarding for Canadian students, with practical skills they can carry well beyond the classroom.”

BMO’s partnership with Zogo is part of the banking group’s drive to make financial literacy more accessible. BMO recently announced a strategic partnership with MoneyPrep, which provides teachers with free access to financial literacy lessons and tools designed for elementary school-aged children. The first financial institution to bring Zogo to Canada, BMO sees the partnership as an extension of its support for financial literacy across all stages of learning, from the classroom through adulthood.

“Building financial knowledge and confidence early can help establish the foundation for lifelong financial well-being and real financial progress,” said Sumit Sarkar, Head of Everyday Banking Products for BMO. “With Zogo, BMO is making financial education more engaging, accessible, and relevant for young Canadians, empowering them to navigate important financial decisions at every stage of life.”

The eighth-largest bank in North America by assets, BMO Financial Group has total assets of $1.5 trillion as of July 2026. The firm offers a wide range of financial services, including personal and commercial banking, wealth management, and investment banking across Canada, the US, and select international markets. In addition to its partnership with Zogo and MoneyPrep, BMO offers tools and resources for financial education and wellness, including BMO SmartProgress, an online financial education platform; BMO My Financial Progress, a digital goal-planning platform; BMO Insights, a spend-monitoring solution; and BMO Credit Coach, a credit-health management platform.

Zogo won Best of Show in its Finovate debut at FinovateFall 2019 and returned to the Finovate stage two years later for FinovateFall 2021. Founded in 2018 and headquartered in Austin, Texas, Zogo also introduced its Zogo Shorts financial video series earlier this month, designed to make learning about finance fit into users’ everyday routines. The company also announced an integration with Alkami that brings its financial education resources directly into Alkami’s digital banking experience.


Photo by Andre Furtado

nCino Unveils Productivity Suite for Mortgage Loan Officers

nCino Unveils Productivity Suite for Mortgage Loan Officers
  • nCino launched its Loan Officer Productivity Suite, a set of AI-powered and automated tools designed to streamline mortgage origination workflows and improve loan officer productivity.
  • The suite includes six capabilities spanning borrower eligibility checks, underwriting summaries, pre-approvals, disclosures, and connectivity with external AI agents through MCP.
  • The launch focuses on workflow execution, potentially helping mortgage lenders increase loan volume without adding staff.

Agentic AI banking platform nCino unveiled its Loan Officer Productivity Suite today. With the new set of tools, the North Carolina-based company aims to help increase the productivity of mortgage originators by adding automated actions.

Launched inside the nCino Mortgage Solution, the new suite uses each lender’s own data, product guidelines, and workflow rules to give originators answers specific to their institution and let them take action. Among the clients already using the Loan Officer Productivity Suite is Educated Mortgage, which uses it for daily origination workflows; and Security National Financial Corporation, which uses the tool to prepare its loan officers by giving them relevant borrower information.

“We’re excited to equip our loan officers with nCino’s intelligent features so they’ll have more confidence knowing exactly what each file needs to keep moving and can trust that routine tasks and borrower questions are being handled along the way,” said Security National Financial Corporation Vice President and CIO Thayne Atkinson.

The Loan Officer Productivity Suite is launching with six major elements:

  • Mortgage Advisor for Loan Officers: Allows originators to ask questions naturally and receive plain-language answers about their pipeline, individual loan files, and GSE guidelines.
  • Loan PreCheck: Evaluates borrower eligibility against multiple guidelines and recommends the best-fit loan program before the underwriting process takes place.
  • Mortgage MCP for Loan Officers: Allows loan officers to connect their preferred AI agents directly to the nCino Mortgage Suite using an MCP connection.
  • AUS Smart Tasks: Turns underwriting findings into a plain-language summary and surfaces suggested tasks.
  • Automated Pre-approval: Unifies credit authorization, verification services, fee calculations, and dual AUS integrations into a single process.
  • Automated Disclosures: Automates Initial Disclosures and Redisclosures for standard loan templates.

“Loan officers are being asked to handle more work without sacrificing responsiveness to borrowers,” said nCino General Manager of Global Mortgage Casey Williams. “The Loan Officer Productivity Suite helps create that capacity by taking routine work off originators’ plates and putting answers and next steps at their fingertips, so they can stay responsive and competitive without adding more hours to the day.”

Since it was founded in 2012, nCino has shifted from a cloud banking tool provider to providing more agentic-focused tools that help clients execute workflows. Because mortgage originators spend a significant amount of time navigating disconnected systems, reviewing borrower information, and completing administrative tasks, shifting to more automated execution could help increase loan volume without adding staff. Additionally, nCino’s support for MCP opens the door for lenders to use external AI agents to interact with their mortgage technology, which could change how loan officers work with their existing systems.


Photo by RDNE Stock project

Visa Study Finds Consumers Trust AI to Shop, But Not to Pay

Visa Study Finds Consumers Trust AI to Shop, But Not to Pay

Agentic shopping is taking over the headlines, but are consumers really ready to hand over their credit cards to a bot? Visa recently sponsored a report that measures consumers’ attitudes toward agentic commerce.

The research was conducted by The Harris Poll in May of 2026 and surveyed 2,065 US adults to provide insight into how consumers are navigating the next evolution of AI shopping and payments. The report found that 72% of respondents have used an AI assistant, 23% trust generative AI to handle payments on their behalf, and 61% would trust Visa to handle agentic transactions.

The findings from The Harris Poll’s research reveal four key takeaways for the future of agentic commerce:

Payment providers could retain influence even if AI owns the customer interface

Visa’s research suggests that consumers distinguish between the technology that helps them shop and the payment providers they trust to facilitate transactions. So while they may use an AI agent to recommend a new pair of shoes, compare prices, and select a retailer, when it comes time to pay, many still prefer the protections and peace of mind offered when using a familiar, established payment provider.

The implication: Banks and payment networks may not need to own the entire AI shopping experience to remain relevant. Their competitive advantage could depend on providing trusted payment infrastructure that sits behind the shopping experience.

Trust could become a competitive advantage for incumbent banks

As it is still a new concept, much of the conversation around agentic commerce has focused on the enabling technology, such as APIs, tokenization, agent authentication, and payment execution. And for good reason: figuring out the logistics of the payment that leverages a constantly evolving field of technology with multiple players is complicated.

However, Visa’s research suggests that consumer confidence could be just as important as technical capability. This element of consumer trust and confidence creates a lot of opportunity for established financial institutions that may feel locked out of participating in agentic commerce.

The implication: Fortunately for banks and payment providers, they already have relationships with consumers, established fraud protections, and experience in handling disputes. Each of these elements is a differentiator as AI agents begin initiating transactions.

Agentic commerce could reinforce existing payment infrastructure

Stablecoins have been taking over discussions in banking and fintech, as their low-cost, speedy rails have the potential to improve the overall customer experience while driving down costs. Additionally, their programmable, blockchain-based infrastructure could make stablecoins an attractive payment option for certain agentic commerce use cases. However, as Visa’s study implies, if consumers prioritize familiar, trusted payment brands, card networks may have an advantage in the early stages of adoption.

The implication: This prioritization shows that lower transaction costs and technical efficiency may not be big enough reasons for consumers to adopt unfamiliar payment experiences. For fintechs building alternative payment solutions, trust and consumer protections may be just as important as price and convenience.

The opportunity in autonomous transactions is in making transactions feel safe

Agentic commerce is still in its early stages, and we still have a lot to learn when it comes to best practices. However, the findings in Visa’s study imply that successful agentic payments will require clear permissions, spending limits, authentication, and dispute resolution.

The implication: If shoppers do not feel safe in allowing agentic AI to make payments on their behalf, they will continue to shop via traditional ecommerce methods. However, Visa is already developing infrastructure through its Visa Intelligent Commerce initiative that will offer authentication, transaction security, and consumer controls. Consumers may be more willing to embrace agentic commerce when trusted financial services providers establish the necessary safeguards, rather than leaving the experience to a fragmented group of unfamiliar players.


Photo by SiljeAO

Fintech Rundown: A Rapid Review of Weekly News

Fintech Rundown: A Rapid Review of Weekly News

It’s a dual holiday today in the US, with Americans celebrating both Columbus Day and Indigenous Peoples’ Day to start the week. There’s no break in the fintech news flow, though, and Finovate’s Fintech Rundown has you covered. Be sure to check back all week long for the latest updates.


Fraud prevention

Document intelligence specialist Veryfi introduces its Fraud Detection and Prevention Suite.

Payments

New Zealand-based fintech Qippay secures an investment commitment of NZ$5 million from Australia’s All Roads Wholesale Fund.

Egypt’s Bank NXT extends its payments partnership with UAE-based Network International.

Identity document verification and bank card scanning solutions provider OCR Studio and payment infrastructure company FinOn team up to enhance security across onboarding and online payments.

On-Demand Pay specialist DailyPay announces $200 million asset-backed securitization of its On-Demand Pay receivables.

Digital assets

SoFi Tech Solutions, Orbi, and Mastercard announce partnership to launch a crypto-linked card program in Mexico.

Multi-asset trading broker Kudo.com launches instant crypto withdrawals.

Stablecoin payments orchestration service Anyflo emerges from stealth; announces acquisition of bitcoin lending platform Native.

Multi-chain orchestration company Ownera forges strategic partnership with institutional digital asset infrastructure provider Utila.

Lending

Nivo unveils its AI assistant for lending, Lender Collect, which automates case coordination for specialist lenders in the UK.


Photo by Jon Champaigne

Backbase Moves Beyond Banking Chatbots with AI Agents That Take Action

Backbase Moves Beyond Banking Chatbots with AI Agents That Take Action
  • Backbase launched Conversational Banking, an agentic AI solution that allows banks to move beyond answering customer questions to executing banking tasks within predefined permissions and controls.
  • More than 10 banks are already using the solution, with one major South African bank increasing self-service containment from 20% to 70% across 22 million customer interactions.
  • The launch highlights a broader shift toward AI-powered execution in banking, raising questions about whether banks will prioritize cost savings or leverage AI to deliver more personalized customer experiences.

Engagement banking solutions provider Backbase is launching Conversational Banking this week to bring agentic AI into the customer and employee experiences.

The launch comes 18 months after Backbase unveiled its new AI-powered banking platform that sought to improve customer engagement with AI-powered self-service and real-time support. Conversational Banking, which runs on Backbase’s AI-native Banking OS, takes that a step further by allowing the AI agent to actually execute appropriate banking actions on the behalf of consumers and employees, given that they fall within pre-defined permissions, policies, and approvals as set by the bank.

The Conversational Banking tool works alongside existing digital banking stacks and allows customers to use natural language prompts to have their lost payment card blocked and replaced, check a payment, or progress a service request. By leveraging customer context, permissions, and connected banking systems, AI agents can carry out specific, permitted tasks on customers’ behalf. For requests that require further investigation or human judgment, employees can pick up where the agent left off by examining an overview of the work the agent has already completed.

“Digital banking put the bank in the customer’s pocket. The next step is to let customers say what they need done and have the bank’s agents act on it intelligently,” said Backbase Founder and CEO Jouk Pleiter. “That future has now arrived early: one where agents do the work, and banks stay in control. It completely changes both the customer experience and the economics of serving them.”

Backbase anticipates that by allowing AI agents to carry out tasks on behalf of consumers and employees, banks can scale and increase their service capacity. In fact, according to a report by McKinsey & Company, agentic AI could cut banks’ operating costs by 15% to 20%, as the automation frees up employee time for advice, exceptions, and complex needs.

Currently, 10+ banks have already started using Backbase’s new Conversational Banking and have reported positive feedback. One of the four largest South African banks has so far supported 22 million customer interactions, while improving self-service containment from 20% to 70%.

Backbase’s launch shows that banks are beginning to shift from AI-powered tools to AI-powered execution. Chatbots have historically been limited to providing information and directing customers to the appropriate resources. By handing tasks over to agentic AI, banks can automate the steps required to resolve customer requests. This transforms AI from a customer service tool into a functional layer of the banking experience. With its background in compliance, Backbase is in a great position to add reliable governance and permissions into the agentic process, addressing one of the key hurdles preventing banks from putting agentic AI into production.

The bigger question, however, is whether banks will use these agentic capabilities primarily to reduce operating costs or to meaningfully improve the customer experience. Automating routine service requests can certainly improve efficiency, but the longer-term opportunity may lie in using AI to deliver more proactive, personalized banking services.


Photo by Ant Rozetsky on Unsplash

Finovate Global Korea: Payments, Blockchain Networks, and Cybersecurity

Finovate Global Korea: Payments, Blockchain Networks, and Cybersecurity

This week’s edition of Finovate Global showcases recent fintech news from South Korea.


Gwangju Bank and Toss announce stablecoin QR payment PoC

Korea’s Gwangju Bank announced that it had successfully completed proof of concept (PoC) for stablecoin-based QR code payments in partnership with Seoul-based superapp Toss. The PoC linked the Gwangju Bank mobile app, the Toss app, and Toss Place payment terminals. Selecting stablecoin payment in the bank app opens the QR scanner in the Toss app, where the user can scan the QR code displayed on the merchant’s payment terminal to verify the payment amount and complete the transaction.

The demonstrated flow was designed to transfer stablecoins from the customer’s wallet to the merchant’s wallet. The payment result could then be verified in the Gwangju Bank app, completing the app-to-app payment process. The PoC used a virtual merchant, and no actual customer data or assets were involved.

The two entities added that they plan to streamline the process by reducing the number of steps customers must take. The bank and fintech are also discussing a second phase of testing involving actual merchants in the Jeonnam and Gwangju regions.

“The PoC conducted with Toss is significant in that it established a technological foundation to proactively respond to the digital asset payment environment and verified the user experience from a customer perspective,” Gwangju Bank Vice President Byun Mi-Kyung said.

Gwangju Bank is a regional South Korean financial institution and a subsidiary of JB Financial Group. Founded in 1968, the bank reported total assets of approximately KRW 34.4 trillion ($54 billion) at year-end 2025. It operates branches in Gwangju, Jeonnam, Seoul, Incheon, and Seongnam.

Founded in 2015 as a money transfer service, Toss has grown into one of Korea’s leading superapps with 30 million users. Toss offers an ecosystem of more than 100 financial management and e-commerce services, along with more than 10,000 mini apps through its Apps in Toss platform, which runs within the Toss app.


Canton Foundation forges strategic partnership with LG CNS

In a bid to expand institutional adoption of the Canton Network in Korea, the Canton Foundation has announced a strategic partnership with Seoul-based IT services provider and systems integrator LG CNS. Together, the Canton Foundation and LG CNS will develop technical capabilities to support Canton implementation as help build a broader technical partner ecosystem.

“Korea is a critical market for institutional adoption of Canton in Asia,” Canton Foundation Head of APAC Thomas Chou said. “This partnership is about building the market together, combining Canton’s growing institutional ecosystem with LG CNS’s deep technology capabilities and relationships across the Korean financial sector. Together, we aim to help institutions move from identifying opportunities to implementation, while building the broader technical ecosystem needed to support adoption at scale.”

The Canton Network is a public, permissionless blockchain designed specifically for institutional finance, while individual applications can define their own permission requirements. Announced in 2023, the network’s mainnet went live in July 2024. It was designed to balance blockchain transparency with the confidentiality required by regulated financial institutions and markets. Canton operates as a modular blockchain ecosystem in which participating institutions maintain their own ledgers while connecting with others via a shared synchronization layer. Canton’s “network of network” architecture enables real-time secure synchronization and settlement, atomic transactions that ensure that complex exchanges involving multiple parties are completed in full or not at all, and privacy for sensitive financial information.

The partnership between the Canton Foundation and LG CNS will focus on three areas: institutional market development, technical enablement and implementation, and technical partner ecosystem growth. LG CNS has been a major player in Korea’s blockchain-based financial industry since 2015. Beginning with the issuance of blockchain-based electronic securities, the company has built the infrastructure for the issuance, distribution, settlement, and trading of digital assets such as CBDCs, tokenized deposits, security tokens, and stablecoins, as well as digital wallets and KYC systems for financial institutions. LG CNS has also built and operated core systems for major commercial banks, insurers, credit card companies, and securities firms for more than 30 years.

“Financial institutions are increasingly moving from exploring blockchain technology toward practical implementation,” said LG CNS EVP and Head of Digital Business Division Hongkeun Kim. “Through our partnership with Canton Foundation, we look forward to combining LG CNS’s technology and implementation capabilities with the Canton ecosystem to develop meaningful opportunities with institutions in Korea. We also look forward to contributing our experience to the development of a broader technical partner ecosystem that can support institutional adoption over the long term.”

The Canton Foundation is the advocacy and expansion arm of the Canton Network. The organization is dedicated to expanding the network’s reach and promoting broader institutional adoption.


Korea Fintech Industry Association announces new anti-hacking strategy

In response to a series of suspected, AI-assisted cyberattacks and data leaks that struck at least seven major South Korea financial institutions in recent weeks, the Korea Fintech Industry Association brought fintech firms and electronic payment providers together this week to discuss the importance of coordinated data-sharing and early risk checks to enhance their defense against cyberattacks.

Kim Jong-hyun, chairman of the association, said recent cyber incidents should not be viewed as problems affecting individual companies alone, but as threats to public confidence in financial services as a whole. His remarks underscored the need for coordinated information-sharing and greater cooperation with regulators to strengthen security. The chairman also emphasized the importance of building systems that will enable teams to identify risks early and respond proactively.

The discussion also covered the Financial Supervisory Service’s (FSS) IT security self-inspection checklist, which the country’s Financial Services Commission has asked firms to use. The 12-point checklist addresses threat intelligence and blocklists, system abnormality detection, access controls and vulnerabilities, system hardening, and incident investigation.


Here is our look at fintech innovation around the world.

Central and Eastern Europe

  • Czech fintech Dateio secured its biggest contract to date thanks to a partnership with ING.
  • Bulgaria’s Fibank partnered with Bitpanda Enterprise to integrate crypto investing into its My Fibank app.
  • Poland’s mBank introduced BLIK Recurring Payments, the ninth bank in the country to offer the service.

Middle East and Northern Africa

  • Valley National Bank acquired Israeli fintech Bluevine for $340 million.
  • Diebold Nixdorf announced that it will deploy cash recyclers for digital wallet and mobile payments company stc pay Bahrain.
  • US-based money transmitter Viamaericas has added Ethiopia and Morocco to its remittance network.

Central and Southern Asia

  • TBC Uzbekistan launched its first secured lending product for SMEs.
  • India’s Pine Labs introduced a unified payments platform for merchants in Singapore.
  • DK Bank to establish a subsidiary in the UAE, becoming the first Bhutanese bank to expand its financial services offering internationally.

Latin America and the Caribbean

  • Brazilian fintech Asaas raised $55.6 million in new funding to supports its payment, financial management, and credit tools for small businesses.
  • SoFi Tech Solutions (formerly Galileo) teamed up with Orbi and Mastercard to launch a crypto-linked card in Mexico.
  • Latvia’s Regula and Chile’s Bernini.ai announced a partnership to provide ID verification for AI agents.

Asia-Pacific

  • South Korea’s Gwangju Bank and fintech Toss successfully completed a proof of concept involving stablecoin payments using QR codes.
  • Vietnam’s MB Bank partnered with OceanBase to modernize its database infrastructure.
  • The Korea Fintech Industry Association announced new anti-hacking measures in the wake of series of recent cybersecurity incidents involving financial services companies.

Sub-Saharan Africa

  • Pan-African payments aggregator PawaPay secured a Payment Service Provider (PSP) license from the Bank of Mozambique.
  • South Africa’s WalletDoc launched Visa Payment Passkeys for merchants in the country.
  • Pan-African neobank Mukuru introduced its new account and card in South Africa, in partnership with Bank Zero and Mastercard.

Photo by Ayyeee Ayyeee

Intrepid Fox Partners with Topograph to Bring KYB to B2B Onboarding

Intrepid Fox Partners with Topograph to Bring KYB to B2B Onboarding
  • Know Your Business (KYB) platform Intrepid Fox has teamed up with KYB data and public register provider Topograph.
  • The partnership will combine Intrepid Fox’s KYB workflows with live company records from official registers for onboarding and ongoing reviews.
  • Intrepid Fox most recently demoed its technology at FinovateEurope 2025 in London.

UK-based Know Your Business (KYB) platform Intrepid Fox announced a partnership with Topograph, a company that provides the data layer for B2B onboarding. The partnership is designed to close the information gaps that can develop after business customers are initially onboarded and keep databases up to date with information on a company’s status, ownership, address, and more. Intrepid Fox’s AI agents provide updated company information that can be compared with data that is already on file. The agents can determine whether follow-up is required and can create context to support human agents in their investigations.

The goal is to combine detection with action through a structured review that records the evidence, follow-up, and human decision-making. This enables compliance teams to focus on those changes that are most critical instead of having to manually review and refresh every company file.

“Monitoring tells you that something changed. A compliance team still needs to understand what changed, whether it matters to the relationship, and what evidence supports the next step,” Intrepid Fox CEO and Co-founder Roman Zilber said. “Working with Topograph helps us connect that signal to a review where context and human judgement remain visible.”

As vital as KYB processes are, they are only as reliable as the records they start with. By monitoring company records directly from their official registers, Topograph provides updated information that is live and traceable to its source. This approach avoids the problems of stale databases, manual searches, and compliance gaps. The company offers a single API that enables teams building onboarding and KYB flows to get live company data, beneficial ownership information, and official documents, while monitoring their systems for changes—all of which is normalized across markets and traceable back to the source. Headquartered in Paris, Topograph was founded in 2024.

“Compliance decisions are only as good as the data behind them,” Topograph CEO and Co-founder Pierre-Henri Janssens said. “That’s what guides our work at Topograph: we connect to more than 100 official registers ourselves, which lets us monitor company records in real time and trace each data point back to its source. Intrepid Fox builds on that foundation, so compliance teams can work through each change with the full context in front of them.”

Founded in 2024 and headquartered in London, Intrepid Fox made its Finovate debut at FinovateEurope 2024 and returned the following year for FinovateEurope 2025. The company leverages GenAI to power document collection and accelerate business customer onboarding for banks and fintechs. Intrepid Fox’s technology helps reduce follow-ups and the operational burden of KYC, while enriching collected data from online and open sources.

Intrepid Fox’s partnership news comes just a few weeks after the company announced an integration with real-time company data provider Kausate. Like Topograph, Kausate connects platforms directly to official registers to provide real-time access across European jurisdictions.


Photo by Adam Cai on Unsplash

Why Spade’s Oban MacTavish Thinks Banking AI Should Focus on Revenue, Not Cost Cutting

Why Spade’s Oban MacTavish Thinks Banking AI Should Focus on Revenue, Not Cost Cutting

For much of the financial services industry, the conversation around AI has focused on creating efficiencies by automating processes, reducing costs, and replacing manual work. But banks may be overlooking AI’s biggest opportunity. Rather than focusing on what AI can eliminate, financial institutions may find greater value in using the technology to better understand their customers, anticipate their financial needs, and deliver personalized experiences that drive revenue.

In this conversation from FinovateFall 2026 in New York, we speak with Oban MacTavish, Co-Founder and CEO of Spade, about why the industry’s enthusiasm for AI agents may be misplaced and how better transaction data can help banks unlock AI’s potential. MacTavish explains why traditional payment data isn’t built for modern intelligence tools and how financial institutions can use AI to recreate the personalized relationships customers once had with their local bankers, but at scale.

“I think most of their customers are looking for a better experience, and it’s one of the ways that we actually see the biggest opportunity for AI in financial services is helping them turn their data into revenue,” said MacTavish.

MacTavish is Co-Founder and CEO of Spade, a New York-based financial data and AI company he co-founded in 2021. Under his leadership, Spade has expanded its platform to help financial institutions make better use of payments data for fraud prevention, customer engagement, analytics, and AI-powered applications. MacTavish also participated in a fireside chat at FinovateFall 2026 on how AI is changing offers, cross-sell, and personalization.

Founded in 2021, Spade transforms raw transaction data into structured, actionable merchant intelligence. Its platform helps banks, fintechs, and other financial services companies identify merchants, enrich transaction records, and build more personalized financial products and experiences. Spade raised $40 million in Series B funding in March 2026, led by Oak HC/FT, to expand its data and AI capabilities.


Photo by RDNE Stock project