For years, banks have competed for customers by offering attractive interest rates, cash back rewards, and convenient digital experiences. But as consumers gain access to an expanding range of financial services providers, attracting new customers is only part of the challenge. Increasingly, banks must find ways to encourage lasting engagement, build loyalty, and help customers make meaningful progress toward their financial goals.
One approach is to connect everyday banking products with incentives that reward positive financial behaviors. Rather than treating lending, checking, and savings as separate relationships, financial institutions have an opportunity to bring these services together to help customers manage debt, build savings, and strengthen their financial health. The result can be a more valuable banking relationship for both the institution and the customer.
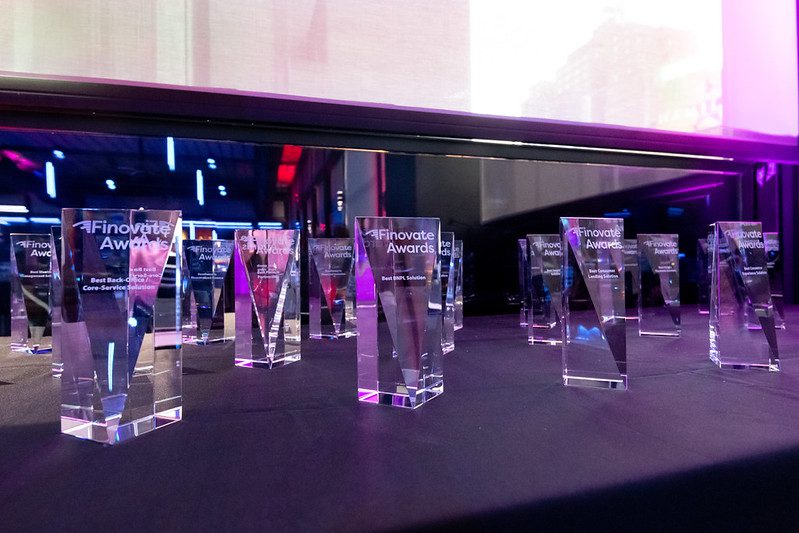
To learn more about this approach, we spoke with Mark Elliot, Chief Customer Officer at Happen Bank, formerly LendingClub Bank. The company, which serves more than five million members, offers a suite of interconnected lending, checking, savings, and financial wellness products designed to help consumers make progress toward their financial goals. Happen Bank won the Best Customer Experience Solution category at the 2026 Finovate Awards.
Congratulations on winning the Best Customer Experience Solution category at the 2026 Finovate Awards. What does this recognition mean for Happen Bank, and what do you think ultimately set your application apart?
Mark Elliot: Thank you! We’re proud of this recognition because it reflects how we build our customer experiences—clearing the way for people going places. That only works when the experience holds up in the moments that matter, like taking steps to manage debt, taking out a personal loan for a purchase that can’t wait, or building savings.
What I think set our application apart was the connection between our products and the needs they address for our members. Someone may come to us for a personal loan to consolidate credit card debt. LevelUp Checking rewards their eligible on-time Happen Bank personal loan payments with an opportunity to earn 2% cash back and offers 1% cash back on everyday essentials. DebtIQ, our free financial wellness tool, gives them a way to understand, monitor, and manage their debt in one place. And LevelUp Savings offers a competitive LevelUp Rate (10 times the national average) for members who deposit $250 or more each month, encouraging them to build a consistent savings habit and a cushion for future large expenses.
Taken together, our products give members reasons to develop strong positive financial habits and stay with us as their financial needs evolve.
Tell us about the problem you set out to solve. What was missing from the market, and how did that shape your approach?
Elliot: We focus on consumers we call the Motivated Middle: high-FICO, high-income, digitally savvy consumers actively managing their financial lives. They’re looking for smart, simple, easy-to-use, and easy-to-understand products that deliver real value—and they’re not finding those products in traditional banking.
We designed our product set from the ground up specifically for them. We brought lending, checking, savings, and a powerful debt management tool into a unified, engaging mobile experience. We designed a set of products that are great in their own right but work even better when used together—for instance, offering cash back for on-time Happen Bank loan payments made through a LevelUp Checking account.
And throughout, we built in rewards tied to smart financial behaviors—for example, offering a higher APY to those contributing at least $250 to their LevelUp Savings account each month. The goal was to make it easier for members to manage today’s obligations while building toward what comes next.
What have you learned from bringing Happen Bank to market? Are there particular results, customer outcomes, or milestones that demonstrate its impact?
Elliot: The biggest lesson is that clear, achievable rewards can give members a reason to build a habit and keep using a product.
LevelUp Savings has more than 80,000 accounts and more than $4 billion in deposits. About 70% of account holders meet the $250 monthly deposit requirement to earn the LevelUp Rate, and those members visit our platform about 30% more often than customers using our previous savings product.
LevelUp Checking has generated six times the account openings of the product it replaced, with 60% of new accounts coming from existing members. Of the members we surveyed, 84% said the cash back incentive makes them more likely to consider us for their next personal loan.
One of the results highlighted in our award entry is particularly meaningful. Borrowers with a LevelUp Savings account build an average savings balance of approximately $19,000 after they have paid off their loan—an amount roughly equal to the amount of credit card debt they came to us to consolidate.
That’s the kind of progress we want to support: helping members gain control over their high-cost credit card debt and then building a financial cushion to meet future goals.
Looking at the broader banking landscape, what is changing most significantly right now, and how is that influencing your strategy?
Elliot: Customers have more banking options than ever, and they expect a clear reason to choose one over another. A competitive rate or cash back offer can attract attention, but the ongoing experience has to make the relationship worth keeping.
Can members understand what they’re earning and paying? Can they manage debt and savings without piecing everything together themselves? Those are practical questions that shape loyalty.
For us, that means designing products around connected needs and making the value easy to understand. It also means using technology to improve the service behind those products.
What’s next for Happen Bank? What should we expect to see from you over the next 12 to 18 months?
Elliot: We’ll continue building on our LevelUp ecosystem, and we’ll release more features through DebtIQ, using member feedback to improve how those products work together.
Home improvement lending is another area of focus, where we’re working with partners to make financing projects simpler for homeowners. We’re also exploring home equity lending, which is a natural fit because top use cases for home equity loans are home improvement and debt consolidation, two businesses we’re already in today.
Across those efforts, the question is the same: where can we make a financial decision easier or help a member take the next step?
As we mark our 20th year, the Happen Bank name reflects how much our relationship with our more than five million members has evolved. Many people first know us through a personal loan. We’re earning a broader role in their financial lives by continuing to deliver value as they pay down debt, build savings, and plan for what comes next.