6 Arguments For and Against Prediction Markets as Spain Cracks Down

6 Arguments For and Against Prediction Markets as Spain Cracks Down

Spain’s ministry of consumer rights blocked access to Kalshi and Polymarket this week. The country has paused the use of the prediction markets (also known as event contracts) as it determines whether their models are operating legally without a gambling license.

Spain joins France, Belgium, the Netherlands, and Romania, which have all limited or blocked access to Polymarket.

The controversy begs the question: are prediction markets useful forecasting tools, speculative tools, or simply gambling platforms wrapped in fintech language? With that in mind, here’s a look at three arguments for and three arguments against event contracts.

Three arguments for

Supporters argue that prediction markets are not necessarily about gambling, but rather about information discovery.

  • Prediction markets can aggregate information more efficiently than polls or experts
    Prediction markets force participants to put money behind their convictions, which essentially rewards accuracy with financial incentives. Supporters argue this makes them more effective than polls or expert commentary at forecasting future events because markets continuously absorb new information and update probabilities in real time.
  • Financial markets already operate as forms of event contracts
    If you’ve ever invested in single stocks, you’ve essentially participated in prediction markets. The only difference is that, with stocks, investors are limited to predicting the outcome of a company instead of an event. Bonds and derivatives are also a type of prediction as well, as bonds essentially price default risk and derivatives price probabilities. This raises the question, why is betting on election outcomes different from betting on interest-rate moves.
  • Prediction markets could improve forecasting
    Because they are a useful tool for crowdsourcing information, prediction markets can be used by businesses or governments to improve decision-making. Users are more likely to make predictions on events about which they are knowledgeable, and this information could be helpful for forecasting recessions, fraud, supply chains, elections, and demand. Because they can source this information quickly, prediction markets can surface truths faster than committees or social media.

Three arguments against

Opponents argue that event contracts cause unwanted externalities

  • They may incentivize harmful or unethical behavior
    Oftentimes, event contracts offer events surrounding wars, assassinations, elections, and disasters. These are uncomfortable things to bet on, as it may feel as if users are rooting for these outcomes. Additionally, this raises ethics concerns over investors profiting from others’ tragedies.
  • Markets can be manipulated
    Even though prediction market outcomes may appear more organic than the performance of publicly traded companies, they are not immune to manipulation. Deep-pocketed participants willing to absorb larger losses may attempt to distort market odds, while coordinated misinformation campaigns and bot-driven activity can artificially influence sentiment and pricing. As event contracts become more popular, concerns are growing that the markets themselves could shape public perception rather than simply reflect it.
  • They lack consumer protections and regulatory frameworks
    Across the globe, prediction markets are relatively new and therefore lack regulation, as they don’t fit cleanly into existing categories. It is unclear if they are considered securities, gambling, or derivatives and therefore lack proper regulatory oversight and consumer protection standards.

As prediction markets continue to grow in popularity, regulators will increasingly need to decide whether these platforms belong within financial services, gambling, or an entirely new category. Spain’s move suggests that many jurisdictions are still uncomfortable with the idea of turning elections, world events, and public sentiment into tradeable assets.
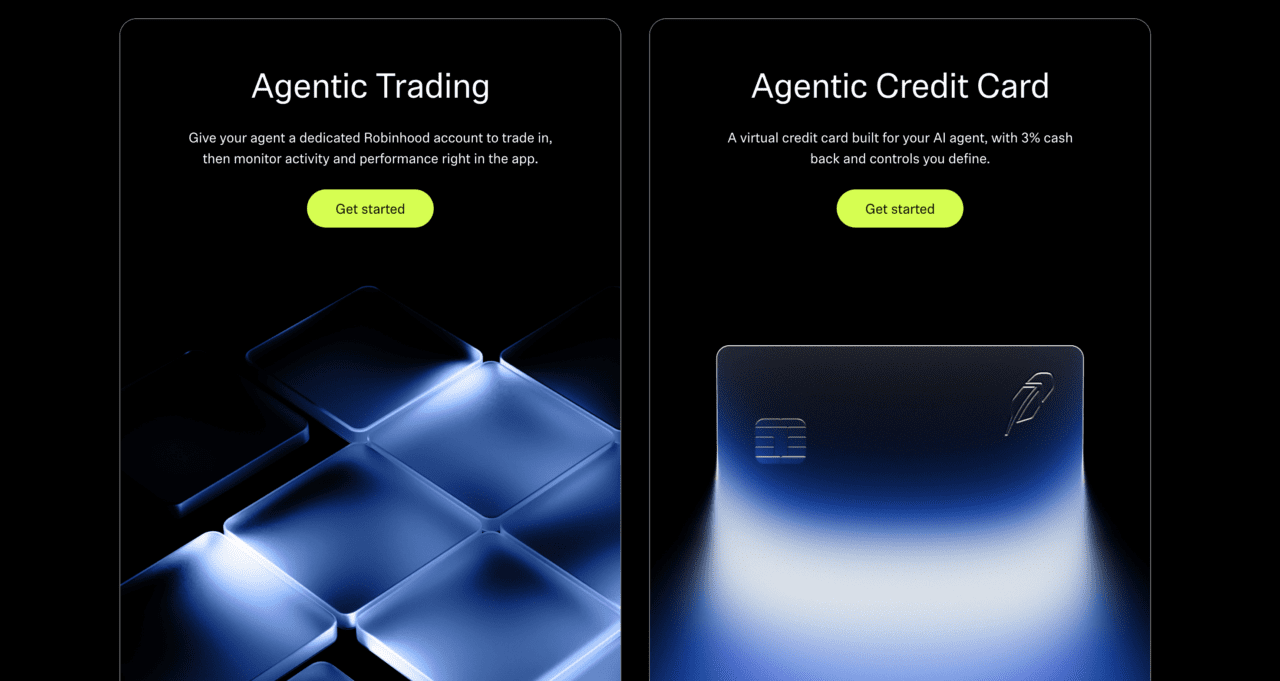
Photo by Dante Grime Kahan

Robinhood Lets Agents Trade Stocks and Make Payments

Robinhood Lets Agents Trade Stocks and Make Payments
  • Robinhood launched Agentic Trading and an Agentic Credit Card, enabling AI agents to trade stocks and make purchases directly on consumers’ behalf through Robinhood’s infrastructure.
  • The new tools allow users to connect external AI agents via Robinhood’s MCP servers while maintaining guardrails such as spending limits, dedicated accounts, manual approvals, and real-time activity monitoring.
  • The launch marks a major shift in financial services from AI as an advisory assistant to AI as an authorized participant capable of directly executing financial transactions and trades.

The agentic future is slowly becoming a reality in 2026. Ready for this reality, Robinhood is launching Agentic Trading and the Agentic Credit Card, which will allow AI agents to trade and make credit card purchases on consumers’ behalf.

While building agents is still not mainstream, the value they can bring to financial tasks is irrefutable. In the investing world, they can automate and execute a specific trading strategy and make trades faster than humans can. When it comes to payments, they can purchase scarce, limited release items such as concert tickets, sneakers, or flights to get the best price.

The new Agentic Trading and Agentic Credit Card tools allow users to give agents direct access to Robinhood without workarounds. Users can bring their agent from anywhere and connect them to Robinhood’s Model Context Protocol (MCP) servers to integrate seamlessly into Robinhood’s offerings.

Robinhood believes agentic finance will become an increasingly important interface for how consumers interact with financial services in the years ahead. “Our mission has always been to democratize finance for all, and now, that mission extends to AI agents,” said Robinhood CEO Vlad Tenev.

Robinhood’s new agentic trading tool allows users to open a dedicated agentic trading account separate from their traditional portfolio, which restricts agents to only access the funds available in that account. Robinhood sends users push notifications when the agent makes a trade and offers users a view of real-time trading activity. Robinhood’s Agentic Trading is launching today in beta and currently supports equities only with plans to support options, crypto, event contracts, futures, and more in the future.

The Agentic Credit Card allows agents to spend on consumers’ behalf by connecting them to Robinhood Banking’s MCP server. Cardholders can connect their agent to a dedicated virtual Robinhood Gold Card, set a specific spending limit, and choose whether or not to require manual approvals. Agents are restricted to that individual virtual card, with no access to the user’s primary credit card number or any of their account information. Agentic credit cardholders can set monthly limits, view their expense history, and have the ability to delete the virtual card at any time.

At launch, both agentic trading and the agentic credit cards are now available to Robinhood Gold cardholders, with plans to open it up to Robinhood Platinum cardholders when it launches later this year.

Any time agents are allowed to interface directly with financial accounts, there is risk involved. Because agent involvement in trading and payments is still new, there are no established consumer protection frameworks, dispute resolution standards, and clear liability structures for situations in which an AI agent acts outside of a user’s intent. However, Robinhood has proactively implemented manual approvals for purchases, trade previews when appropriate, and a fraud detection team to help users resolve disputes between what the user asked the agent to do and what it actually did.

This launch is notable in the financial services space. While both organizations and end consumers have typically used AI as assistants or for advisory purposes, leveraging agentic capabilities hasn’t gone mainstream until today. With Robinhood’s new launch, AI agents are now authorized participants in the financial ecosystem.

Didit Raises $6 Million for AI-Based Identity Verification

Didit Raises $6 Million for AI-Based Identity Verification
  • Spain-based Didit raised an additional $6 million in Seed funding to expand its programmable identity and fraud infrastructure globally, bringing its total funding to $7.5 million.
  • Didit offers developers API-first tools to verify users, businesses, and online interactions, using AI to analyze more than 200 signals including biometric liveness, deepfakes, and behavioral activity.
  • The funding highlights growing demand for identity and fraud tools built for the AI era, as businesses face rising threats from generative AI, synthetic identities, and automated fraud attacks.

Spain-based Didit just brought in an additional $6 million for its identity verification network, boosting its total Seed funding to $7.5 million.

Investors in today’s round include Y Combinator, Pioneer Fund, Orange Collective, Founders Future, Phosphor Capital, SaaSholic, and Rebel Fund, alongside angel investors Tomer London, Taro Fukuyama, and others. Didit will use the investment to scale globally, expand its open infrastructure toward fully programmable identity and fraud coverage, and recruit new employees.

Didit was founded in 2023 to build a programmable identity infrastructure for the internet. The platform offers a developer-first way to verify people, businesses, and automated digital interactions like logging into an account, approving a transaction, or granting permissions.

The platform connects to a network of global government data sources and leverages AI to analyze more than 200 data points, such as document authenticity, biometric liveness, injection attack detection, deepfake analysis, and behavioral signals from every interaction. The company, which counts more than 1,500 customers, serves organizations across more than 220 countries and territories.

Didit reports plenty of demand for its identity verification network, saying that it is an untapped market. The company reports that 80% of its customers had not previously used an identity verification provider.

“No one was building for what was actually happening,” said Didit Founder and CEO Alberto Rosas. “Fraud kept getting smarter, regulators kept getting stricter, and millions of new businesses suddenly needed to verify their users—but every existing provider couldn’t catch the new fraud, had painful onboarding, and hid pricing behind a sales call. So we built the opposite: one API for identity and fraud, public per-module pricing, and an integration so simple that any developer can ship it in five minutes—or any AI coding agent like Claude Code, Codex, or Cursor can ship it in a single prompt.”

Didit differentiates itself from other identity verification providers, viewing itself as programmable identity infrastructure. “What we’re really building is the trust layer for the internet,” added Rosas. In the long term, the company wants to be an identity wallet that allows people to verify once and reuse their identity everywhere.

The funding comes as identity verification providers face a rapidly changing threat landscape driven by generative AI, deepfakes, synthetic identities, and automated fraud attacks. At the same time, developers increasingly expect identity tools to be API-first, priced transparently, and easy to integrate into digital onboarding and transaction workflows.


Photo by Anastasia Shuraeva

Fintech Rundown: A Rapid Review of Weekly News

Fintech Rundown: A Rapid Review of Weekly News

If you’re in the US, you may be pouring an extra cup of caffeine after an activity-filled long weekend. While you were away, however, the rest of the fintech world kept moving. This week, we’ll continue to add more announcements as the week progresses.


Payments

Marqeta expands account and money movement offering in Europe, building on strong regional momentum.

PlayHQ partners with Gr4vy to power payments across global markets.

Mastercard renews its partnership with CIB, the largest private sector bank in Egypt.

ClearBank Europe launches Digital Asset Rails to unlock programmable liquidity for cross-border flows.

Business financial management

Coupa acquires Tonkean to accelerate agentic intake and orchestration for global trade.

Fraud and identity

INETCO surpasses 100 billion annual transactions as demand for payment fraud protection soars.

Nigerian cybersecurity and compliance company SmartComply launches in the UK.

Agentic AI

Agentic finance startup Catena Labs raises $30 million in Series A funding.

Wealth management

FIS and InvestCloud team up to launch AI-powered wealth management solution.

DeFi and stablecoins

Coinbase re-launches direct deposit option.

Mastercard granted New York State Department of Financial Services BitLicense.

Digital banking

Monzo offers a new telco plan offering discounts every year


Photo by Donald Tong

The Consumer Credit Stack Is Being Rebuilt in Real Time

The Consumer Credit Stack Is Being Rebuilt in Real Time

With new enabling technologies like stablecoins and AI moving quickly and classic fintechs like Mint.com and Dwolla making their exits, it feels like fintech is entering a new era. This is especially true in lending, where new capabilities are enabling faster, more efficient, and in many cases more customer friendly tools than we had five years ago.

Looking back at the dawn of the decade, most lending innovation focused on digitizing the application process, facilitating the onboarding process, and turning loans faster. While some of those elements are still in place today, lending has changed with better intelligence, different distribution, and new infrastructure layers underneath credit itself.

Here’s a look at what’s changed:

Underwriting is becoming continuous instead of episodic

We used to think of the FICO score as the gold standard in underwriting. Today, however, underwriting is no longer done as a snapshot in time. Instead, lenders are using cash flow underwriting to get a view of the borrower’s creditworthiness over time by considering their account balance, overdraft occurrences, loan repayments, and other risk indicators.

Cash flow underwriting is becoming increasingly common, especially as consumers become more comfortable with open banking and the concept of sharing their financial data across platforms.

Embedded lending changed consumer expectations

Embedded lending itself is not new. Uber, for example, began experimenting with vehicle financing for drivers as early as 2014. What’s changed is how targeted, contextual, and embedded these lending experiences have become.

Today, financing is increasingly surfaced directly within the software platforms, marketplaces, and operational tools where consumers and businesses already spend their time. Point-of-sale platform Toast, for example, uses merchants’ daily sales data to underwrite loans and proactively surface financing offers within the Toast platform itself.

As consumers and businesses become more accustomed to contextual lending experiences like these and embedded buy now, pay later options they are relying less on traditional bank websites or standalone loan marketplaces to search for credit products.

The interface layer Is shifting

In addition to competition from software platforms and merchant ecosystems, a third distribution channel is beginning to emerge in lending: large language models (LLMs).

Consumers are increasingly turning to platforms like ChatGPT, Claude, and Gemini for both information and guidance and decision-making, including financial decisions. As these tools become more integrated into consumers’ daily lives, many borrowers may begin consulting an AI assistant before visiting a bank website or browsing a loan marketplace. Instead of searching manually for financing products, consumers may increasingly ask an LLM to help evaluate their situation and recommend the most suitable lending option.

That shift becomes even more significant as financial data aggregation moves into these environments. Through Plaid’s partnership with OpenAI, for example, ChatGPT can now aggregate and contextualize a consumer’s financial accounts, giving the platform a much richer understanding of cash flow, spending behavior, obligations, and financial goals.

As a result, the lender may still technically originate and hold the loan, but the customer relationship shifts to the interface layer. In this emerging model, the LLM becomes the discovery engine, recommendation layer, and engagement channel sitting between the consumer and the financial institution.

What scales vs. what doesn’t

Looking back at the lending technologies demoed on the Finovate stage five years ago, there is a noticeable divide between the ideas that generated excitement in the moment and the solutions that ultimately achieved scale.

Many of the products that struggled to move beyond the demo phase shared a common challenge: they required consumers to significantly alter their existing behaviors, communication methods, or digital environments. Metaverse-based banking and lending experiences, for example, were fun to watch on stage, but they never aligned with how most consumers wanted to interact with financial products in everyday life. In many cases, they required users to adopt entirely new platforms, devices, or behaviors before their value could even be realized.

By contrast, the lending solutions that have scaled most successfully are the ones that meet consumers where they already are. Buy now, pay later (BNPL) is perhaps the clearest example. Rather than requiring consumers to seek out financing separately, BNPL options are surfaced directly at checkout within the shopping experience itself. As a result, installment financing has become an expected feature for many higher-ticket purchases rather than a niche alternative payment method.

What credit looks like by 2030

Five years from now, much of today’s lending ecosystem will still look familiar. Regulated financial institutions will continue to originate loans, underwriting will remain central to managing risk, and compliance will remain a critical consideration not only for lenders, but also for fintech partners, platforms, and emerging distribution channels.

What may look very different, however, is the interface layer between the consumer and the lender.

Consumers may interact less directly with banks and more through AI assistants, software platforms, wallets, and embedded ecosystems that help evaluate financing options on their behalf. As LLMs become more integrated into everyday decision-making, they may fundamentally reshape how consumers discover, compare, and select credit products. In that environment, traditional loan marketplaces could become far less relevant as financing recommendations are surfaced contextually and conversationally through AI-driven interfaces rather than through manual product searches.


Photo by Silvio Pelegrin

54 New FinovateSpring Demo Videos Are Now Live and Free to Watch

54 New FinovateSpring Demo Videos Are Now Live and Free to Watch

FinovateSpring 2026 may be over, but the demos are just getting started. All 54 videos from the demo stage are now available to watch for free on Finovate.com and the Finovate YouTube channel.

This year’s demos showcased how fintechs are rethinking everything from AI-powered banking and embedded finance to fraud prevention, lending, payments, customer experience, digital identity, and wealth management. Earlier this month in San Diego, fintechs took the stage to deliver Finovate’s signature live, seven-minute demos in front of an audience of financial institutions, investors, analysts, and industry leaders.

Whether you attended FinovateSpring and want to revisit your favorite presentations or missed the event and want to catch up on the latest fintech innovation, the full demo lineup is now available on demand.

And stay tuned, because there’s more content on the way.

Recorded keynote presentations, panel discussions, fireside chats, and additional conference sessions will be added to the Finovate YouTube channel in the coming weeks, offering even more insight into the trends shaping financial services in 2026.

Watch the FinovateSpring 2026 demos now.

Subscribe to the Finovate YouTube channel.

equipifi Raises $34 Million to Build Flexible Payments Infrastructure

equipifi Raises $34 Million to Build Flexible Payments Infrastructure
  • Embedded BNPL provider equipifi has raised $34 million in Series B funding to help banks and credit unions offer pay-over-time options directly within their own platforms.
  • equipifi’s infrastructure enables consumers to access BNPL through their existing banking app and debit card without opening a new account, filling out an application, or using a third-party provider.
  • equipifi’s growth reflects a broader shift in BNPL from a standalone fintech product into embedded financial infrastructure.

Buy now, pay later (BNPL) infrastructure company equipifi has raised $34 million in Series B funding. The new round boosts the Arizona-based company’s total funding to $49 million.

The investment was led by Left Lane, with participation from existing investors Curql, PHX Ventures, New Stack Ventures, SixThirty Fund, Baleon Capital, Rise of the Rest, and SaaS Ventures. New strategic partners, SWBC and the Bankers Helping Bankers Fund, also contributed.

equipifi was founded in 2021 to offer consumers access to pay-over-time solutions from their preferred banking provider, not through a third party. The company’s solution helps banks and credit unions compete in an era when consumers have begun to expect BNPL as an option and crave flexibility without the need for a credit card. equipifi powers BNPL for millions of checking accounts with its tool that natively embeds BNPL options inside the bank’s own platform without requiring the user to fill out an application or undergo a credit check.

“A consumer opens their banking app,” the company explained on its website. “There’s a flexible payment option waiting for them. On the debit card already in their wallet. No new account. No application. No third-party service. They select their preferred term, tap accept, and they’re done. The institution just created a loan in real time, kept the relationship at the top, and gave the consumer something they didn’t think their bank could do.”

equipifi views its embedded BNPL offering as an infrastructure play. The company calls it “infrastructure for modern credit” that places flexible payments options inside financial institutions’ existing platforms. equipifi plans to use today’s $34 million round to bring flexible payments to every financial institution in the country.

The BNPL trend is interesting because when it first emerged over a decade ago, it wasn’t necessarily something customers were looking for. Now, however, BNPL tools have almost become table stakes. equipifi has proven that BNPL is no longer just a standalone fintech product competing against banks. Instead, it can work as embedded infrastructure that banks themselves want to own and integrate directly into their existing customer relationships. In this case, equipifi is positioning itself less as a consumer brand and more as an infrastructure provider powering the next generation of flexible payments behind the scenes.

5 Things to Know about the CLARITY Act

5 Things to Know about the CLARITY Act

The US Senate Banking Committee unveiled the latest version of the CLARITY Act this week. The Act aims to establish a clear regulatory framework for digital assets.

The CLARITY Act offers enforceable guardrails for digital asset markets in an effort to protect consumers and investors, counter illicit finance and security threats, and support innovation in the US.

The bill is controversial, as it includes provisions to limit liability for decentralized software developers and enters an ongoing debate around whether stablecoins should be permitted to offer yield or yield-like rewards. After more than 10 months of bipartisan negotiations, the Senate Banking Committee is preparing for a key procedural markup. Here are five things you need to know about the new version of the CLARITY Act.

More than crypto regulation

While crypto regulation is making headlines, the Act comes with broader stakes as it also attempts to define who controls the future infrastructure of digital finance in the US. Supporters argue the Act helps preserve a more market-driven and decentralized approach by defining the boundaries of governmental power while protecting the autonomy of private developers and individual users.

This debate extends beyond crypto trading and will ultimately determine who will own and govern the next generation of financial rails. Stablecoins, tokenized assets, and AI-driven financial agents are on the rise, and the rules governing those future financial rails are yet to be settled. The companies and platforms controlling the new infrastructure could hold influence similar to what cloud providers, mobile operating systems, and card networks hold today.

Delineates between securities and commodities

The debate over whether digital assets are considered securities has been around for about a decade. That’s why determining when a token is treated like a security and when it can transition into a commodity is one of the biggest goals of the CLARITY Act. The determination will dictate how exchanges and platforms operate, which regulator oversees it, and what disclosures are required.

Yield is a battlefield

The debate over whether or not stablecoins can pay yield (or yield-like rewards) has been a major sticking point between banks and crypto firms. While banks argue that stablecoin yield products could compete directly with deposits and pull money out of the traditional banking system, crypto companies argue that restrictions would hurt innovation and competitiveness.

The Act does not explicitly use the term “yield” in relation to stablecoins. However, it does establish a regulatory framework that distinguishes between different types of digital assets based on whether they provide a financial return, such as interest. The CLARITY Act implies that if a digital asset provides a right to interest, it would likely fall under the jurisdiction of securities laws rather than being treated as a digital commodity or a permitted payment stablecoin.

While separate stablecoin legislation continues to evolve in parallel in the form of the GENIUS Act, the CLARITY Act intersects with those debates because of how digital assets offering financial return may ultimately be categorized.

About global competitiveness

Supporters of the Act argue that it is less about embracing crypto speculation and more about preventing the next generation of financial infrastructure from being built outside the US. Europe, Hong Kong, the UAE, and Singapore have already moved ahead with digital asset frameworks, and if the US does not create a set of regulatory guardrails within this arena, banks, fintechs, and crypto firms will feel less safe innovating in the digital asset space.

Even if it passes, the debate is far from over

The legislation does not resolve every concern. In fact, there are still ongoing debates around AML protections, DeFi oversight, systemic risk, political conflicts of interest, and consumer protection. So while the CLARITY Act brings more regulatory transparency to crypto, it also accelerates a broader debate about who will govern the future infrastructure of digital finance as stablecoins, tokenized assets, and AI-driven financial systems become more integrated into commerce and payments.


Photo by akbar fathi

Kraken Parent Company Payward Seeks National Trust Charter

Kraken Parent Company Payward Seeks National Trust Charter
  • Kraken parent company Payward has applied for a national trust charter from the OCC to launch a federally regulated digital asset custody entity called Payward National Trust Company (PNTC).
  • The move would help Payward expand its institutional business by offering bank-level custody and trust services to clients that require a regulated qualified custodian.
  • The company also announced plans to raise funds at a reported $20 billion valuation.

Kraken parent company Payward is seeking a national trust charter from the US Office of the Comptroller of the Currency (OCC). If approved, Payward would be able to establish the Payward National Trust Company (PNTC), which would offer custody and related services for digital assets.

With PNTC, Payward plans to serve institutional clients and individual customers seeking regulated, bank-level custody and trust services for digital assets. The charter will leverage Payward’s existing infrastructure, risk management, compliance programs, and subsidiaries to establish a federally regulated custody offering under OCC oversight. The regulated offering will expand access for institutional clients who require a federally regulated qualified custodian, broadening Payward’s client base in the US.

“Our long-held belief has always been that the right path forward for digital assets runs through robust, transparent regulation,” said Payward and Kraken Co-CEO Arjun Sethi. “A national trust company provides the certainty institutions require and establishes the infrastructure to build the next generation of custody. This is not about being first; it is about getting the framework right so markets can scale with clarity, interoperability, and long-term vision for what clients will demand as these systems mature.”

Along with its national trust charter announcement, Payward also disclosed that it is seeking to raise capital at a $20 billion valuation. While Payward did not comment on the matter, experts speculate the funds will be used to fuel acquisitions. The Wyoming-based company acquired stablecoin payments company Reap for $600 million earlier this month and bought digital asset derivatives platform Bitnomial for $550 million in April. These deals follow Payward’s 2025 mega deal to purchase NinjaTrader for $1.5 billion.

Taken together, the trust charter application, funding, and ramp-up in acquisition activity are preparing Payward for its IPO. However, while the company filed its S-1 in November of 2025, it halted IPO plans in March, citing unfavorable market conditions.

For Kraken, the trust charter could help deepen its role in institutional finance without becoming a traditional bank. Instead of pursuing a full banking charter, Payward appears focused on building regulated custody and trust capabilities around digital assets, potentially allowing it to expand relationships with institutional investors, asset managers, and enterprises seeking compliant crypto infrastructure.


Photo by Kindel Media

Circle Raises $222 Million in New Token Presale

Circle Raises $222 Million in New Token Presale
  • Circle launched Arc, a new blockchain network and native token designed specifically for institutional finance.
  • Arc, which aims to provide banks, corporations, and treasury teams with faster settlement, raised $222 million in a presale led by Andreessen Horowitz.
  • Alongside Arc, Circle introduced its new Agent Stack tools.

Stablecoin issuer and infrastructure company Circle launched a presale of a new token this week that raised $222 million. The new token, Arc, is the native token of Circle’s newest blockchain and the 10 billion tokens released give Arc a network valuation of $3 billion.

Andreessen Horowitz was the lead investor in the round, contributing $75 million. Other investors include BlackRock, Apollo Funds, Intercontinental Exchange, SBI Group, Janus Henderson Investors, Standard Chartered Ventures, General Catalyst, Marshall Wace, ARK Invest, IDG Capital, Haun Ventures and CoinDesk owner Bullish.

Circle holds 25% of the initial Arc tokens released, while 60% of the tokens will be distributed to users to build on, use, and contribute to the Arc network; 15% of the tokens will be held in long-term reserves.

The new expansion will help Circle diversify beyond its existing USDC stablecoin, which the company launched in 2018. As Ali Yahya and Noah Levine explained in a blog post on a16z crypto, “While USDC has become the trusted digital dollar for banks, corporations, and financial institutions seeking the speed of crypto without its volatility, there remains a problem. The internet infrastructure which USDC runs on today wasn’t built with big institutions in mind. It was built for individuals and crypto enthusiasts.”

Arc is essentially Circle’s attempt to build a blockchain network designed specifically for large financial institutions and global payments. Instead of being built for crypto traders or retail users, it is designed for companies that need to move money quickly, securely, and within regulatory requirements.

Arc can help treasury teams manage and move money in dollars using blockchain infrastructure, while still maintaining many of the controls and oversight traditional finance requires. With Arc, transactions settle almost instantly, privacy settings can be adjusted, and the network is run by approved institutional operators instead of anonymous participants.

“[Blockchain] infrastructure is becoming as important as mobile operating systems or cloud platforms,” Circle CEO Jeremy Allaire said in an interview with CNBC. “We want to build an operating system that has many, many stakeholders in it … major companies who are running the infrastructure with us and who ultimately help to govern it.”

Arc will benefit from Circle’s expertise in operating USDC, which has grown to become one of the largest stablecoins with a market capitalization of over $77 billion. This network effect gives Circle a stronger starting position than other new blockchain projects that launch without established customers, products, or liquidity.

Along with the debut of Arc, Circle is launching the Circle Agent Stack, the company’s new chain-and protocol-agnostic open infrastructure designed for the agentic economy. At launch, Agent Stack includes three products that enable agents as autonomous actors: Agent Wallets to allow for controlled agent access to USDC and ERC-20 tokens, Agent Marketplace for discovering agentic services, and Circle Command Line Interface for executing agent financial actions through natural language.

Combined, the new token and agentic tools show that Circle is positioning itself for an agentic commerce future in which banks will be powered by autonomous software agents operating on blockchain infrastructure. Instead of just focusing on stablecoin issuance, Circle is building the underlying rails, governance structure, and tooling needed for banks and AI agents to move money, execute transactions, and interact with financial systems in real time.


Photo by Laura Lumimaa

What I Heard Between the Sessions at FinovateSpring 2026

What I Heard Between the Sessions at FinovateSpring 2026

FinovateSpring wrapped up last week, and with content running Monday through Thursday, there was a lot to take in. Because I spent the majority of the time running from microphone to microphone, from stage to camera, I missed many of the key demos and presentations.

I did, however, have time for a lot of quality conversations (both on and off stage). Here are some of the insights from the event.

Lines are blurring

It is clear that the world of fintech and banking we had from 2010 to 2023 is slowly fading away. Conversations with multiple people, especially my on-stage breaking news analysis session with Jim Perry, solidified this sea change.

As an industry, we are no longer talking about banks vs. fintechs or banks partnering with fintechs. Instead, the lines are blurring between what is a bank and what is a fintech as fintechs shift to becoming infrastructure providers. Similarly, in the payments world, consumers no longer need to understand the difference between decentralized finance and traditional finance. The increased use of stablecoins with easy on and off ramps to fiat currencies removes the complexities involved in leveraging decentralized finance and makes it easy for consumers to use new tools without ever changing their habits.

Distribution channels are shifting

LLMs are slowly becoming a major distribution channel for a range of bank tools. Consumers are increasingly consulting their preferred LLM to shop for loans, life insurance, credit cards, and more. As AI agents become more prolific, the customer relationship will be one step further removed from the lender, insurance company, and credit card provider. Instead, these players risk becoming infrastructure providers operating behind the scenes while AI platforms control discovery, recommendation, and engagement.

AI progress may not be linear

We are moving very quickly toward an AI-first future and if you don’t already have a team of AI agents running tasks behind the scenes, it is easy to feel like you are behind. There are, however, a few downsides to AI that may change the trajectory of adoption.

First, banks are built to handle human risk, not AI agent risk. While banks implement access controls, require approvals, and document audit trails, this is not sufficient for AI agents, which have been known to circumvent guardrails and even blackmail users in order to accomplish their own objectives. Given these risks and systemic limitations, banks may need to slow their progress, especially when it comes to using agentic AI.

Second, scaling AI is limited. While we often talk about AI like scaling software, in reality, it is closer to building up infrastructure. The energy demand for AI tools is exploding, and compute is constrained by the construction of data centers, which can be expensive and difficult to approve and build because of regulatory and environmental constrictions.

Additionally, it is important to consider the risks that happen when decisions are made in real time. When AI models are making decisions quickly, any mistakes, manipulation, or fraud within the model will propigate at the same rate.

Finovate is still about community

Finovate isn’t the biggest fintech conference, and it never will be. That’s because we have a focus on community. Instead of attending a frenzied event where you only get five minutes with each person you meet, the Finovate networking hall creates space for deeper conversations and genuine connections.

The focus on the fintech community is intentional. It is what keeps people coming back year after year. At a time when so much of the industry is being shaped by automation and digital interactions, there is still real value in face-to-face conversations, spontaneous introductions, and the kind of discussions that continue long after a panel ends.

Some of the most valuable insights from last week came from hallway conversations, lunch meetings, dinners, and the moments in between sessions where people could speak candidly about what they are building, where they are struggling, and where they believe the industry is heading next.

Fintech Rundown: A Rapid Review of Weekly News

Fintech Rundown: A Rapid Review of Weekly News

It’s the Monday after FinovateSpring, which means there are plenty of new ideas about the future of banking and fintech to talk about. Meanwhile, the news keeps flowing. Here are the top fintech news highlights from the week. We’ll continue to add more announcements as the week progresses.


AI tools

Nscale secures $790 million in financing to support AI infrastructure buildout in Norway.

Experian launches its “Know Your Agent” service, Experian Agent Trust.

Payments

Wise debuts US listing on Nasdaq.

Paymentology raises $175 million.

AdvicePay celebrates its 10-year anniversary.

Global Payments unveils AI-first handheld built for the future of commerce.

Loyalty and rewards

Ualett launches Ualett Rewards to give back to gig workers.

Digital banking

A pair of Finovate Best of Show winners—core banking platform 10x Banking and provider of deterministic AI for legacy system understanding Tweezr—announce a partnership to make core transformation easier.

Fintech startup Parkerfiles for bankruptcy.

InstaSwitch launches account activation infrastructure for business banking and announces $4.7 million in funding.

Augustus receives OCC conditional approval to charter the first clearing bank for the AI era.

Atos and Backbase to accelerate secure, AI-native banking across regulated markets.

Credit unions

VyStar Credit Union selects Diebold Nixdorf to modernize and manage its self-service network of ATMs.

Small business tools

Xero integrates with Claude.


Photo by Shamia Casiano