This site is operated by a business or businesses owned by Informa PLC and all copyright resides with them. Informa PLC's registered office is 5 Howick Place, London SW1P 1WG. Registered in England and Wales. Number 8860726.
Finovate Blog
Tracking fintech, banking & financial services innovations since 1994
It’s the last week of February, which means we have one more month to wrap up any Q1 goals. Below, we’ve aggregated the top news in fintech for the week. We’ll continue to add more announcements as the week progresses.
This article is brought to you in collaboration with Gregory.
AI is rapidly reshaping the competitive landscape in banking, and for many institutions, the real challenge lies not in experimentation, but in implementation. Richard Davies, CEO of Allica Bank, has been focused on exactly that: how to successfully deploy AI across an organization and drive meaningful adoption at scale.
Founded in 2020, Allica is a digital bank focused on established small and medium-sized businesses. To date, it has lent over £3 billion and been twice named by Deloitte as the UK’s fastest growing technology company. In 2025 the Financial Times identified it as the second fastest growing company in Europe.
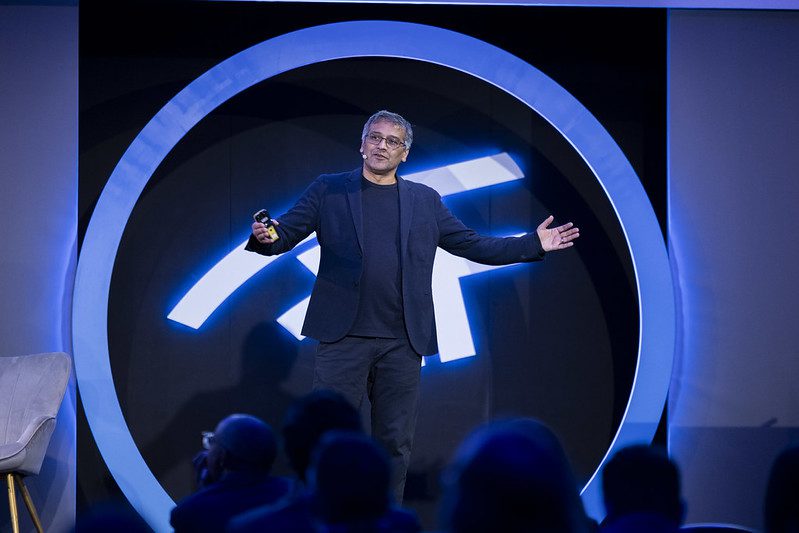
Richard delivered a fascinating keynote address at FinovateEurope, titled: “Successfully Implementing AI & Scaling Adoption: What Are the Challenges Around Rolling Out to Production?”. Afterwards, we sat down with him to talk about what it really takes to embed AI into a bank’s operating model.
Tell us a little more about your role as CEO of Allica Bank and what you’re focused on at the moment?
Richard Davies: Allica is a fintech bank focused on established small and medium-sized businesses. We typically define that as businesses with five or more employees or at least £500,000 in revenue. So we’re not talking about the very smallest microbusinesses, but those that are at a point where things start to get more complex and there are multiple staff to support.
We find these businesses fall into a gap between the corporate banking divisions and retail banking divisions of the major banks. That’s the space we focus on.
We have been building Allica for five or six years now and provide a full stack of services, including current accounts, cards and all types of lending. Increasingly, we are moving into financial operations areas such as spend management and cash flow forecasting. Alongside that, we have been thinking hard about how we can apply AI to power many elements of what we do across the organisation.
In your keynote, you spoke about successfully implementing AI and scaling adoption. What do you see as the biggest challenges for banks when it comes to rolling AI out in practice?
Davies: I would group it into three main areas:
First, ensuring that AI adoption happens across the whole company, rather than sitting in an innovation lab or small specialist team. A big focus for us has been getting people bought in, upskilled and confident, and encouraging teams to create their own simple, agentic use cases. I am a big believer that bottom-up adoption tends to win over purely top-down mandates.
Second is software engineering and product development. Around a third of our staff are in engineering, and that is probably the area that has seen the greatest progress in AI tooling. We have focused on helping people move towards more T shaped or full stack roles, and ensuring our tech stack is AI enabled to unlock significant productivity gains. Depending on what you measure, we are seeing productivity improvements of two to ten times.
Finally, there are more complex agentic use cases. We have specialized teams working on these, and we have been learning a lot over the past two years about what it takes to get them live in production. It’s exciting because beyond engineering, you start solving real world problems that consume a lot of human time and can be inconsistent when done manually.
A lot of banks are investing in AI at the moment. How should they decide where it makes the most sense to focus first?
Davies: My view is that you should not overly narrow your focus. If you pick two areas, you are neglecting ten others, and those areas will fall behind.
Perhaps I have the luxury of leading a fintech organization that is naturally inclined towards this, but I think AI needs to be embraced across the company. Where you do need focus is on infrastructure, including data quality, enabling access to different AI models and ensuring that is done company wide.
If I had to pick one area with immediate and certain benefit, it would be engineering. The productivity unlock in software development is huge. If teams are still working in traditional ways, they need to move quickly, not just for the company’s benefit, but for their own careers. The industry is shifting rapidly, and people need the skills and experience to keep up.
Beyond the technology itself, what changes do banks need to make internally for AI to really become part of how they operate?
Davies: Culture is a big part of it. People need to lean into it. You need the infrastructure in place, as well as training and upskilling so people feel confident using AI.
At the same time, organizations need to remain risk aware. Different AI use cases carry different risks, and teams need to understand those.
In many ways, it’s similar to previous organizational transformations, such as moving from traditional waterfall practices to agile. The enablers are not conceptually different, but it does require deliberate leadership and a clear view of how you enable the organization to change.
From what you’ve seen at FinovateEurope so far, what themes or conversations around AI in banking have stood out to you the most?
Davies: Some of the most interesting conversations have been happening off stage. Recently, we have seen software company valuations come under pressure following major AI model releases, with the view that people can now build their own software more easily.
At the same time, traditional banks have re-rated quite significantly over the past year. In the UK, share prices are up roughly 80 percent. It creates an interesting dynamic.
Fintech has at times in the past been viewed by investors as a poor relation to software, but in reality, building a fintech is much harder than building a pure software company. You have complex regulatory requirements and balance sheet considerations that software firms do not.
It feels like there may be a shift happening in the relative valuation of where companies with real assets versus asset light software companies. For many fintechs, particularly those with strong fundamentals, that could ultimately be a net positive.
FinovateEurope 2026 wrapped up last week, but the fintech conversations are still flowing across social media. The two-day event was packed with meaningful conversations, fast-paced demos, a reunion of familiar faces, and new connections.
And while speakers and attendees were busy talking and learning about all things fintech and banking, Finovate’s photographer was capturing the event in more than 1,000 photos.
The photos are broken down into three categories, and we’ve pulled in a few photos as well as highlights to help summarize FinovateEurope via pictures. If you’re looking for a full content summary, check out our event summary blog post.
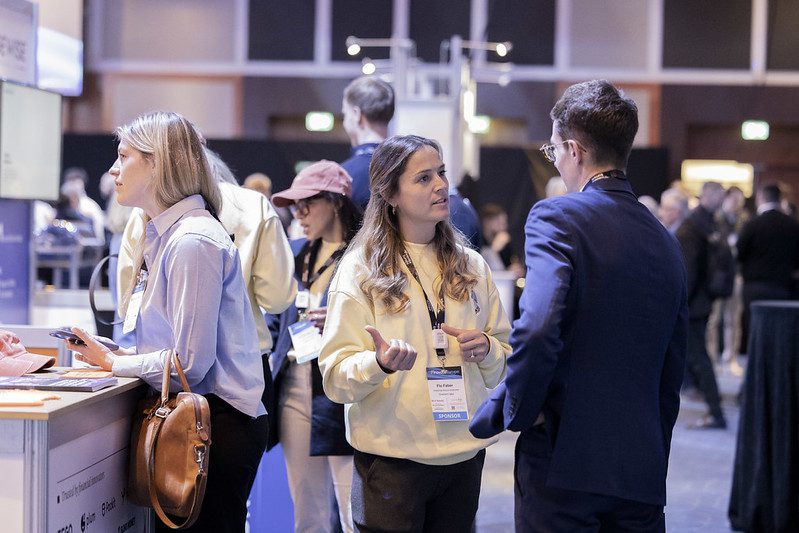
Some of the best discussions happen off stage. And with almost a dozen networking sessions baked into the event, there were a lot of valuable ideas exchanged in the hallways and on the networking floor. Heightening this experience were a live caricaturist and, even though fintech has a magic of its own, a magician.
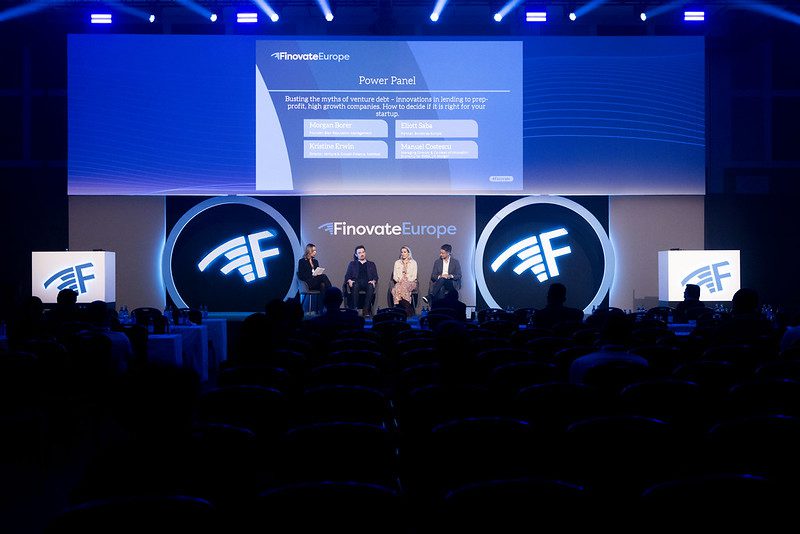
Between panel discussions, fireside chats, and keynote presentations, the FinovateEurope stage hosted some of the brightest minds in fintech (and I’m not just saying that because I was on stage). We heard from founders on their biggest challenges, venture capitalists on the state of funding as we move into 2026, and bankers on how they actually measure the value of AI pilots.
The more than 20 companies that demoed their newest technology on stage showcased some of the most cutting edge ideas in fintech. From identity verification to core modernization, banks and fintechs face a lot of challenges. These fintechs took the stage to show their newest technology in under seven minutes.
If you attended FinovateEurope in London last week, you may have noticed that the energy of the event felt different.
In previous years, the conversation leaned heavily toward experimentation. This year, it shifted toward execution. Across the demo stage, panel sessions, and hallway conversations, it was clear that fintech is maturing. And that maturity is reshaping how banks create, partner, and serve customers.
AI moves from experimentation to operationalization
Agentic AI dominated the agenda in a pragmatic way that eschewed hype for reality.
Speakers discussed the importance of governed agentic AI that protect users with guardrails, auditability, and human oversight. Among these protective barriers, trust, explainability, and regulatory alignment were highlighted as central design principles when implementing agentic AI tools. It is clear that the conversation has shifted from “Can AI agents work?” to “How do we deploy them safely inside regulated institutions?”
Fraud and identity also pulsed throughout conversations about AI, as new technologies are evolving these elements from singular checks to continuous behavioral intelligence. The topics of responsible AI and the impact of AI on the future workforce were also front and center, with standing-room-only crowds on the AI stage discussing governance, skill atrophy, and ethical deployment.
As one attendee said, “When it comes to AI, speed may win attention, but trust wins the relationship.”
Customer experience: from product-centric to embedded
In the Analyst All-Stars session, much of the conversation centered on customer-centricity. Banks are moving from product-centric models to embedded, predictive, and contextual financial experiences.
In my panel discussions on embedded and challenger banking, we explored how digital lending is moving closer to the customer as part of the journey. Executing embedded lending is about being present at the moment of need in the correct channel.
Other panel discussions and keynotes offered more insights around improving the customer experience:
Customers compare bank journeys to every digital experience they have.
Onboarding remains a major friction point.
Personalization and channel choice are now expectations.
Balancing compliance, risk, and conversion requires smarter orchestration.
Challenger banks continue to influence customer expectations, especially when it comes to how they think about brand and community. Many conversations along these lines considered the benefits of collaboration. In fact, over 70% of fintech product launches now involve strategic partners, and panels on platform banking reinforced that partnerships are structurally necessary to compete.
Payments, tokenization, and agentic commerce
Many of the payments discussions highlighted the fact that instant payments are becoming mainstream, but geography and behavior matter. By increasing the speed of payments, fraud also accelerates. This shift is pushing institutions toward implementing “friendly friction,” with biometrics and AI-powered detection.
While not highlighted quite as much, the topic of agentic commerce was brought up in the payments track. If (or when?) bots become customers, banks must rethink identity verification and value-chain control. With ISO 20022 becoming the common language for blockchain-based value exchange, tokenization and programmable money will become key pieces of infrastructure.
Capital is maturing
Most of the investors on the networking floor and up on stage agreed that fintech funding rebounded globally in 2025. Today, capital efficiency and unit economics have returned to the center of strategy. To keep up, founders are tightening business models and refining their distribution strategies. Additionally, panelists mentioned that community-backed capital structures, which add accountability, are increasingly being used alongside traditional venture funding.
Beyond the stage
The Women in Fintech panel was one of the most popular sessions. The overflowing crowd was a reminder that inclusion plays a role in organizational growth. Geopolitical risk, national security strategy, and regulatory shifts also underscored the fact that financial services innovation does not happen in isolation.
Thanks to all of our speakers who braved the stage to share their insights, and to everyone who attended. You all make up such a great community and we truly could not do this without you all!
As banks digitize their lending processes and seek to expand credit access across borders, it is becoming increasingly difficult to make fast, accurate credit decisions. To mitigate risk, lenders need real-time insights into spending habits, automated functionality, and visibility into a broader set of data, especially as they seek to improve speed, enhance the customer experience, and maintain compliance.
At FinovateEurope 2026, a new group of fintechs will showcase how they are addressing these challenges by bringing intelligence and automation directly into the lending process. From sourcing alternative credit data to deploying AI-driven lending agents, the companies below are helping banks and lenders modernize credit decisioning while keeping risk in check.
FinovateEurope 2026 will take place at London’s InterContinental O2 on February 10 and 11. Tickets are available now. Visit our FinovateEurope hub today and save your spot!
Intuitech brings live AI agents into lending workflows to automate manual, time-consuming processes across origination and servicing. The company helps lenders streamline tasks including data collection, validation, and borrower interactions. This automation helps reduce operational burden while improving speed and consistency.
By embedding AI agents directly into clients’ lending operations, Intuitech enables them to scale their lending activity without requiring additional talent in-house. The automated approach helps bring modern credit delivery to lenders of all sizes.
Mifundo’s technology enables customers to assess cross-border credit risk by sourcing and standardizing credit data from across European markets. The company helps lenders better evaluate borrowers with international financial histories by assess creditworthiness for mobile, expatriate, and cross-border customers. Mifundo enables banks to reach more borrowers, as many are underserved by traditional credit systems and therefore are overlooked.
With remote work becoming more popular and the potential for cross-border lending increasing, firms are realizing that there is a gap in data for European credit markets. Mifundo closes this gap by expanding access to reliable credit information, ultimately helping lenders minimize risk while unlocking new lending opportunities across borders.
sea.dev provides real-time risk insights designed to help lending teams make better credit decisions across the loan lifecycle. The company’s platform aggregates and analyzes borrower, portfolio, and market-level data to offer lenders clearer visibility into risk exposure, ultimately supporting faster approvals.
sea.dev enables lending teams to continuously monitor risk and adapt decisions as inputs change. The company’s more dynamic, insight-driven approach helps lenders explore more products and serve new borrower segments.
Why banks should care
With more consumer data available than ever before, lenders can now underwrite loans more effectively, especially for customers who were once considered risky or had limited credit histories. This abundance of data also introduces new challenges, including inaccurate, unclean, or cross-border information that can complicate analysis and require specialized expertise. Fortunately, new tools are emerging to help automate data collection, filtering, and validation. These tools have the potential to enable lenders of all sizes to expand their reach and better serve a broader customer base.
The countdown is on! FinovateEurope 2026 lands in London on February 10 through 11 at the InterContinental O2 in London, and the global fintech community is gearing up for one of the year’s most engaging events.
The two-day conference will feature more than 1,000 senior decision-makers, including bankers, investors, founders, and fintech leaders as they uncover what’s next in fintech and banking. You’ll see over 20 live demos of cutting-edge technology with 100+ expert speakers offering insights that go well beyond buzzwords.
If you already have your ticket (if you don’t, there’s still time to register), here’s how to make the most of your days on-site:
Download the ConnectMe app and create your profile to start networking, set your schedule, and view the agenda.
The invitation-only Leaders+ and Impact+ sessions begin on February 9 at 6:00 pm.
Registration and networking begins at 8:15 am on February 10 and the day concludes with the Best of Show announcement during the evening cocktail reception, which starts at 4:30 pm.
Breakfast and networking begins at 8:15 am on February 11 and the day concludes with the Investor All Stars panel, which wraps up at 4:30 pm.
Bring your badge each day. You’ll need it for entry!
Plan your travel time to the venue, especially if you’re commuting or taking public transport.
Dress code? Business casual to business formal. Be comfortable, but ready to make an impression.
Need help? Stop by the registration desk or find a Finovate team member for assistance.
Follow #FinovateEurope on LinkedIn and Twitter for live updates and key takeaways.
Whether your goal is to track early fintech trends, forge new partnerships, or benchmark your strategy against peers, FinovateEurope delivers. With elite networking, live product insights, and industry-shaping conversations all under one roof, this conference promises to kick off 2026 with fresh ideas and real momentum.
Varo raised $123.9 million in a Series G round led by Warburg Pincus and Coliseum Capital.
The bank will use the investment to scale its chartered banking and lending platform.
Alice Milligan, former chief marketing officer at Morgan Stanley, and Kevin Watters, former division chief executive officer at JPMorgan, have joined Varo’s Board of Directors.
Digital challenger bank Varolanded $123.9 million in financing this week. The Series G round, which boosts Varo’s total funding to $1.1 billion, was led by existing investor Warburg Pincus and new investor Coliseum Capital Management. Also contributing to today’s investment are existing investors such as Northview.
For new investor Coliseum Capital Management, the appeal lies in Varo’s ability to use its charter to compete with incumbent banks while expanding its product depth. “We are thrilled to join Warburg Pincus as long-term, collaborative partners, and support Varo’s work to expand its customer value proposition and to further differentiate from traditional banks,” said Coliseum Capital Management co-founder and Managing Partner Chris Shackelton. “We believe Varo is building a resilient and scalable platform from which to capitalize on a significant market share opportunity.”
Varo was founded in 2017 and secured a bank charter three years later. The fintech’s banking platform brings digital-first bank tools, from money management to lending, credit building, and savings accounts and tools. Varo offers two lending products, Varo Advance and Varo Line of Credit, which together generated $547 million in volume last year. The bank’s lending tools are powered by the company’s machine learning models that supplement traditional credit data, allowing the bank to lend to non-traditional borrowers.
As part of today’s announcement, Varo disclosed that Alice Milligan, former chief marketing officer at Morgan Stanley, and Kevin Watters, former division chief executive officer at JPMorgan, have joined its Board of Directors.
From a governance and operating perspective, Varo’s board sees the company’s combination of regulated banking discipline and modern technology as a key differentiator in a crowded challenger market. “Varo has built something rare: a technology-first customer experience paired with the governance and risk discipline required of a nationally chartered bank,” said Varo Bank Board of Directors Alice Milligan and Kevin Watters. Watters reports that Varo will use today’s funds to support the company’s next phase of growth by scaling its lending and banking platform.
“This combination of new capital, Coliseum’s partnership, and experienced banking leaders joining our board, is propelling Varo into its next phase of growth,” said Varo Bank CEO Gavin Michael. “We remain focused on operating with discipline and delivering meaningful impact for our customers.”
US-based Varo is one of the few true challenger banks that operate with their own bank charter, a structural advantage that gives it direct control over deposits, lending, customers, and unit economics. But a charter alone does not guarantee scale. Varo is still small when compared to competitors such as Chime, which operates under a sponsor banking model and has tens of millions of users. And while SoFi is Varo’s closest chartered competitor, the gap between the two is widening. SoFi recently reported record Q4 2025 results, including $1 billion in net revenue, $174 million in net income, and one million new members added in a single quarter.
As bank charters increasingly become table stakes in the challenger banking field, Varo will need to focus on scaling by differentiating its offerings and channels to reach new markets, especially as international players like Nubank, which just received regulatory approval to operate in the US, bring their customer-winning strategies to the US.
Welcome to the first week of February! Both FinovateEurope and Valentine’s Day are just around the corner, and there’s lots to love about this week’s fintech news headlines. Below, we’ve aggregated the top news in fintech for the week. We’ll continue to add more announcements as the week progresses.
Verisavelaunches credit card processing fee optimization program for professional services firms.
NCR Atleos and Heart of England Co-operative extend relationship to enhance financial inclusion.
STAR Financial Bank partners with CorServ to meet demand for enhanced commercial credit cards.
dLocalpartners with DHL Express Brazil to automate Pix payments and accelerate parcel release.
Wealth management
UK-based Novum Investment Managementsecures investment form UK local government pension fund to launch and scale Doris, a new offering to help transition people from saving to investing.
NymCardenables stablecoin settlement with Visa in the Gulf Cooperation Council (GCC) region including countries such as Saudi Arabia, the UAE, and Oman.
Credit, data, and analytics
Analytics software firm FICOforges global partnership with technology consulting and digital solutions provider Tech Mahindra to help companies integrate AI-powered decisioning and advanced analytics.
Payoneer is expanding local collection capabilities across Indonesia and in the Mexican Peso.
The investments aim to scale infrastructure and capabilities that support Payoneer’s global payments and commerce ambitions.
With nearly 2 million customers, Payoneer aims to offer further improved local access and cross-border payment efficiency through 2026.
Global payments company Payoneer made moves to help companies doing business in Indonesia and Mexico this week. The New York-based company expanded its global payment platform in Indonesia and enhanced local collection services in Mexico.
The new capabilities aim to help customers transact and receive funds from local buyers and ecommerce platforms. Payoneer anticipates its platform will facilitate the funds faster and at a lower cost, ultimately helping businesses tap into new, global markets.
In Indonesia, Payoneer will help small businesses collect funds from local businesses. The company aims to offer more control over foreign exchange management while providing increased access to a trade in the largest ecommerce market in Southeast Asia.
For global businesses looking to collect funds in the Mexican Peso, Payoneer has expanded its collection services in that currency. With the expansion, the company is aiming to reduce friction for global sellers who need to collect funds across multiple channels, supporting shifting international demand.
“Global trade is dynamic—reshaping in response to macro factors and trade policy,” said Payoneer SVP of Treasury and Payment Services Derek Green. “For over 20 years, Payoneer has supported and enabled our customers’ global ambitions. By expanding our capabilities in critical markets like Mexico and Indonesia, we continue to empower our customers as they look to expand into fast-growing markets, leveraging our ecommerce marketplace ecosystem to enable access to customer demand on Amazon Mexico, Walmart, Mercado Libre, and Shopee.”
Payoneer was founded in 2005 to help SMBs transact, do business, and grow globally. The company’s global financial stack helps remove barriers and simplify cross-border commerce to make it easier for businesses to connect to the global economy, pay, get paid, manage their funds across multiple currencies, and grow their businesses.
The new capabilities launched this week add to Payoneer’s existing local collection infrastructure across North America, Europe, Latin America, and Asia Pacific.
In today’s announcement, Payoneer disclosed that it plans to expand local collection capabilities in other high-growth markets in Latin America and Asia Pacific later this year to support its almost 2 million customers.
Nubank has received conditional approval from the US OCC to form a national bank, marking a major regulatory milestone as it begins the setup phase for entering the US market.
Unlike past challenger bank attempts, Nubank enters the US from a position of strength, with more than 127 million customers, strong engagement, and $783 million in quarterly net income.
Regulators require Nubank to fully fund the bank within 12 months and begin operations within 18 months.
Brazil-based digital bank Nubank (also known as Nu) just achieved a long-standing goal. The fintech received conditional approval from the US OCC for the formation of a de novo national bank, Nubank, N.A.
Announcing the approval, Nu Founder and CEO David Vélez framed the move as a strategic validation of the company’s long-held belief in digital-first banking. “This approval isn’t just an expansion of our operation; it’s an opportunity to prove our thesis that a digital-first, customer-centric model is the future of financial services globally,” said Vélez. “While we remain fully focused on our core markets in Brazil, Mexico, and Colombia, this step allows us to build the next generation of banking in the United States.”
The conditional approval, granted about four months after Nu initially submitted its application, places the company in the early setup stage of forming a US national bank. During this period, Nu must meet a series of requirements set by the OCC and secure additional approvals from the FDIC and the Federal Reserve. Regulators also require the company to fully fund the bank within 12 months and begin operations within 18 months.
After Nu receives full regulatory approval for a national bank charter, it will operate under a comprehensive federal framework that allows it to launch deposit accounts, credit cards, lending, and digital asset custody. Nu plans to establish strategic hubs in Miami, San Francisco, Northern Virginia, and the North Carolina Research Triangle.
Cristina Junqueira, Nu’s co-founder and CEO of its emerging US business, highlighted the regulatory milestone as a step toward establishing credibility and competitiveness in a crowded market. “Receiving federal approval for a national bank charter is a significant step in our journey to becoming a solid, compliant, and competitive regulated institution in the US,” said Junqueira. “We look forward to delivering the transparent, efficient financial experiences already trusted by more than 127 million customers around the world to our future customers in the US.”
Founded in 2013, Nu has operated in its home country of Brazil as a fully regulated financial institution since 2016 and announced that it plans to obtain its full banking license this year. The fintech also operates in Colombia and has an expansion plan in Mexico, where it is waiting on approval from the Comisión Nacional Bancaria y de Valores to organize as a banking institution.
While international expansion efforts have been slow, the company’s customer acquisition growth has not. With more than 127 million customers, Nu is known throughout fintech for its high customer engagement level, reaching an activity rate exceeding 83%. In the third quarter of last year, the fintech reached a record revenue of $4.2 billion, which represents a 39% year-over-year growth.
It’s important to note that Nu’s entrance into the US market will likely succeed where other challenger banks have failed. Monzo, N26, and Bunq have all tried and failed to secure a US license from the OCC, while Revolut still does not have a US banking license, either. The difference is that Nu is massively profitable with relatively low customer costs. The company reported $783 million in net income in the last quarter alone.
For Nu, which caters to a largely Hispanic customer base, the US is full of opportunity. There are more than 65 million Hispanics living in the US, many of whom are left out of traditional banks in the US due to high fees, limited access to credit, and legacy onboarding models that fail to reflect their financial realities. Nu’s success in Latin America has been built on designing for inclusion at scale. The fintech boasts transparent pricing, an intuitive digital experience, and unique underwriting. Bringing this successful model to the US while navigating one of the world’s most demanding regulatory environments, would be a huge win for Nu, and perhaps could serve as a model for other overseas challengers seeking to launch in the US.
As FinovateEurope returns to London on February 10 and 11, the spotlight on the second day of the conference shifts from demos to deep discussion. On February 11, FinovateEurope’s Industry Stages run in parallel with one another, giving attendees the opportunity to dive into strategic conversations shaping financial services in 2026.
This year’s event features five Industry Stages: Artificial Intelligence; Banking, Regulation & Risk; Customer Experience; Lending; and Payments. Each stage is designed to offer banking and fintech leaders more than just theory. The sessions focus on what’s working in practice, what’s breaking under the pressure of new technology and regulations, and what institutions need to rethink about their current operations.
Artificial Intelligence: from pilots to production
The AI stage will feature discussions on one of the biggest challenges facing financial institutions today: moving beyond experimentation. The sessions will explore lessons learned from early AI agent pilots, governance frameworks to combat “shadow AI”, and how banks can scale AI responsibly. Highlights include a keynote from Richard Davies, CEO of Allica Bank, who will speak about the realities of implementing AI in production. The stage will also host panels tackling ROI, data readiness, and responsible AI as a competitive necessity.
Customer Experience: personalization without losing the human touch
On the Customer Experience stage, the conversation moves past buzzwords to focus on execution. Sessions will examine how open data enables hyper-personalization, why mindset can be the biggest challenge, and how banks can retain empathy while scaling. A standout power panel brings together leaders from J.P. Morgan, Invesco, and PolyAI to explore what banks can learn from other industries as customer expectations are being reset by the evolution of enabling technologies.
Payments: instant, intelligent, and under threat
Payments are quickly evolving across the globe, especially with new regulations such as PSD3 and new capabilities and enabling technologies such as instant payments, stablecoins, and cross-border modernization. Panels will focus on how data-centricity and AI can unlock growth while strengthening security, especially as fraud losses and cyber threats keep rising.
Banking, regulation & risk: resilience in a volatile world
Regulatory pressure and operational resilience will be the center of the conversation on this stage, where discussions will span DORA, dispute management, and the risks embedded in cloud and AI adoption. These sessions are especially relevant for banks navigating complex vendor ecosystems while being asked to do more, faster, and with greater accountability.
Lending: capturing the embedded opportunity
The Lending stage will look at how banks can reclaim growth by meeting unmet needs, especially in small business and embedded lending. Panelists will explore how AI is reshaping credit decisioning, how regulation is evolving, and where incumbents can realistically compete with fintech challengers.
Together, these five Industry Stages on February 11 will offer a concentrated look at the decisions that will define banking’s next chapter. If you register for FinovateEurope before January 30, you can still save £300.
ThetaRay has launched Ray, an Agentic AI investigation suite designed to help banks automate and standardize transaction monitoring investigations amid rising alert volumes and regulatory scrutiny.
The platform targets growing regulatory demands from frameworks such as the EU’s AMLR and FinCEN’s AML/CFT directives by delivering faster, more consistent, and audit-ready investigations with traceable, explainable AI.
Ray helps firms create compliance-critical workflows and scale AML operations without relying on manual processes or increasing headcount.
Financial crime detection company ThetaRay has launched a new set of tools to help firms keep up with evolving regulations in the face of advanced fraud. Called Ray, the new Agentic AI investigation suite aims to help banks conduct transaction monitoring investigations.
Ray is embedded into ThetaRay’s Investigation Center, an Agentic investigation suite designed for banks, fintechs, and payments platforms balancing high alert volumes with rising regulatory demands. Ray combines autonomous investigations with on-demand analyst support. The fintech anticipates Ray will ultimately help banks reduce the time it takes to resolve cases and create more consistency in investigations that span internal teams and jurisdictions. ThetaRay created Ray toautonomously handle the full investigation by validating the geolocation, analyzing patterns, and scanning adverse media to prepare a structured, audit-ready case-file document.
The launch is strategic and comes at a time when regulators across the globe are raising their expectations for investigative quality and documentation. The EU’s new Anti-Money Laundering Regulation (AMLR) and AML Authority framework require stronger due diligence, more rigorous monitoring and record-keeping, and consistent compliance controls across jurisdictions. In the US, FinCEN’s AML and Counter Financing of Terrorism (CFT) directives require transparent, evidence-based investigations and Suspicious Activity Report (SAR) narratives.
“This is an incredibly important moment for us and for the industry,” said ThetaRay CEO Brad Levy. “I couldn’t be more energized by the opportunity to tackle one of the biggest challenges in financial crime compliance. Our mission is simple: to help make global markets more modern and secure for all. The future will be shaped by people who care and by megatechs and specialized fintechs working closely together to raise the bar for transparency, accountability, and lasting trust.”
However, as regulators require higher investigative quality, documentation, and more defensible decisions, alert volumes continue to rise and place a strain on investigation teams, requiring manual data gathering.
“Financial institutions are moving beyond experimentation toward real, production-grade use of Agentic AI in compliance-critical environments,” saidMicrosoft Global Head of AI Strategy and GTM for Payments and Banking Tyler Pichach. “Platforms like Ray demonstrate how Agentic AI, when deployed on a secure and governed cloud like Microsoft Azure, can help banks modernize complex investigation workflows while meeting regulatory expectations for transparency, control, and trust.”
With Ray, firms can prepare for this increased strain by using it to automate evidence collection, behavioral and counterparty analysis, open-source checks, and document review and narrative generation. Built and deployed on Microsoft Azure, Ray offers an on-demand AI assistant that supports questions from analysts and deeper exploration.
“Manual investigations inevitably vary from analyst to analyst. Ray introduces a consistent reasoning framework across the entire operation, reducing subjectivity, and ensuring that each case, no matter who handles it, stands up to scrutiny,” said ThetaRay Regulatory Affairs Manager David Shapiro. “Most importantly, Ray was built so that every decision is traceable back to evidence. In a regulatory environment that demands transparency, AI explainability is the foundation.”
As regulators require more defensible, consistent, and transparent investigations, financial institutions are under pressure to modernize workflows that rely on manual analysis and fragmented tools. By embedding Agentic AI directly into the investigation process, ThetaRay is positioning Ray amid the next generation of AML operations in which regulators require speed, consistency, and explainability.
Founded in 2013, ThetaRay offers transaction monitoring, transaction and customer screening, and customer risk assessment suites to help firms fight financial crime. The Israel-based company helps its 100+ institutional clients leverage AI to monitor 15 billion transactions valued at $20 trillion on an annual basis.