Banking Circle Launches Stablecoin Settlement Services

Banking Circle Launches Stablecoin Settlement Services
  • Banking Circle launched fiat-to-stablecoin and stablecoin-to-fiat settlement, enabling banks to move funds seamlessly across traditional and blockchain rails with instant settlement and regulatory traceability.
  • The move comes days after Banking Circle received its CASP license, which positions Banking Circle to embed stablecoin capabilities directly into a bank’s existing infrastructure.
  • Stablecoins are quickly emerging as an always-on settlement layer that is becoming standard in cross-border payments.

European cross-border payments fintech Banking Circle is narrowing the gap between stablecoin and fiat today. The fintech is launching stablecoin settlement services, a suite of fiat-to-stablecoin and stablecoin-to-fiat capabilities that will facilitate the movement of funds, regardless of whether they sit on bank rails or blockchain rails.

The announcement comes days after Banking Circle received a Crypto-Asset Service Provider (CASP) license from the Commission de Surveillance du Secteur Financier (CSSF). The newly minted license will allow Banking Circle to expand from cross-border fiat services into digital asset services.

“The award of our CASP license is an important milestone for Banking Circle, as well as for the broader payments ecosystem,” said Banking Circle CEO Laust Bertelsen. “Stablecoins have fast evolved from a peripheral innovation into core infrastructure for cross-border settlement, treasury management, and financial inclusion.”

Banking Circle will integrate its new stablecoin settlement service into banks’ existing infrastructure to help them take advantage of stablecoin rails. The new tools will offer increased security, lower risk, and more convenience than traditional global settlement rails, creating efficiencies for banks.

After they integrate with Banking Circle’s core platform, clients will be able to interoperate between fiat currencies and leading stablecoins, including USDC, USDG, and EURI. Leveraging stablecoin rails, Banking Circle will offer instant settlement and full regulatory traceability.

“We have spent years building the financial infrastructure that enables more than 750 payment companies, financial institutions, and marketplaces to efficiently move and convert over €1.5 trillion annually across the globe,” said Banking Circle Chief Digital Asset Officer Kirit Bhatia. “Stablecoins are a natural extension of that infrastructure and central to our mission of eliminating unnecessary cost and complexity through technology.”

Founded in 2013, Banking Circle was acquired by private equity firm EQT in 2018 for $300 million. Headquartered in Luxembourg and regulated by the Commission de Surveillance du Secteur Financier (CSSF), the bank is fully licensed and serves as a correspondent bank offering multi-currency bank accounts and virtual IBANs as well as bank connections for local clearing and cross-border payments.

Banking Circle has branches in Denmark, Sweden, Germany, Norway, Poland, the Czech Republic and the UK, and subsidiaries in Liechtenstein, Singapore and Australia. 

Banking Circle’s announcement shows that banks across the globe are rethinking the underlying infrastructure of payments. Stablecoins are emerging as an always-on settlement layer that can complement traditional correspondent banking networks. As banks across the globe integrate stablecoin payments rails into their platforms, and as the global stablecoin market reaches approximately $293 billion, it is becoming clear that stablecoin rails are slowly becoming a standard part of cross-border payments, rather than an alternative.

Fintech Rundown: A Rapid Review of Weekly News

Fintech Rundown: A Rapid Review of Weekly News

As we prepare to welcome the month of May, take a look at this week’s latest fintech and banking news. The top of the week brings very payments-heavy headlines, but I expect we’ll see an uptick of news across the board as New York Fintech Week heats up. We’ll continue to add more announcements as the week progresses.

Payments

India’s central ​bank cancels Paytm Payments Bank’s payments license.

Western Union plans stablecoin launch to modernize its payment systems.

Pine Labs acquires a 100% stake in D2C checkout platform Shopflo Technologies.

Banking Circle launches stablecoin clearing service.

OnePay partners with Tempo for stablecoin-powered payouts and account funding.

Nium and Coinbase partner to power global stablecoin payments and settlement.

PayNearMe appoints Niall Hayes Chief Development Officer, EVP of Engineering.

Financial management

Prophix launches the next wave of Prophix One Agents, defining the delegation era for finance.

Digital banking

Akbank AG completes Phase 1 of its core banking transformation to Mambu. 

Loyalty Credit Union goes live with authenticated chat through Eltropy and Mahalo integration.

Fraud and identity

Jumio announces Mark Lorion as Chief Executive Officer.

Former Okta President of Auth0, Shiven Ramji, to join Cellebrite as President, Products and Technology.


Photo by cottonbro studio

Adyen to Acquire Loyalty Platform Talon.One

Adyen to Acquire Loyalty Platform Talon.One
  • Adyen is acquiring Talon.One for $879 million to add enterprise loyalty, promotions, and incentive infrastructure used by 300+ brands.
  • Adding Talon.One’s loyalty infrastructure moves Adyen beyond payments into real-time decisioning to enable merchants to connect identity, pricing, and promotions and act during the transaction.
  • The new infrastructure can dynamically deliver offers during AI-driven shopping experiences to help shape purchases.

Payments platform Adyen is acquiring loyalty solutions company Talon.One in a deal valued at $879 million (€750 million). The deal is expected to close in the second half of 2026.

Germany-based Talon.One serves as the loyalty infrastructure for 300 enterprises, including large brands such as Nordstrom and H&M. Founded in 2015, the company offers tools for enterprise loyalty management, personalized promotions, and incentive optimization. Earlier this year, Talon.One released Unified Incentives Protocol (UIP), a new set of standards that shows available promotions and loyalty incentive offers within AI agent-based shopping experiences.

“Joining Adyen allows us to embed real-time decisioning at the core of every transaction,” said Talon.One Co-founders Christoph Gerber and Sebastian Haas. “Together, we enable merchants to connect customer identity with pricing and promotions in real time, in-store and online, driving better outcomes for our customers.”

Adyen anticipates that bringing in Talon.One will help connect online and in-store shopper interactions, enabling merchants to act on the insights in real-time. Combining Adyen’s payments infrastructure and transaction data with Talon.One’s real-time decisioning capabilities will allow merchants to establish a consistent customer identity across channels. Merchants can use this information to dynamically adjust promotions and pricing based on aspects of the customer identity.

“Our merchants ask us every day how they can better connect their online and in-store customer data and act on that in real time,” said Adyen Co-CEO Ingo Uytdehaage. “Many have tried to build a solution themselves but struggle to turn insights into action. With Talon.One, a merchant can recognize a shopper and apply a relevant offer instantly, before the payment is completed, ultimately driving higher revenue.”

Adyen considers the acquisition a “natural next step” in its investment in unified commerce and data products. Talon.One will enable it to link customer identity directly to SKU-level promotions and incentives within the flow of payments to improve conversion, fraud, and customer lifetime value.

Ultimately, the deal elevates Adyen beyond payment rails into a real-time decisioning layer within the transaction itself. By combining payments data with loyalty and promotion logic, Adyen is acting on the fact that transaction data is only valuable if it can be operationalized at the moment the purchase decision is still being made.

As the move toward agentic commerce accelerates, acting in the moment of the purchase becomes even more critical. AI-driven shopping experiences will increasingly surface and execute offers on behalf of consumers, making infrastructure that can dynamically deliver pricing, incentives, and identity-aware promotions a competitive differentiator.

Moomoo Launches Agentic Investing in the Form of API Skills

Moomoo Launches Agentic Investing in the Form of API Skills
  • Moomoo launches API Skills to connect personal AI agents to trading and allow investors to use natural language to build and execute strategies without coding.
  • The new tools include strategy validation, intent-to-execution translation, and 24/7 market monitoring inside a pro trading environment.
  • Moomoo enables external AI agents via APIs, giving users control, flexibility, and local data security.

Online investment and trading platform Moomoo is launching agentic investing tools this week. The California-based company has launched API Skills to allow retail investors to connect their personal AI agents directly to Moomoo’s infrastructure.

With API Skills, investors can use natural language commands to create structured, executable investment strategies without coding. The tool integrates with multiple AI agent frameworks, enabling always-on agents that act as 24/7 trading assistants that continuously interpret market data, monitor conditions, and prepare trades based on a user’s goals within a professional-grade trading environment.

“With Moomoo API Skills, we are reducing the technical barriers that once stood between an idea and its execution, enabling clients’ personal AI agents to connect directly with our platform while ensuring investors retain full control of every decision,” said Moomoo Canada CEO Michael Arbus.

The new tool not only helps non-technical users automate their trading decisions, but it also helps investors save time by streamlining more complex workflows. Included in the API Skills are: automated strategy validation that allows users to review, refine, and validate their strategies before deploying them; intent-driven development that translates natural language commands into structured logic to execute the move in the market; and a volatility monitor that detects market shifts 24/7.

With Moomoo’s API Skills, all trading credentials and sensitive account data remain within the user’s local environment instead of passing through third-party AI servers. The new capability also allows users to test and explore their agent’s logic using virtual funds before moving the logic into the wild.

Moomoo isn’t the only trading platform empowering users with agentic trading. Last month, brokerage platform Public introduced AI agents to automate their portfolio strategies with AI. The two approaches are slightly different, however. While Public’s agents are native, consumer-facing agents geared toward retail investors, Moomoo is an API layer for builders that lets external AI agents plug into trading.

Founded in 2018, Moomoo has 29 million investors across Singapore, Australia, Japan, Canada, Malaysia, and New Zealand.

Oracle Brings Agentic AI Platform to Corporate Banking

Oracle Brings Agentic AI Platform to Corporate Banking
  • Oracle is embedding agentic AI directly into corporate banking workflows, launching pre-built agents across credit, trade finance, treasury, and lending.
  • The tools target some of banking’s most manual, document-heavy processes, enabling faster decisions and allowing teams to scale output without adding headcount.
  • With a human-in-the-loop approach and hundreds more agents coming, Oracle is positioning AI as operational infrastructure.

Enterprise technology company Oracle is deepening its agentic AI prowess this week. The Texas-based company announced it is adding new embedded AI capabilities and agents for its corporate bank clients.

Oracle’s new agentic AI tools will offer clients a suite of AI-infused applications and pre-built AI agents for treasury, trade finance, credit, and lending. As a result, firms can automate once-manual processes and speed decision-making, ultimately unlocking new opportunities for growth.

“Corporate banking runs on precision, resiliency, and trust,” said Oracle Financial Services Senior Vice President Sovan Shatpathy. “Our AI-powered platform embeds intelligence directly into mission-critical processes, accelerating decisions and strengthening governance so banks can serve clients with greater speed and confidence.”

The two main pillars of the new launch include corporate credit and trade and supply chain finance. The corporate credit arm has five main agents that help with data extraction from loans, financial statements, and documents, and generate credit memo reports. The trade and supply chain finance has an application validator agent that ingests bank guarantee application packages and supporting documents and delivers a risk recommendation, as well as an agent that analyzes sales contracts and designs an appropriate supply chain finance program.

Because Oracle’s agentic AI takes a human-in-the-loop approach, all decisions are supported by human expertise, maintaining oversight and ethical governance. Oracle said that these agents are among “hundreds” of other corporate and retail banking agents that will launch in the next 12 months.

Much of the AI development we’ve seen in banking over the past two years has been customer-facing, taking the form of chatbots and personalization tools. Oracle’s new push into agents removes the strain from some of the most manual, document-heavy parts of corporate banking. Instead of just offering faster memo writing, Oracle’s tools allow credit teams to handle more deals without increasing headcount, offer a standardized approach to trade finance, and provide banks a way to offer faster response time to their clients.

Five Fintechs Helping Banks Build and Launch Better Financial Products

Five Fintechs Helping Banks Build and Launch Better Financial Products

Launching and scaling new products isn’t as simple as developing a new tool and making it live. There are plenty of tasks that need to be considered alongside the actual product release, including governance and compliance, marketing and social campaigns, consumer testing and surveying, finding and fixing vulnerabilities, and consumer follow-up.

At FinovateSpring 2026 in San Diego, we’re hosting five fintechs that are making this next phase of product launches possible. Check out the variety of capabilities and learn more about the companies behind them below.


PentEdge

PentEdge AIMS gives community banks and credit unions an examiner-ready AI governance platform that’s purpose-built for the $500 million to $100 billion institutions navigating federal AI risk guidance. Founded in 2025, the North Creek, New York-based company delivers a real-time scoring dashboard with a view of AI exposure across a portfolio, offers pre-built vendor AI risk profiles, and provides audit-ready PDFs for examiners.


Intention.ly

Intention.ly’s Advisor Brand Builder (ABB) helps firms build a differentiated brand, website, and content engine in a matter of days to enable advisors to attract ideal clients and outpace competitors. Among the company’s engagement options are a diagnostic assessment, a fractional CMO and COO, an outsourced marketing team, and more. Headquartered in King of Prussia, Pennsylvania, Intention.ly was founded in 2021.


PwC

Customer Link by PwC offers banks a set of “synthetic customers” through which they can test products, pricing, and experiences. Firms can use results to quickly generate quant data and turn survey crosstabs into clear, segment-specific growth actions.

Founded in 1998, PwC provides clients with a wide range of capabilities, including consulting, cybersecurity, AI, audit, and more. The company is headquartered in New York.


Rezliant

Rezliant’s Maestro Pulse helps fintechs, payment providers, and small financial institutions automatically fix security vulnerabilities in their codebases, PII (Personally Identifiable Information) data flows, and API integrations. The company provides contextualized triage of fintech vulnerabilities, automates remediation of multiple critical flaws simultaneously, and delivers effortless two-click fixes directly from email notifications.

Headquartered in Mesa, Arizona, Rezliant was founded in 2023.


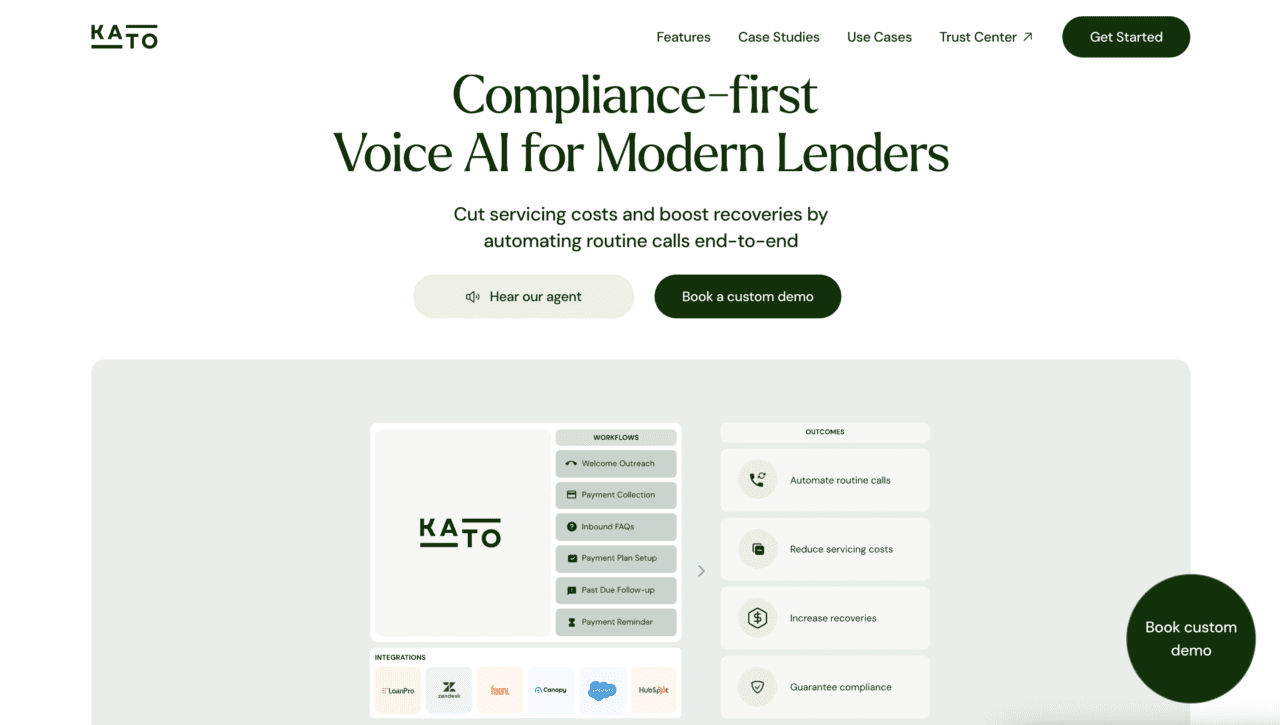
Kato

Founded in 2024, Kato helps lenders scale with compliance-first automation. The San Francisco-based company’s technology helps firms reduce servicing costs up to 80%, increasing recoveries by 1%, and freeing agents to focus on high-value work.


Why banks should care

While it seems like the hard work of a new product launch is the planning and development phase, the reality is that execution is where most initiatives succeed or fail. Banks are expected to move faster, create and develop more frequently, and deliver better customer experiences. Doing so, however, requires navigating compliance requirements, validating product-market fit, securing systems, and effectively bringing products to market.

Platforms that support these adjacent functions help reduce the friction that often slows product launches. They enable banks to move from idea to execution more efficiently, while minimizing risk and ensuring alignment with regulatory expectations. In an environment where speed and precision both matter, having the right infrastructure around product launches can be the saving grace that changes a product from a failure into a success.


Want to attend? Now is the time to lock it in. Get 40% off this week only with code FKV2794ART (ends April 17): https://informaconnect.com/finovatespring/purchase/select-package/?vip_code=FKV2794ART


Photo by Monstera Production

Airwallex Launches Physical Point of Sale Device

Airwallex Launches Physical Point of Sale Device
  • Airwallex launched Airwallex POS Payments, a physical point-of-sale device.
  • The device will enable physical, in-store payments that integrate with Airwallex’s broader commerce stack.
  • The new launch helps Airwallex compete with Square and Stripe, but Airwallex has an advantage in regions where it holds banking licenses.

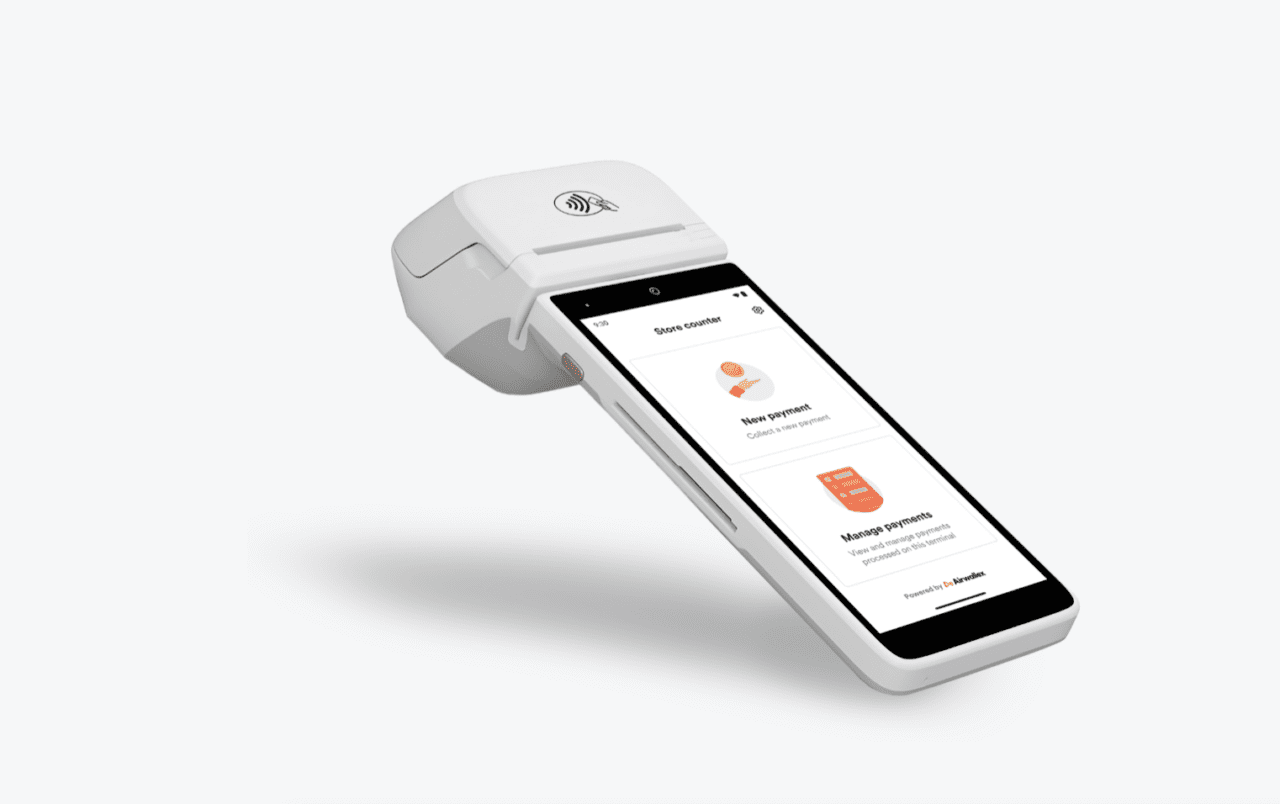
While the rest of the payments world is racing toward agentic payments, Airwallex is bringing its focus back to the physical world. The Singapore-based company announced this week that it has launched Airwallex POS Payments, a physical point-of-sale (POS) device.

The new, physical device integrates with the company’s commerce stack to unify online and in-store payments. Bringing everything together will help merchants offer consistent payment flows, reporting, and customer experiences across multiple channels. Enterprise retailers will gain more visibility and control across channels, while SaaS platforms will gain the ability to embed in-store payments directly into their products.

“By extending our global financial platform to the physical countertop, we’re bringing online and in-store payments together, reducing the fragmentation that has long held in-store payments back, and giving enterprises a truly global foundation for growth,” the company said in its announcement.

Adding physical POS devices places Airwallex directly in competition with Square, a pioneer in the mobile POS hardware space, and Stripe, which offered to acquire Airwallex in 2019 for $1.2 billion. Airwallex has an advantage over these two legacy players in certain regions, however. In Japan, for instance, where the company holds a banking license, the fintech owns both the backend banking infrastructure, as well as the front-facing software. So when a merchant is paid, Airwallex can hold the funds instead of having to transfer them to the merchant’s primary bank account.

Founded in 2015, Airwallex holds nearly 90 regulatory licenses and permits across 50 markets that enable customers to operate in 200+ countries and regions and support multi-currency checkout at scale. In 2025 alone, the company extended its regulated and local capabilities across 12 new markets, securing licenses and launching products in France, the Netherlands, Israel, Canada, Korea, Japan, New Zealand, Malaysia, Vietnam, Brazil, Mexico, and the UAE.

The new POS payments device is now available across the UK, Europe, Hong Kong, and Singapore, with plans to launch in Australia and the US, where it currently serves 46,000 businesses.

eToro Acquires Crypto Wallet Zengo

eToro Acquires Crypto Wallet Zengo
  • eToro has acquired self-custodial wallet provider Zengo to deepen its digital asset capabilities and expand into on-chain finance.
  • The deal brings keyless wallet infrastructure in-house, positioning eToro to move beyond trading into custody, authentication, and transaction control.
  • As crypto evolves into infrastructure, owning the wallet layer could determine who controls the customer relationship.

Social trading and investment network eToro announced it has acquired self-custodial crypto wallet provider Zengo for an undisclosed amount. eToro plans to leverage the acquisition to deepen its digital asset capabilities and bridge traditional finance with on-chain infrastructure.

Zengo was founded in 2018 and offers a crypto wallet with buy, sell, and swap capabilities to both individual and commercial users. The Israel-based company positions itself as a secure crypto wallet, offering Bitcoin vaults, theft protection, a Web3 firewall, and enterprise-grade compliance and controls for commercial users. Notably, Zengo is a pioneer in multi-party computation cryptography and is known for its keyless wallet architecture.

“We believe the future of finance will be increasingly digital, decentralized, and user-controlled, with self-custody playing an important role in that evolution,” said eToro Co-founder and CEO Yoni Assia. “Zengo has built an innovative and secure wallet experience, and this acquisition will enable us to accelerate its growth while continuing to provide users with choice in how they access digital assets.”

eToro will combine its multi-asset platform with Zengo’s non-custodial wallet technology to expand on its own digital asset capabilities while growing Zengo’s platform. “From day one, Zengo has focused on making self-custody simple and secure for everyday users,” said Zengo Co-founder and CEO Ouriel Ohayon. “Joining eToro allows us to accelerate that mission at a global scale. Together, we can expand access to self-custody and on-chain finance while connecting it to a broader investing ecosystem that bridges traditional and on-chain finance.”

Founded in 2007, eToro launched Bitcoin trading capabilities in 2013, but didn’t launch a dedicated crypto trading platform in the US until 2019. Today’s acquisition will help eToro expand into tokenized assets and emerging decentralized trading models such as prediction markets and perpetuals.

As the banking world increasingly normalizes decentralized finance, it may no longer be enough for fintechs and investment firms to simply offer traditional finance investing tools, especially as crypto evolves from an asset class into infrastructure.

By acquiring Zengo, eToro is positioning itself to participate more directly in on-chain activity, rather than simply offering access to facilitate trades. The deal is another example of fintechs pushing deeper into infrastructure. Self-custody wallets are emerging as the interface layer for on-chain finance. By bringing that capability in-house, eToro is positioning itself to control digital assets, storage, authentication, and transactions.

Five Fintechs Helping Banks Manage Risk, Compliance, and Governance

Five Fintechs Helping Banks Manage Risk, Compliance, and Governance

Financial services are growing more complex, which means that risk, compliance, and governance are no longer simply back-office functions. These services, which were once considered “boring” aspects of fintech, are now core to how banks and fintechs operate, compete, and scale. From evolving regulatory expectations to increasingly sophisticated fraud and operational risks, financial institutions are under constant pressure to maintain control while continuing to innovate.

At FinovateSpring 2026, a new group of companies is demonstrating how banks can modernize governance, streamline compliance, and better manage risk across the organization. Below are five companies helping banks move toward a more proactive, automated, and scalable approach to risk, compliance, and governance.


CRIF

CRIF delivers a broad suite of credit bureau services, analytics, and decisioning platforms that help financial institutions make smarter, faster, and more transparent lending decisions. Its technology enables banks and lenders to design, test, and deploy credit strategies with greater speed and control, combining data, analytics, and governance into a single framework.

The platform offers no-code strategy design for business users, real-time simulations with KPI validation, and embedded AI agents that support compliant and explainable decisioning. Headquartered in Italy and founded in 1988, CRIF serves banks, credit unions, fintechs, and lenders globally, helping them modernize credit risk management while maintaining regulatory confidence.


Rulebase

Rulebase helps financial institutions scale compliance by automating testing and quality assurance across customer interactions and internal workflows. Its platform continuously monitors activity, detects potential violations, and generates audit-ready evidence, enabling teams to move beyond manual reviews and point-in-time checks.

By improving speed and accuracy while reducing regulatory risk, Rulebase allows organizations to focus on high value activity while maintaining compliance. Founded in 2025 and headquartered in New York, the company offers a modern approach to embedding compliance directly into day-to-day operations.


Winnow

Winnow helps financial institutions simplify and streamline compliance by replacing manual research and fragmented processes with a centralized, easy-to-use platform. Its solution delivers tailored, attorney-reviewed regulatory guidance, enabling organizations to quickly understand and meet their compliance obligations without the time and cost of traditional methods.

By reducing complexity and improving accuracy, Winnow allows teams to spend less time interpreting regulations and more time executing against them. Founded in 2018 and headquartered in Anaheim, California, Winnow provides a more efficient path to staying compliant in a complex regulatory environment.


The Electronic Guardian

The Electronic Guardian offers a secure digital repository designed to help individuals organize, protect, and transfer critical financial and personal information. Its platform, The Coop, consolidates important documents and assets into a centralized system that evolves into a comprehensive estate inventory, supporting legacy planning and asset continuity.

Built with private encryption and “at rest” recoverability, The Coop ensures sensitive information remains both secure and accessible when it matters most. Founded in 2019 and headquartered in Pittsburgh, The Electronic Guardian enables banks, credit unions, and insurance providers to offer added value through estate organization and long-term asset protection solutions.


Model IQ by Kevin D. Oden & Associates

Model IQ, developed by Kevin D. Oden and Associates, is an automated platform designed to help financial institutions manage model risk and meet stringent regulatory requirements. Built by quants, the solution streamlines compliance with SR 11-7, FDIC, and NCUA guidelines by bringing structure, speed, and consistency to the model risk management process.

The platform automates the entire model lifecycle to accelerate review timelines while improving accuracy and audit readiness. Founded in 2018 and headquartered in San Francisco, Model IQ serves financial institutions ranging from community credit unions to regional banks and fintechs, offering a scalable approach to governance in an increasingly model-driven industry.


Why banks should care

Risk, compliance, and governance are central to a bank’s operations, directly impacting an organization’s ability to scale. As banks adopt AI, expand digital channels, and operate across increasingly complex regulatory environments, the volume and velocity of risk has increased to a point where manual processes and siloed systems can’t keep up.

Platforms that automate compliance testing, improve decision transparency, and streamline model risk management offer banks a way to stay ahead of regulators while operating more efficiently. Just as importantly, they reduce the operational burden on internal teams.

For end users, having a place to store and manage their key documents can be crucial for both security and organization. Financial institutions that offer tools like this as a benefit will not only add a revenue stream, but will also give clients another reason to associate them with safety and security.


Photo by Ilkauri Scheer

Synctera Acquires Compliance Fintech Cable

Synctera Acquires Compliance Fintech Cable
  • Synctera has acquired Cable to add real-time compliance monitoring and automated control testing to its BaaS platform.
  • Cable enables continuous, end-to-end oversight of fintech programs, replacing traditional point-in-time compliance checks.
  • Financial terms of the deal were undisclosed.

In the BaaS world, compliance is quickly moving from a box-checking exercise to a continuous, provable requirement. That’s why embedded finance and BaaS fintech Synctera has acquired financial risk control platform Cable.

From Finovate’s perspective, this is a fun announcement to see, as both companies have demoed at Finovate in the past. Cable showcased its Automated Assurance product at FinovateFall 2022. Two years later, Synctera demoed its platform at FinovateFall 2024.

UK-based Cable was founded in 2020 to offer a financial risk control platform with automated testing and real-time alerts that help clients manage, track, and have full oversight of the controls. Cable works in conjunction with a firm’s existing compliance infrastructure to test whether controls, such as KYC, transaction monitoring rules, AML, and other workflows are functioning as designed.

“Synctera has always focused on helping banks and fintechs build and scale responsibly,” said Synctera Co-founder and CEO Peter Hazlehurst. “But execution alone isn’t enough. Banks need visibility into how those systems are performing in real time. Cable provides that missing observability layer, giving our partners confidence that controls are working as intended across their entire fintech ecosystem. Most solutions in this space are theater. Cable isn’t.”

While Cable initially launched to help firms manage financial crime, Cable has since doubled down on helping partner banks, including Axiom Bank, Quaint Oak Bank, and Griffin, manage their fintech programs. Instead of taking a sampling-based approach that only offers a snapshot in time, Cable helps sponsor banks approach compliance with continuous, end-to-end oversight of their fintech programs.

“Banks are being asked to stand behind the performance of increasingly complex fintech ecosystems,” said Natasha Vernier, co-founder of Cable. “That requires a fundamentally different approach: one that is continuous, data-driven, and verifiable. We built Cable to meet that need, and joining Synctera allows us to bring that capability to a much broader market.”

Once the acquisition is finalized, the Cable team will join Synctera to build out the compliance infrastructure banks and fintechs need to operate responsibly. Cable will also continue to serve its existing client base and will be available as a standalone offering.

As partner bank–fintech relationships scale, traditional oversight that only offers a point-in-time snapshot is no longer sufficient to meet regulatory expectations. Instead, banks are being pushed toward continuous, real-time visibility into how controls are performing across their ecosystems. By integrating Cable’s automated testing and monitoring capabilities, Synctera is positioning itself as not just execution infrastructure, but also as a built-in verification tool.

Financial terms of the deal were not disclosed.

London-Based Round Raises $6 Million to Automate Treasury Management

London-Based Round Raises $6 Million to Automate Treasury Management
  • Round has raised $6 million and announced the launch of agentic workflow and autonomous payroll tools to automate treasury, AP, and payroll.
  • The company combines AI-driven automation with owned payment infrastructure to fully execute finance teams’ money movement commands.
  • By sitting in the flow of funds, Round introduces new competition for banks, treasury management system providers, and fintechs.

Treasury management company Round has closed $6 million in seed funding this week, boosting its total funding to $8.1 million. The London-based fintech is also unveiling two new products: Agentic Workflow Builder and Autonomous Payroll. 

Today’s round was led by Alstin Capital. Existing investors including Passion Capital, along with new investors Backed VC and Love Ventures, as well as angel investors, also contributed. Uniquely, Round’s own clients also invested. Around 10% of the company’s customer base contributed to today’s round.

“We are building for the finance team of the future, one that understands the importance of automation to keep up with the pace of modern companies. AI tools are rapidly being deployed across the industry and finance teams do not need to be left behind,” said Round Cofounder Hayyaan Ahmad.

The company will use today’s funding to accelerate product development, expand its engineering and go-to-market teams, deepen integrations across banks and accounting systems, and scale its existing infrastructure. Round also has plans to launch community-focused events such as hackathons, hands-on workshops, and webinars.

Round’s new Agentic Workflow Builder, which is currently in early access, builds a workflow based on a natural language description. It allows finance teams to run workflows autonomously that previously required an employee. The Agentic Workflow Builder can run 24/7 and notify teams via Slack, WhatsApp, or email if something needs attention.

Similarly, Autonomous Payroll essentially helps payroll run itself, autonomously pulling funds and executing the payment on schedule. It eliminates the need for finance teams to log into multiple systems to make payroll each month.

Treasury, payroll, and accounts payable have historically been fragmented across banks, ERP systems, and manual workflows. By combining agentic AI with owned payment infrastructure, Round is aiming to collapse those layers into a single, autonomous system.

Round was founded in 2023 to reduce the manual work involved in treasury management by automating workflows. The company automates treasury, accounts payable, and payroll to save finance teams the manual, repetitive work involved in moving funds around to optimize yield.

Round differentiates itself from other automated workflow platforms because it owns and manages the infrastructure involved, such as wallets and payment rails. Clients can leverage that infrastructure, along with Round’s machine learning and intelligence to set rules for approval thresholds, payment schedules, and cash minimums, to ensure payroll obligations are met, and that idle cash is invested appropriately. Since launching its first automated workflows less than a year ago, Round has processed over $500 million.

With Round owning the infrastructure, banks, legacy treasury providers, and even fintechs face a new type of competition. Traditional treasury management systems such as Kyriba offer visibility and controls, but often rely on integrations with external banks and require manual execution. Newer fintechs like Ramp, Brex, and Airbase offer spend management and accounts payable tools, but do not offer full autonomous fund movement.

Moving forward, Round’s challenge will be client trust and regulatory oversight. While finance teams may be willing to automate workflows, they may be less willing to fully automate money movement, especially when it comes to payroll.


Photo by Jan van der Wolf

Fintech Rundown: A Rapid Review of Weekly News

Fintech Rundown: A Rapid Review of Weekly News

There may be April showers out your window, but the fintech landscape is all flowers this week. Take a look at all of the highlights from fintech funding, product developments, partnerships, and more below. We’ll continue to add more announcements as the week progresses.

Payments

Gr4vy supports agentic payments through orchestration and launches development kit to prepare merchants for AI commerce.

Adyen launches Intelligent Money Movement to unify enterprise payments, liquidity management, and payouts.

GoCardless grows 22% in 2025, records first quarter of profitability.

Wise plans to move public listing from London to Nasdaq in May.

Icon Solutions appoints Anders Olofsson as EMEA Sales Director.

Investing and wealth management

Vested crossed $1 billion in assets under administration.

Small business tools

Remote expands its global employment infrastructure with acquisition of Bravas.

Round raises $6 million to automate treasury management.

InvoiceCloud unveils AI-powered billing experience.

Yooz introduces intelligent Line‑Level Matching to bring item-level automation and accuracy to invoice reconciliation.

Digital banking platforms

Nymbus launches secure MCP server for AI-driven core banking actions.

Beforepay appoints Kasey Kaplan as Deputy CEO.

Physical banking tools

Founders Federal Credit Union selects NCR Atleos for ATMaaS to modernize member self-service experience.


Photo by wal_ 172619