This site is operated by a business or businesses owned by Informa PLC and all copyright resides with them. Informa PLC's registered office is 5 Howick Place, London SW1P 1WG. Registered in England and Wales. Number 8860726.
Finovate Blog
Tracking fintech, banking & financial services innovations since 1994
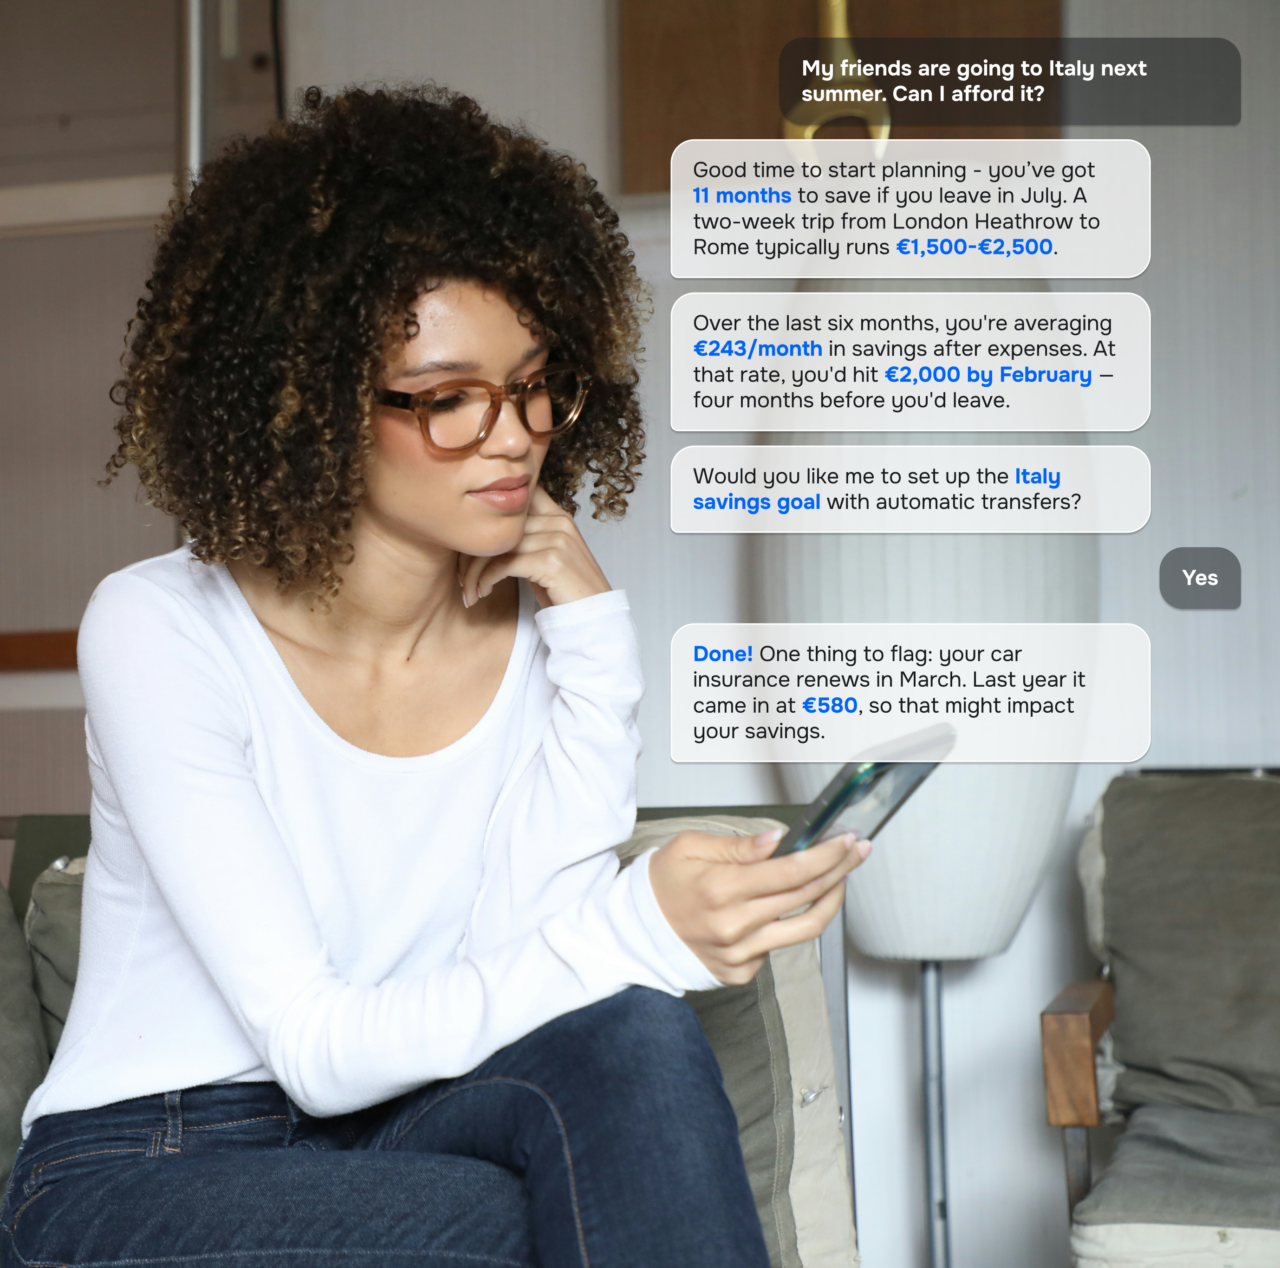
Personal finance solutions fintech Meniga launched a new product called Fini, an MCP server that enables banks to bring agentic AI into their existing platforms.
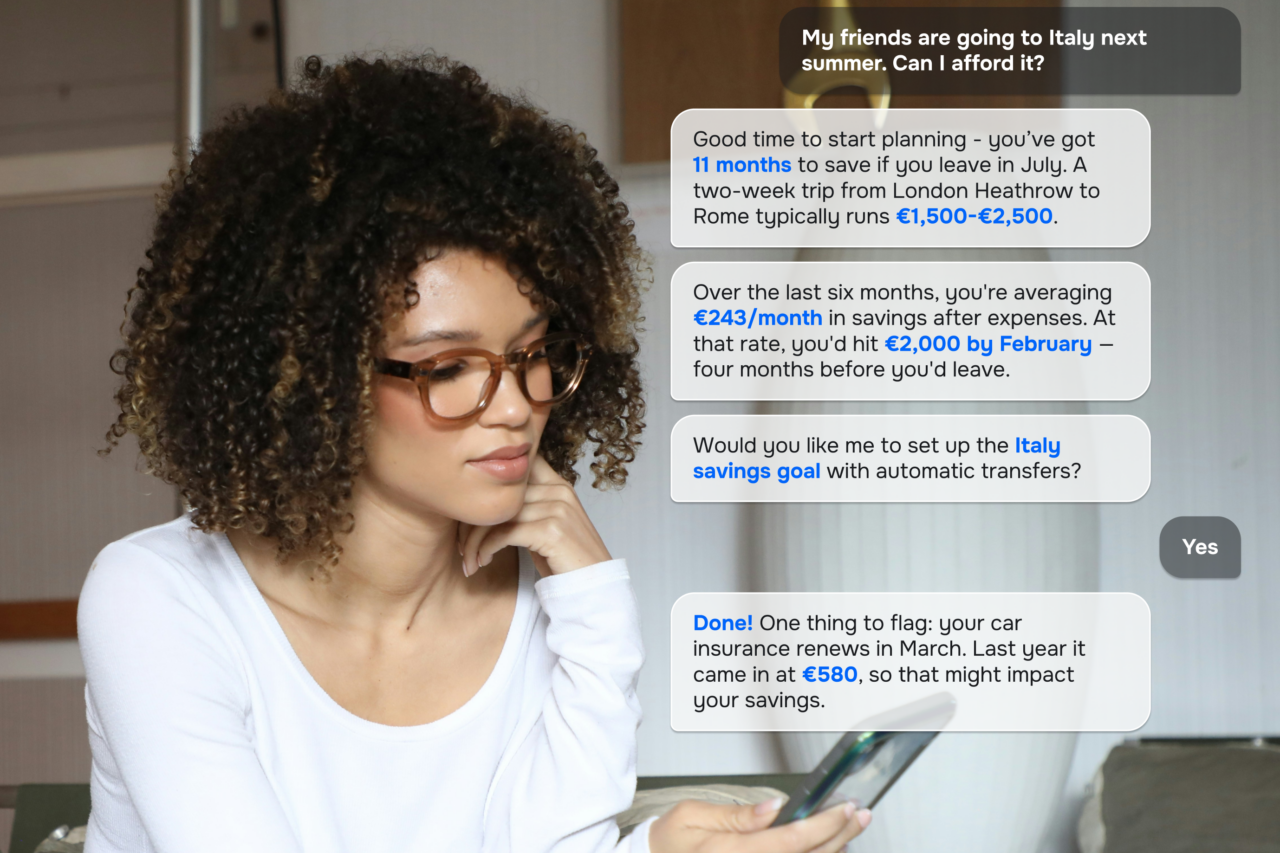
Fini, which was built with the input of five large banks, serves as the bridge between a bank’s preferred large language model (LLM) and Meniga’s personal finance, enrichment, and insights capabilities. Rather than building its own AI model, Meniga enables banks to pair Claude, GPT, Gemini, or another LLM with the company’s financial intelligence platform, allowing customers to ask questions about their finances in natural language within the bank’s website or mobile app.
Founded in 2009, Meniga serves over 100 million banking customers across 30 countries. The UK-based company’s clients include UniCredit, Groupe BPCE, UOB, Swedbank, SAB, Tangerine, and Riyad Bank. Meniga’s intelligence and personalization layer helps banks turn financial data into insights and proactively anticipate customer needs, promoting engagement.
Meniga anticipates that this conversational interface will benefit banks by engaging with consumers on a deeper level, increase satisfaction, lower support costs, and offer insights into customers’ individual needs. The new tool also meets consumers where they are, especially as their preferences shift away from features and towards conversational interfaces that offer instant, personalized answers.
“The banks that win agentic banking will be the ones that ground their conversational layer in real financial context. Not a generic chatbot, but an assistant that actually knows a customer’s spending patterns, their goals, and their upcoming bills, and is able to act on them,” said Meniga CEO Raj Soni.“With Fini, banks can enter the AI-agent era on the platform they already trust, without rebuilding what’s underneath, and without their data ever leaving the bank.”
Beyond answering questions, Fini supports agentic AI workflows that allow customers to complete certain banking tasks, like opening new accounts or setting up automatic transfers, directly within the conversation. This eliminates the need to navigate to separate screens.
Because Fini is model-agnostic, banks can build their AI assistants on Claude, GPT, Gemini, or their own proprietary model while relying on Meniga to provide the underlying financial context. Banks also retain control over their own guardrails, identity and access controls, and customer data, which never leaves the bank.
Meniga’s launch is similar to those of other fintechs racing to capture the LLM opportunity for consumer financial management. Rather than developing proprietary large language models, banks are increasingly viewing AI as a layered architecture. Foundation models such as Claude, GPT, or Gemini provide the conversational interface, while companies like Meniga provide the financial intelligence needed to ground those conversations in a customer’s actual spending patterns, cash flow, subscriptions, and financial goals. This approach enables banks to adopt new AI models as they emerge without rebuilding the personal financial management capabilities that differentiate their customer experience.
Robinhood announced a handful of features last week, including the rollout of Robinhood Earn, a decentralized lending product that allows people to lend their dollar-backed USDG through a self-custody wallet at an estimated 7% APY. This estimated 7% APY on USDG stablecoin deposits is high enough to raise eyebrows, especially at a time when banks are paying closer to 3% to 4% on their highest-yield savings accounts. So how can Robinhood sustainably offer 7%?
Robinhood Earn
First, let’s take a look at the details of the launch. Robinhood Earn applies to USDG, a stablecoin issued by Paxos Digital Singapore and Paxos Issuance Europe. Robinhood is not paying 7% APY on bank deposits. Instead, the yield is generated by lending activity for Robinhood users who lend stablecoins using Morpho, a decentralized lending protocol that powers onchain lending. Just as with fiat lending, there is risk in lending stablecoins. Users still assume the risk on the deposits. However, Robinhood has partnered with Lloyd’s of London and RELM to protect covered losses in the event of cyber or smart contract exploits. Essentially, the company is bringing decentralized finance (DeFi) into a familiar customer experience.
The 7% interest strategy appears no different from a fintech offering a new high-yield savings account that pays an above-average yield of over 4% APY in order to incentivize consumers to open new accounts. It is a marketing tool. Robinhood’s new DeFi lending product is already integrated into its mainstream brokerage experience, so the 7% is the additional incentive for users to convert cash to USDG, begin using Robinhood Chain, and eventually use tokenized assets and on-chain services.
Should banks offer 7% yield?
It is important for firms to recognize that yield has become a feature, not the product. If stablecoins become everyday money, what role does the deposit account play? If consumers can earn yield without a traditional bank account, how should banks compete? And what happens when customers don’t even realize they’re using decentralized finance?
The answer isn’t necessarily to match Robinhood’s 7% yield, which is good, because banks already know that offering a 7% yield is off the table. Instead, banks should focus on the advantages DeFi can’t easily replicate:
Trust FDIC insurance, consumer protections, fraud resolution, and regulatory oversight still matter—especially during periods of market volatility.
Financial relationships Consumers don’t just need a place to store money. They need mortgages, auto loans, credit cards, financial advice, and payment services. Banks have an opportunity to integrate yield-generating products into a broader relationship.
Simplicity Robinhood’s announcement demonstrates that consumers don’t want to navigate wallets, bridges, or smart contracts. Banks that can abstract blockchain complexity while maintaining a familiar customer experience will be well positioned.
Hybrid models Rather than viewing DeFi as competition, banks may eventually incorporate tokenized deposits, stablecoins, or on-chain lending into their own offerings, allowing customers to benefit from blockchain infrastructure without leaving the regulated banking system.
In the new era of finance, the winners will be those that make DeFi invisible. Just as most consumers don’t think about ACH, RTP, or card networks when they use a credit card, in the future they may not care whether their yield comes from a bank balance sheet or an on-chain lending protocol. Instead, they’ll choose the institution that offers the best combination of return, trust, and convenience.
Klarna has applied to establish Klarna Bank USA, a Utah-chartered industrial bank, marking its latest step toward becoming a full-service bank in the US.
Owning a bank charter would allow Klarna to bring banking operations in-house, reducing its reliance on partner banks while expanding its payments, savings, credit, and merchant offerings.
Klarna joins a growing wave of fintechs pursuing US bank charters in 2026, reflecting an industry shift toward owning banking infrastructure instead of relying on sponsor banks.
Digital bank and BNPL provider Klarna is the latest fintech to apply for a US banking license. The company announced today that it has submitted applications to the Utah Department of Financial Institutions and the FDIC to establish Klarna Bank USA. The newly proposed bank will be a Utah-chartered industrial bank.
Klarna’s role as a bank is not new. The Sweden-based fintech has had a bank license in Europe since 2017, and while it has been providing bank services in the US since 2019, it does so through partner banks. Originally founded in 2005 as a buy now, pay later technology provider, Klarna now counts 30 million users in the US and over 119 million active global users.
Klarna said that obtaining its own bank charter will enable it to offer a broader suite of financial services directly to consumers while reducing its reliance on partner banks. The company also framed the move as a way to foster greater competition in the US banking market. “Banking is built on trust,” said Klarna Co-founder and CEO Sebastian Siemiatkowski. “We’ve seen firsthand the appetite for a fairer, more transparent approach in the US, and our own banking license is the natural next step, giving customers tools to borrow responsibly and build financial confidence, while bringing greater competition, innovation, and choice to consumers and merchants alike.”
Klarna Bank USA will operate as a subsidiary of Klarna and will have its own independent board, governance, and internal controls. Klarna has appointed Gary Harding, who served as CEO of both Milestone Bank and Prime Alliance Bank, to serve as President and CEO of Klarna Bank USA.
Having its own bank charter would allow Klarna Bank to bring its existing banking operations in-house. Klarna anticipates that removing its reliance on WebBank, its partner bank, will increase reliability across payments, savings, credit, and merchant services. Obtaining its own bank license will offer consumers more transparency and safety by bringing digital tools and traditional banking products in one place.
Klarna’s move to apply for a bank charter follows a flurry of applications in the first half of 2026. According to American Banker, two dozen neobanks, digital asset companies, lenders, investment firms, and payments providers have applied for or conditionally received bank charters so far this year.
Klarna’s application is another sign that fintechs are increasingly viewing bank charters as a strategic advantage instead of a regulatory burden. After years of relying on sponsor banks to offer deposit accounts and lending products, many fintechs have realized that owning the charter can provide greater control over product development, funding, compliance, and the customer experience. Even though the process to obtain a charter is costly and brings heightened regulatory oversight, it also gives companies like Klarna more flexibility to build long-term banking relationships with customers instead of depending on third-party partners.
MX launched a white-labeled conversational AI assistant that banks can embed into their digital banking platforms.
Unlike many consumer AI tools, MX’s assistant can both answer questions about a customer’s finances and initiate banking actions, such as opening new accounts.
The launch reflects a broader industry shift toward keeping AI-powered financial guidance inside banks’ own digital channels, helping institutions strengthen customer relationships.
Financial data platform MX is bringing conversational AI directly into digital banking. The company unveiled a white-labeled financial AI assistant that banks can deploy within their existing banking platforms, enabling customers to ask questions about their finances and take action without leaving the bank’s app.
The new assistant allows bank customers to engage with their finances by asking natural language questions in a conversational environment. The assistant maintains an active relationship with the customer by surfacing meaningful opportunities for financial wellness. Unlike many consumer AI assistants, MX’s tool leverages the financial institution’s existing transactional infrastructure to help customers complete tasks such as opening new accounts.
MX financial institution clients also stand to benefit from the new conversational AI tool. It leverages consumer-permissioned data to contextually recommend immediate financial opportunities and relevant products and services at the exact moment they are needed. Additionally, the increased engagement can help improve consumer trust and reduce strain on traditional customer service channels. Most importantly, it ensures that the bank maintains control over the customer relationship.
“Financial institutions are sitting on incredibly powerful data. They just haven’t had the right tools to act on it at the moment that matters,” said MX CEO and Founder Ryan Caldwell. “This assistant will change that. It’s designed to take complex back-end data and turn it into a clear signal: this customer needs something right now. Instead of a third party stepping in to capture that moment, the relationship stays with the financial institution that earned it, and the customer gets help from someone they already trust.”
From a compliance standpoint, MX’s AI assistant routes user interactions through a secure architecture that helps mitigate risk by validating conversations against the bank’s pre-configured policy rules. These guardrails ensure that consumers receive insights that are derived from their actual data while ensuring administrative visibility for internal risk and compliance teams. And because data stays within the financial institution’s and MX’s platform, it is not made available for third parties to train or retain the data used by the AI assistant.
Interestingly, MX’s launch comes the same week that ChatGPT made its financial aggregation tool more broadly available to its subscribers. The Plaid integration now works for both ChatGPT Pro users as well as ChatGPT Plus users. However, MX’s AI assistant differentiates itself from the LLM’s capabilities in that it is not limited to read-only. The company’s new tool leverages the financial institution’s existing transactional processes to allow users to take actions on their accounts.
MX is currently recruiting early launch partners and expects to roll the assistant out to a broader group of financial institutions following the initial pilot phase.
The first half of 2026 has made it clear that fintech and banking are entering a new phase. AI is changing how consumers interact with financial institutions, infrastructure is becoming a competitive advantage, and embedded finance continues to blur the lines between banks, fintechs, and technology companies.
What do these shifts mean for the rest of the year?
Jody Bhagat, President of North America, Engine by Starling
Tiffani Montez, Principal Analyst, EMARKETER
Jeremy Almond, CEO, Paystand
During this interactive discussion, we’ll explore questions such as:
Will AI assistants become the primary interface for banking?
Is owning financial infrastructure becoming more valuable than owning the customer relationship?
How are customer expectations around banking relationships changing?
What does the rise of invisible payments and embedded experiences mean for banks and fintechs?
Which trends are likely to define the second half of 2026?
Whether you work at a bank, credit union, fintech, or technology provider, you’ll leave with practical insights into where the industry is headed and what strategies are likely to matter most over the coming months.
Date: Wednesday, July 1, 2026 Time: 12:00 p.m. PDT
Reserve your spot today and join the conversation as we examine the forces shaping the future of financial services.
Fiserv has embedded Personetics’ AI platform into Experience Digital (XD).
The integration will help banks deliver real-time, personalized financial guidance to consumers and small businesses.
The move reflects the shift of AI from a standalone fintech tool to core digital banking infrastructure.
Banking and commerce technology provider Fiserv and cognitive banking platform Personetics are joining forces today. Fiserv has embedded Personetics’ platform within its Experience Digital (XD), a tool that gives banks and credit unions a new way to offer more personalized experiences to end users.
Embedding Personetics’ AI platform directly into Fiserv’s digital banking experience will allow Fiserv’s bank clients to act on data in real time, offering them the ability to deliver timely prompts, contextual guidance, and relevant offers within XD. The new capabilities will help end consumers manage their cash flow, build their savings, and make more informed financial decisions. It will offer small business users the ability to better manage working capital, anticipate needs, and respond more quickly to changes in their business.
“Financial institutions have no shortage of data, but many still struggle to translate that information into timely, relevant action,” said Personetics CEO Udi Ziv. “By embedding Personetics within Experience Digital, Fiserv is helping banks and credit unions deliver more human, personalized digital experiences that can improve money management for consumers and help small businesses operate with greater confidence.”
Personetics was founded in 2010 to bring cognitive banking tools to banks. The company sets itself apart with its AI-driven insights that help banks become a trusted advisor to their customers by bringing them personalized financial guidance. Personetics, a long-standing pioneer in AI-powered financial wellness, serves 150 million bank customers across 24 global markets each month.
Fiserv launched its XD platform in 2023 as the evolution of its digital banking offerings, bringing together account opening, money management, payments, small business banking, and fintech integrations in a unified digital experience. Natively embedding Personetics’ tools into XD will enable banks to create a more intuitive and relevant digital banking experience.
The move comes at a time when consumers are increasingly turning to AI-powered tools for financial guidance. Increasingly, fintechs and banks are adding AI-powered financial guidance as a built-in capability rather than an optional add-on. Embedding Personetics directly into XD will allow Fiserv to lower implementation barriers for clients, enabling banks to bring AI-driven money management tools to market more quickly.
“Consumers and small businesses increasingly expect digital banking experiences that are intuitive and responsive,” said Fiserv Chief Product Officer Vishal Dalal. “With this collaboration, our clients can use the data they already have to deliver timely guidance and personalized engagement that creates meaningful value for the consumers and businesses they serve.”
The announcement illustrates how AI is shifting from a standalone feature to core digital banking infrastructure. Rather than asking banks to select and integrate their own AI tools, platform providers like Fiserv are increasingly embedding those capabilities directly into their products, making advanced financial guidance accessible to a broader range of institutions.
Kentucky’s UK Credit Union is deploying IllumaSHIELD to strengthen fraud prevention and member authentication across its contact center and self-service channels.
IllumaSHIELD shifts away from security questions and passwords as banks and credit unions adopt voice biometrics to combat AI-powered fraud, including voice cloning and social engineering attacks.
Illuma’s technology continuously authenticates members as they speak, helping financial institutions reduce friction, shorten call times, and improve security without disrupting the customer experience.
Voice authentication solutions provider Illuma announced its latest partnership this month. The Texas-based company is teaming up with Kentucky-based UK Credit Union to help the credit union reduce fraud.
Specifically, UK Credit Union will implement IllumaSHIELD to bring authentication and fraud prevention capabilities to its contact center and self-service channels. IllumaSHIELD, which was unveiled at FinovateFall 2020, is the company’s voice security platform that leverages real-time voice authentication technology that passively verifies members as they speak, which reduces reliance on security questions and ultimately minimizes call handle time. Because the platform continuously evaluates risk throughout the interaction, it allows the credit union to step up authentication only when needed.
“AI-driven fraud is forcing financial institutions to rethink how they secure the voice channel,” said Illuma Founder and CEO Milind Borkar. “UK Credit Union is taking a forward-looking approach by adopting voice security that continuously verifies identity, blocks threats in real time, and improves both the member and agent experience—while eliminating friction from every interaction.”
As advances in generative AI have made it easier for fraudsters to clone voices, automate social engineering attacks, and bypass traditional knowledge-based authentication methods, financial institutions are having to secure voice interactions beyond asking for security questions and passwords. By providing continuous, biometric forms of identity verification, Illuma is authenticating users based on how they speak rather than what they know. Crucially, platforms like IllumaSHIELD aim to help banks and credit unions deliver this authentication without friction.
UK Credit Union anticipates that IllumaSHIELD will help it move beyond traditional knowledge-based authentication. “At UK Credit Union, protecting our members while delivering a seamless experience remains a top priority,” said UK Credit Union President and CEO Ryan Ross. “Partnering with Illuma allows us to modernize how we approach authentication and fraud prevention while creating a faster, more natural experience across our service channels.”
Headquartered in Plano, Texas, and founded in 2016, Illuma specializes in voice authentication solutions for credit unions and community banks. In addition to IllumaSHIELD, the company also offers advanced fraud prevention, adaptive multi-factor authentication (MFA), deepfake detection, and human-AI collaborative intelligence. The company most recently demoed at FinovateSpring 2025, where it won Best of Show for its deep fake detection technology.
For years, Finovate has helped fintechs connect with banks and other customers. This September, we’re launching a new event designed to help fintechs connect with the people who fund them.
Taking place on September 11 alongside FinovateFall in New York, IMPACT: Funders & Founders brings together fintech startups, scaleups, and investors for a full day of networking, content, meetings, and startup pitches. While FinovateFall is built around helping fintech companies meet potential customers, IMPACT is designed to help fintech founders build relationships with investors.
Who Should Attend?
IMPACT is for fintech founders and their teams and investors.
On the startup side, the event is geared toward fintech startups and scaleups, particularly companies that have raised up to a Series A round. On the investor side, we’re bringing together venture capital firms, angel investors, private equity investors, family offices, and limited partners.
Whether a company is actively fundraising or simply looking to build relationships for the future, IMPACT offers an opportunity to connect with investors who understand the fintech landscape.
Why Are We Creating IMPACT?
While investors have long attended Finovate events, we’ve seen growing demand for a dedicated event focused specifically on fundraising, investing, and startup growth.
IMPACT creates structured opportunities for founders and their teams and investors to connect through pre-arranged, one-on-one meetings, networking sessions, roundtable discussions, and live startup pitches featuring investor feedback and Q&A. The goal is to create an event where meaningful conversations and connections can happen more efficiently than through traditional networking alone.
What Can Attendees Expect?
The event features two dedicated content tracks.
The Investor Stage will explore topics such as AI in investment operations, emerging fund structures, venture capital trends, and the future of fintech investing.
The Founder & Startup Stage will focus on fundraising strategy, go-to-market planning, scaling a fintech company, building industry connections, and leveraging AI for growth.
In addition to attending content sessions, eligible startups can participate in the IMPACT Zone, a dedicated showcase area in Finovate’s Exhibit Hall where companies can meet investors and fellow founders throughout the day. Startups raising pre-seed through Series A funding can also apply to deliver a four-minute pitch in front of investors.
How Is IMPACT Different from FinovateFall?
While IMPACT takes place alongside FinovateFall, the two events serve different purposes.
FinovateFall helps fintechs connect with buyers and partners through live demos and networking. IMPACT helps fintechs connect with investors and advisors who can help fuel their next stage of growth.
Together, the events support fintech companies throughout their journey in everything from raising capital to winning customers. Whether you’re a founder seeking your next investor, a startup executive looking to expand your network, or an investor searching for the next breakout fintech company, IMPACT offers a new way to connect with the people shaping the future of financial services.
If you’d like to register or learn more, check out our website to learn about opportunities that best fit your needs.
We have officially entered the final week of June, which marks the ending of the first half of 2026. As we close out the first six months of this year, here’s a look at the top news headlines for this week. We’ll continue to add more announcements as the week progresses.
Payments
Nuvionteams with Visa Direct to strengthen real-time global payout capabilities for businesses operating across borders.
Bankaktiebolaget Nordiska (Nordiska) partnered with Finastra’s Swift Service Bureau to enhance access to the global Swift network and Sweden’s central payment rails.
E-commerce, banking, and payments ecosystem Bir teams up with payments platform Paysend to launch international money transfers in Azerbaijan.
Wise has acquired expat resource Expatica, gaining access to a website that attracted more than 7 million visits in 2025 from people researching and navigating life abroad.
The deal gives Wise an earlier touchpoint with prospective customers, allowing it to build brand awareness and trust before consumers choose a bank, payments provider, or money transfer service.
Wise plans to expand Expatica’s content and geographic reach, strengthening its position among the growing global population of expats and internationally mobile consumers.
Cross-border payments fintech Wiseannounced this week that it has acquired Expatica, an online resource for people living and working abroad. The move places Wise front and center among one of its most important customer groups, expats.
Expatica was founded in 2000 to provide local guidance for people living internationally. The company’s website serves as a directory that covers topics such as relocation, housing, finance, lifestyle, healthcare, and immigration. The website reached more than 7 million visits in 2025, with its largest audiences coming from France, Germany, Portugal, and Spain.
According to the UN, 304 million people (3.7% of the world’s population) were international migrants in 2024. With Expatica serving as a long-standing expert in the field, the acquisition will help Wise reach prospective expats earlier in their relocation journey, increasing the company’s visibility among a broader international audience.
By acquiring Expatica, Wise gains access to consumers when they are researching a move abroad—often before they have selected a bank, payments provider, or money transfer service. That early engagement could help Wise build brand awareness and trust long before a customer needs to move money internationally.
“Expatica has spent years helping people make sense of life abroad with practical, locally relevant guidance. That makes it a strong fit for Wise, because we already support millions of people whose lives span borders,” said Wise Head of Owned Sites Danny Butler. “When people are planning, moving and settling into life abroad, money is a big part of that experience—from getting paid to sending, spending and managing money across borders. Wise is built for those moments.”
Wise plans to maintain and augment Expatica’s website, with investments planned to expand the company’s content, local coverage, markets, and languages over time. As Expatica’s users leverage its resources to navigate life in a new country, Wise wants to become a familiar and relevant choice for expats who need to manage money across borders.
Wise was founded in 2011 under the name TransferWise to facilitate cross-border payments while bringing transparency to the fees involved. The company serves 19 million active customers worldwide, processing over $240 billion in cross-border transactions.
For years, bank-fintech relationships often followed a predictable path. Banks identified promising startups, tested their technology, and viewed acquisition as the ultimate endgame. Today, that dynamic is changing.
At FinovateSpring 2026, I sat down with Deepa Chatterjee, SVP of Business Development and Go-to-Market for Small Business Banking at U.S. Bank, to discuss how bank-fintech partnerships are evolving, where banks are competing with digital-first challengers, and what the future of small business banking looks like.
One of the most interesting takeaways from our conversation was how dramatically the relationship between banks and fintechs has changed. While banks once viewed fintech partnerships as potential acquisition opportunities, many are now embracing deeper, longer-term collaborations. “The way that we worked with fintechs was primarily thinking of potentially acquiring them,” said Deepa. “Now that tha markets have changed we are far more likely to work and partner with fintechs in a much deeper way, and so ownership is not necessarily on the table.”
Deepa Chatterjee is SVP of Business Development and Go-to-Market for Small Business Banking at U.S. Bank. She leads business development, partnerships, sales enablement, product marketing, data insights, and automation initiatives for the bank’s small business segment. Before joining U.S. Bank, Chatterjee held leadership roles at Dayforce and Oportun and spent more than a decade at American Express in strategy, marketing, and business development positions. She holds a bachelor’s degree in economics from Barnard College at Columbia University and an MBA from the Yale School of Management.
U.S. Bancorp, the parent company of U.S. Bank, is one of the largest banking institutions in the United States, serving millions of consumer, business, commercial, and institutional clients. The bank offers a broad range of financial services, including business banking, payments, treasury management, merchant acquiring through Elavon, lending, and wealth management solutions. U.S. Bank has increasingly expanded its digital capabilities through fintech partnerships and embedded financial services designed to help small businesses streamline their financial operations.
Coinbase is evolving beyond crypto into an “everything exchange,” adding AI-powered advice, agentic trading, tokenized stocks, and expanded credit offerings in a bid to become consumers’ primary financial platform.
The new launches highlight two major fintech trends: AI moving from financial guidance to autonomous action, and the continued blurring of lines between banks, brokerages, fintechs, and crypto platforms.
By combining investing, lending, payments, wealth management, and AI tools into a single experience, Coinbase is betting that convenience and integration will define the next generation of financial services.
Crypto exchange platform Coinbase wants users to think of it as much more than a cryptocurrency exchange. This week, the company unveiled a series of new products as part of its effort to become a primary financial platform for consumers.
Since it was founded in 2012, the company has been slowly building out a comprehensive banking platform. What started as a crypto wallet has evolved into a full service financial platform with debit and credit cards, prediction markets, derivatives, crypto-backed lending, and more.
“Coinbase is building the future of finance, where you can manage your money with just one interface, and one login,” the company said in its blog post announcement. “We’re saying “no” to financial fragmentation, and the new products we’re introducing today take us several steps closer to that future.”
Here’s a rundown of the top five new tools and features Coinbase is unveiling this week and why each matters:
Coinbase advisor
Coinbase has launched an AI financial advisor to provide personalized financial guidance based on a customer’s holdings and financial situation. While many fintechs are hesitant to give financial advice because of the regulatory requirements, Coinbase registered with the SEC as a Registered Investment Advisor and with the CFTC and NFA as a Commodity Trading Advisor.
Why it matters: The move places pressure on both traditional financial institutions and fintechs offering robo-advisory technology to offer more sophisticated, real-time financial guidance at a lower cost. Offering AI-powered financial advice caters to consumers of all levels because it allows them to communicate using natural language, comes at a lower cost, and does not require the consumer to change their existing habits or switch apps. When compared to traditional wealth management, which has historically been reserved for affluent customers, the advisor tools will have a wider reach and be a valuable tool for customer retention.
Agentic trading
Customers can deploy AI agents to execute personalized trading strategies on their behalf while maintaining ultimate control over the account. Investors can confine their agent to an isolated sub-account and set limits around capital allocation, asset permissions, and trade sizes. Coinbase joins Robinhood, which launched agentic trading earlier this month, in pioneering this feature.
Why it matters: With agentic tools, AI implementation makes the leap from informing decisions to taking action. Having an agent move funds on an investor’s behalf can help with treasury management, cash flow management, and micro-investing decisions that would be too tedious for human investors.
Expanded stock and options trading
In a move that continues to expand Coinbase beyond crypto, the company announced broader access to stock trading and options trading. The company first unveiled stock trading in December 2025 and expanded it to all US users in February of this year. This week’s announcement highlights the next phase of Coinbase’s strategy that will focus on transforming it into a full-service financial platform.
Why it matters: Even though stock trading is not new for Coinbase, it highlights the company’s new position as a universal investment platform. Similar to how Robinhood expanded into banking and SoFi branched out into investing, Coinbase’s move to broaden its offerings will make the company a more holistic banking platform. The move is also an example of how lines across financial services are beginning to blur. The distinction between crypto platforms, brokerages, and banks is increasingly disappearing.
Tokenized US stocks
Coinbase plans to enable non-US customers to trade tokenized US equities around the clock. Tokenized stocks are backed 1:1 by the underlying asset, representing true equity ownership, including dividend payouts and complete shareholder rights. Additionally, investors will be able to lend their shares to earn yield, use them as collateral for a loan, or even gift them directly to someone else.
Why it matters: Tokenized trading offers 24/7 trading, potentially faster settlement, and broader global access to US markets. This changes the traditional models of limited trading hours, clearinghouses, and custodians that have dictated the legacy stock market since its inception.
Expanded access to Coinbase One Card
The company expanded USDC-backed access to the Coinbase One Card, a card built for users who are generally overlooked by traditional credit bureaus. The update allows users who aren’t approved for a traditional line of credit to secure a Coinbase One Card using USDC as collateral. The card offers Bitcoin rewards on everyday purchases while paying rewards on the underlying USDC deposit every week.
Why it matters: Offering a credit builder card allows Coinbase to tap into a new set of users who have historically been ignored by traditional financial institutions. And because Coinbase’s credit builder card still pays out rewards and offers additional benefits like the new Travel Portal that provides cardholders access to all of the same travel protections and benefits offered through the American Express Network.
From the looks of these new products and tools, it appears that Coinbase is making a bid to become a full-service financial institution without calling itself a bank. Combining investing, lending, payments, wealth management, and AI-powered tools into a single experience will allow Coinbase to provide a more unified experience to customers that care less about traditional financial categories and more about convenience. As the lines between banks, brokerages, fintechs, and crypto platforms continue to blur, Coinbase’s latest moves offer a glimpse into what the next generation of financial services may look like.