FinovateSpring 2014 – visibleequity

FinovateSpring 2014 – visibleequity

How they describe themselves: Visible Equity provides analytics software to financial institutions for use in warehousing disparate data, analyzing credit risk and lending opportunities, measuring expected losses, and testing for potential fair-lending discrimination.

How they describe their product/innovation: Fair Lending laws have been around for decades, but more sophisticated Fair Lending analysis has recently become a hot-button issue and point of emphasis from financial regulators.

Our product uses intuitive design and advanced statistical modeling to determine whether discrimination or “disparate impact” is potentially occurring in marketing activities, during the loan application process, with pricing and add-on products, and with charge-off and collection practices.

It is unlikely that a financial institution is ever knowingly discriminating, but now with the use of Fair Lending Analytics, institutions can mathematically prove they are compliant and treating all borrowers fairly.

Product Distribution Strategy: Direct to Business (B2B)

Contacts:

Bus. Dev.: David Gilbert, COO, [email protected], 888-409-1560
Press & Sales: Matthew Court, VP Sales & Marketing, [email protected],
888-409-1560

FinovateSpring 2014 – Vorstack

FinovateSpring 2014 – Vorstack

How they describe themselves: Vorstack is a venture-backed company founded and staffed by security and legal experts. Vorstack offers solutions that provide automation and control over threat and fraud intelligence sharing, resulting in substantially reduced time to discover, validate, contain, and remediate threats. Vorstack is deployed with leading companies in the e-commerce and technology markets and is launching in the financial services market in April 2014.

How they describe their product/innovation: Vorstack’s VFS solution for financial services is a distributed analytics and correlation platform for multi-party coordinated cyber defense. We provide the control and auditability necessary to satisfy strict domestic and international privacy, anonymity, and compliance requirements. Our solution natively operates across emerging threat-sharing standards like STIX/TAXII to enable organizations to leverage public-private partnerships and ISACS to promote intelligence sharing. Vorstack’s solution provides a configurable channel for human intelligence collaboration complementing real-time data intelligence analysis.

Product Distribution Strategy: Direct to Business (B2B), licensed

Contacts:

Bus. Dev. & Press: Mark Manning, VP Technical Services, 408-420-3883
Sales: Paul McGowan, VP Sales, 516-319-4109

FinovateSpring 2014 – WePay

FinovateSpring 2014 – WePay

How they describe themselves: WePay is a payment company built for platform businesses such as online marketplaces, crowdfunding websites, and small business software companies. WePay offers their platform customers complete protection from fraud risk and compliance burdens while delivering the flexibility to create seamless user experiences.

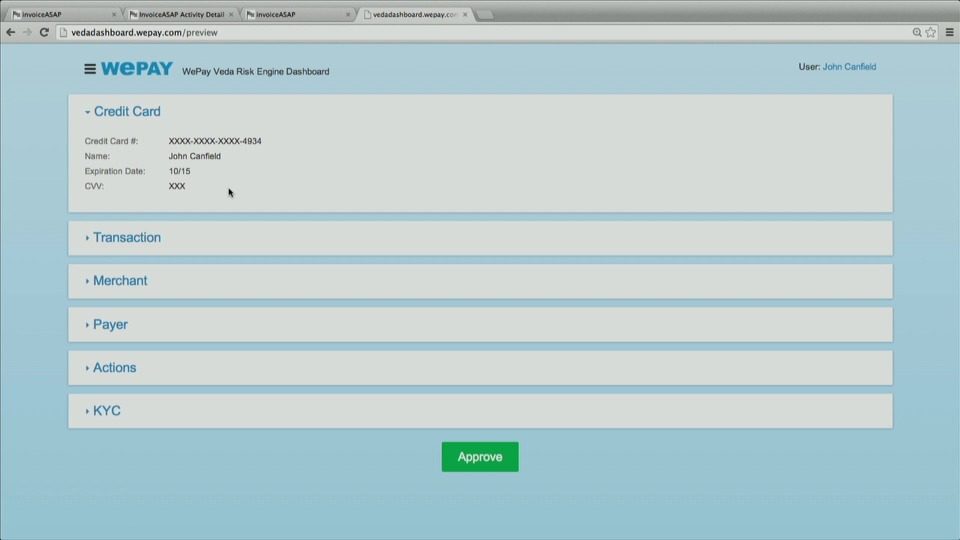
How they describe their product/innovation: Only WePay’s patent-pending risk engine technology, Veda, stitches together a variety of novel data sources to better understand a platform’s users. To fight fraud, Veda combines proprietary data from platforms, data from WePay’s own transactional graph, and social data from sources such as Facebook, Twitter, and Yelp.

Product Distribution Strategy: Direct to Business (B2B), through other fintech companies and platforms

Contacts:

Bus. Dev. & Sales: Tyler Gaffney, VP Sales, [email protected]
Press: April Rassa, Director of Communications & Content, [email protected]

FinovateSpring 2014 – Wipit

FinovateSpring 2014 – Wipit

How they describe themselves: Wipit provides integrated mobile payments, financial services, and prepaid debit card convenience to underbanked consumers. The company has partnered with Sprint, a leading wireless service provider, to launch the revolutionary, co-branded Boost Mobile Wallet and Sprint Money Express mobile wallet service. Wipit has commercial partnerships with and has been invested in by Euronet Worldwide (NASDAQ: EEFT), H&R Block (NYSE: HRB), and Core Innovation Capital. For more information, visit www.wipit.me.

How they describe their product/innovation: Boost Mobile Wallet lets millions of prepaid wireless customers load cash to their mobile wallet account, then use the funds to send international money transfers, pay bills, or top-up their Boost Mobile phone − all from the convenience of Wipit’s Mobile Wallet app on their Android smartphone or iPhone. Customers are also provided with a convenient, cost-saving alternative to retail check cashing via Wipit’s in-app Quick Check service. For customers that prefer the convenience of card payments, Boost Mobile Wallet includes a personalized, linked Visa prepaid card that can be used for ATM withdrawals and Visa purchases.

Product Distribution Strategy: Direct to Consumer (B2C), through other fintech companies and platforms

Contacts:

Bus. Dev.: Jakob Wamser, Director of Bus. Dev., [email protected], 314-397-5253
Press: Vikram Kanodia, EVP Strategy, [email protected], 626-394-3996

FinovateSpring 2014 – Yseop

FinovateSpring 2014 – Yseop

How they describe themselves: Yseop is a Smart Machine based on Artificial Intelligence (AI) and Natural Language Generation (NLG), which writes intelligent text just like a human being, but at a speed of thousands of pages per second. Yseop boosts productivity in the financial industry, drives sales, and transforms financial advisors into instant experts without additional training. Yseop turns Big Data into comments and actionable insights by instantly writing any type of report (such as executive summaries, fact sheets, stock profiles, investment, earnings reports, etc.) in real time and in multiple languages (currently in English, Spanish, French, German, etc.).

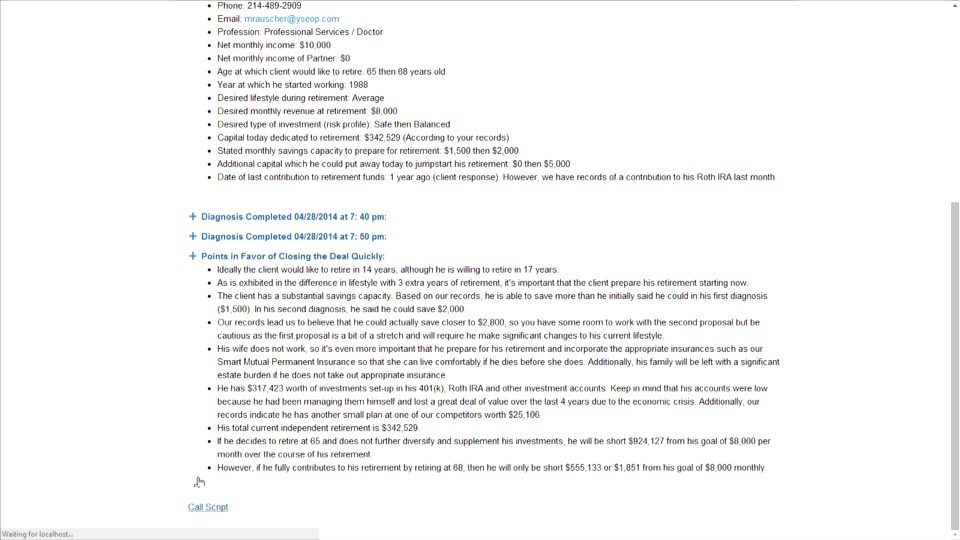
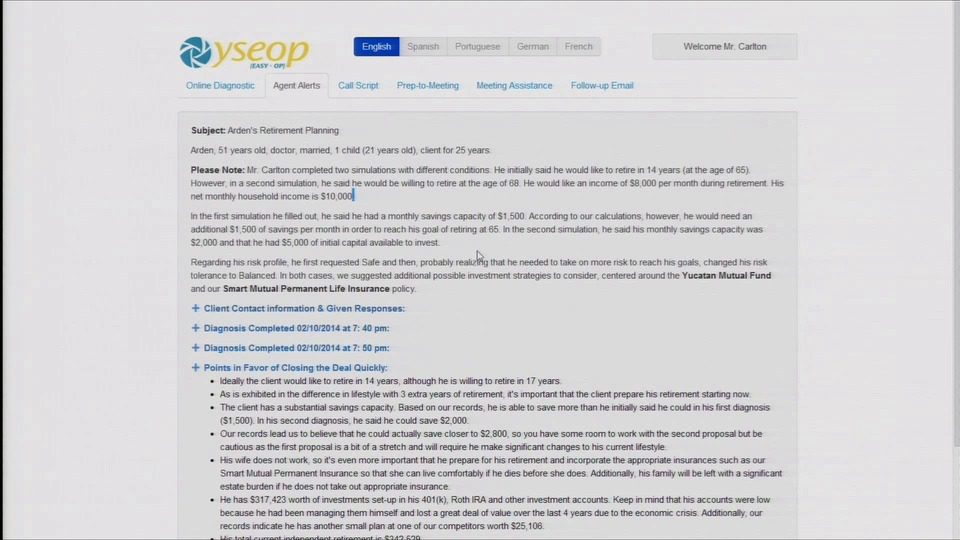
How they describe their product/innovation: Yseop Sales Force Productivity Suite (YSF) and its email writing application, called “YseMail” (“Easy-Mail”), is an integrated sales performance boosting solution to be plugged into a CRM, which supports the financial advisor throughout the sales cycle. YSF analyzes customer data, dialogs intelligently with the advisor or customer to gather contextual data, and produces written conclusions such as pre- and post-meeting summaries, personalized marketing communications, and prep-to-meeting documents in less than a second.

Product Distribution Strategy: Direct to Business (B2B), through financial institutions

Contacts:

Bus. Dev. & Sales: Matthew Kropp, Director of Sales & Marketing, [email protected],
214-393-9719
Press: Arden Manning, Director of Communications, [email protected], 646-480-0633

FinovateSpring 2014 – ZenPayroll

FinovateSpring 2014 – ZenPayroll

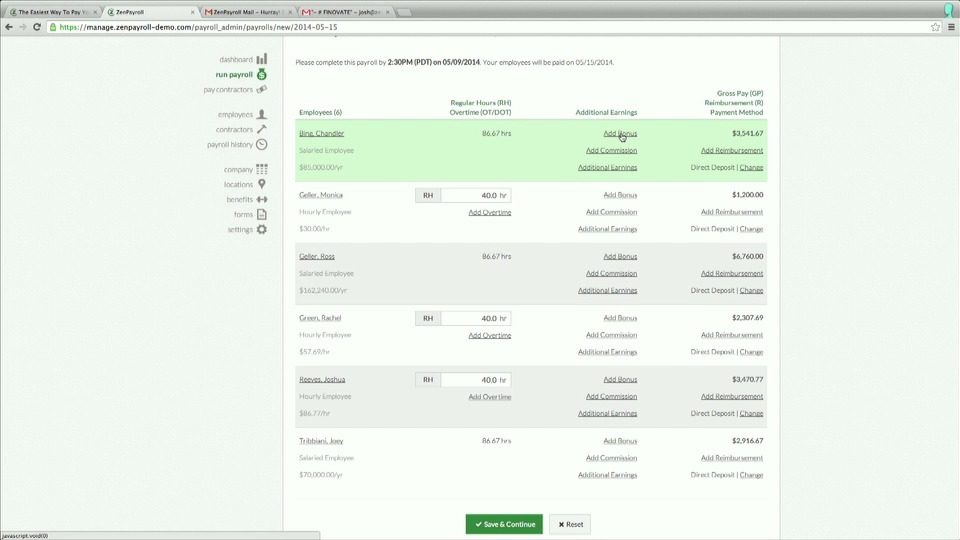
How they describe themselves: ZenPayroll is modern, delightful payroll. Our mission is to make payroll as simple and intuitive as possible using the principles of modern software. The payroll market today is filled with unnecessary layers of complexity, manual tasks, and numerous fees – we built ZenPayroll to fix this. Customers can run payroll in minutes from any connected device. All government payroll reporting is done automatically and paperlessly, providing the easiest way for business owners to manage payroll taxes and compliance. We’re processing half a billion dollars in annual payroll for small businesses of all kinds.

How they describe their product/innovation: Payday is a special moment; it’s a chance for business owners to thank people for their contributions and for employees to feel appreciated. Compensation today is an impersonal, transactional event. Our team is unearthing the human side of compensation currently buried under layers of complexity and government bureaucracy. Payroll should be about people, not payments. At FinovateSpring, ZenPayroll is unveiling how payroll software can empower employees and help business owners build stronger teams.

Product Distribution Strategy: Direct to Business (B2B), through financial institutions, through other fintech companies and platforms

Contacts:

Bus. Dev.: Jaleh Rezaei, Partnerships, [email protected]
Press: Steffi Wu, PR, [email protected]
Sales: Saad Shahzad, Sales, [email protected]

FinovateSpring 2014 – Zumigo

FinovateSpring 2014 – Zumigo

How they describe themselves: Zumigo leverages mobile network data to secure financial transactions, identify devices, protect logons with precision, identify device owners, and enable marketing. Financial institutions can leverage Zumigo’s global solutions to verify that customers are present at a merchant or in proximity to a transacting PC when their debit or credit card is used. Zumigo can also authenticate devices to prevent attempted account takeovers with stolen credentials and even match device ownership records with account records. Marketing programs can be enhanced with timely, location-specific offers driven with Zumigo’s data.

How they describe their product/innovation: Zumigo is demonstrating a revolutionary new way to simplify the account-opening funnel and reduce shopping cart abandonment. Financial institutions and eCommerce companies can integrate this solution to existing new-customer flows on websites and mobile applications. By leveraging its access to mobile networks and related account data, Zumigo can prepopulate forms with a customer’s name, address, phone number, and even tokenized credit card data. Now a customer’s mobile phone can provide the data needed to streamline, reduce risk, and secure any transaction.

Product Distribution Strategy: Direct to Business (B2B), through other fintech companies and platforms

Contacts:

Bus. Dev. & Sales: [email protected]
Press: [email protected]

FinovateEurope 2014 – vaamo

FinovateEurope 2014 – vaamo

How they describe themselves: vaamo is a financial services startup that will fundamentally change the way individuals save and invest. We utilise a mobile optimised web application to provide individuals with unprecedented easy access to a clever investment solution that is superior in terms of performance, risk, and costs compared to most investment products distributed to private clients today. The founding team of vaamo consists of former strategy consultants, one investment banker, and one university professor. All combined makes more than 30 years of practical financial services experience with focal areas in retail and private banking as well as asset and wealth management.

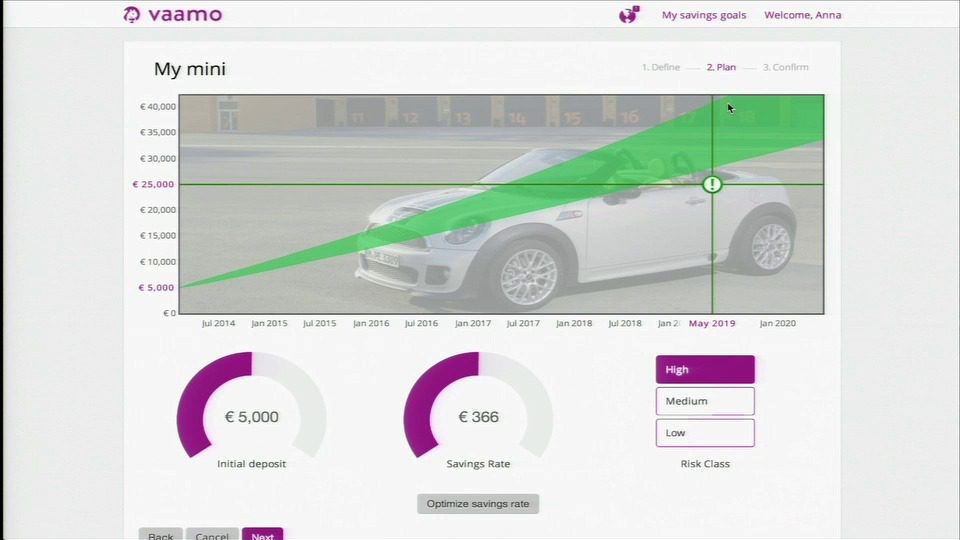
How they describe their product/innovation: Our web application is designed to provide private individuals with easy to use and intuitive access to savings and investments. A key differentiator is the focus on customers’ personal financial goals instead of financial products, the strict limitation of available financial products to only one investment solution, as well as the mobile optimisation. Customers can set up personal financial goals (e.g. retirement, new home), and define for each goal the amount they want to save by when, how much they want to save today and regularly, and which risk they are willing to take. Inputs are instantaneously illustrated using a chart that projects future contributions, performance, and risk, enabling customers to understand the impact of each input.

Product Distribution Strategy: Direct to Consumer (B2C)

Contacts:

Bus. Dev.: Dr. Thomas Bloch, [email protected],
+49 163 362 3822 &
Dr. Oliver Vins, [email protected], +49 151 681 681 65

FinovateEurope 2014 – Momentum

FinovateEurope 2014 – Momentum

How they describe themselves: Blue Speck Financial owns and operates Momentum, a financial services technology and marketing firm which is directly authorised and regulated by the Financial Conduct Authority.

Momentum is a free to access website that helps people make choices over their financial future, whether they’ve got £5 or £50 million, by delivering information, products, and access to advice relevant to their circumstances. Momentum uses accessible, innovative technology to put the consumer at the centre of their financial world.Momentum and its Money Hub technology are currently only available for UK consumers.

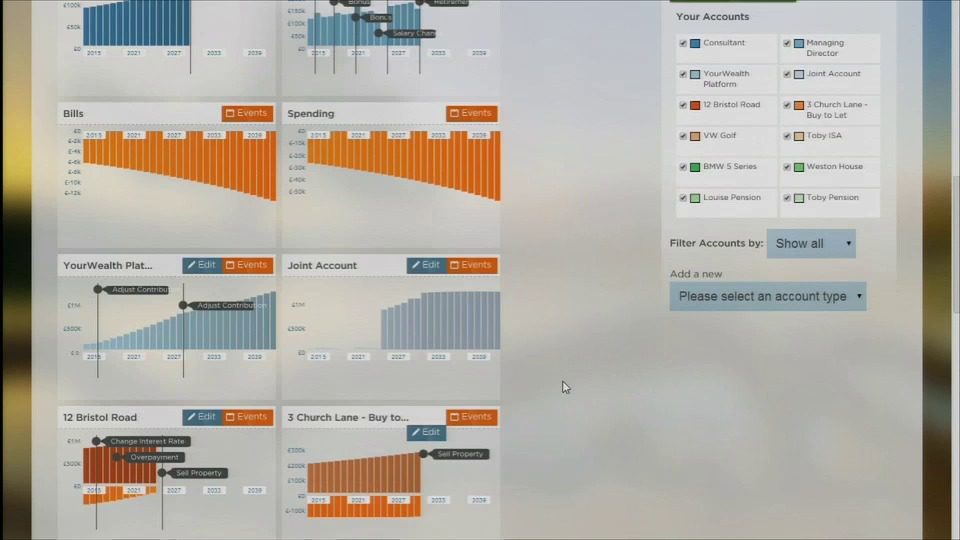
How they describe their product/innovation: Momentum’s Money Hub technology is one of the world’s most powerful personal finance tools and is available via mobile, tablet and desktop devices. It brings together a user’s entire financial world and incorporates the ability to aggregate accounts, budget, track and plan scenarios for the future as well as access to financial products and advice.

Money Hub gives users total control, allowing them to connect directly with a product provider or financial adviser and select which areas of their financial universe they wish to share with them. We believe Money Hub will revolutionise the world of personal finance.

Product Distribution Strategy: Direct to Consumer (B2C), Direct to Business (B2B), through financial institutions, licensed

Contacts:

Bus. Dev. & Sales: Jamie Donald, Senior Commercial Manager, 0117 3790050 &
Toby Hughes, CEO, 0117 3790050
Press: Sophie Lilley, Director and Partner, Lansons Communications, [email protected] & Lucia Harris, Digital Content Executive, 0117 3790050

FinovateEurope 2014 – Yseop

FinovateEurope 2014 – Yseop

How they describe themselves: Yseop is artificial intelligence software, which writes (and speaks) intelligent text, just like a human being, but at a speed of thousands of pages per second. Yseop revolutionizes the financial industry by boosting productivity, driving sales and turning each financial advisor into an expert without additional training.

How they describe their product/innovation: Yseop Sales Force Productivity Suite (YSF) and its email writing application, called “YseMail” (pronounced “Easy-Mail”), is an integrated sales performance boosting solution to be plugged into a CRM, which supports the financial advisor throughout the sales cycle. YSF analyzes customer data, dialogs intelligently with the financial advisor or customer to gather contextual data and produces written conclusions in seconds, including pre- and post-meeting summaries, personalized marketing communications and prep-to-meeting documents. YSF has demonstrated an improvement in sales productivity of 20% overnight.

Product Distribution Strategy: Direct to Business (B2B), through other fintech companies

Contacts:

Bus. Dev. & Sales: Matt Rauscher, Consultant, [email protected], +44 (0)208 123 5707
Press: Arden Manning, Communications Director, [email protected], +44 (0)775 796 0633

FinovateAsia 2013 – whitelabel

FinovateAsia 2013 – whitelabel

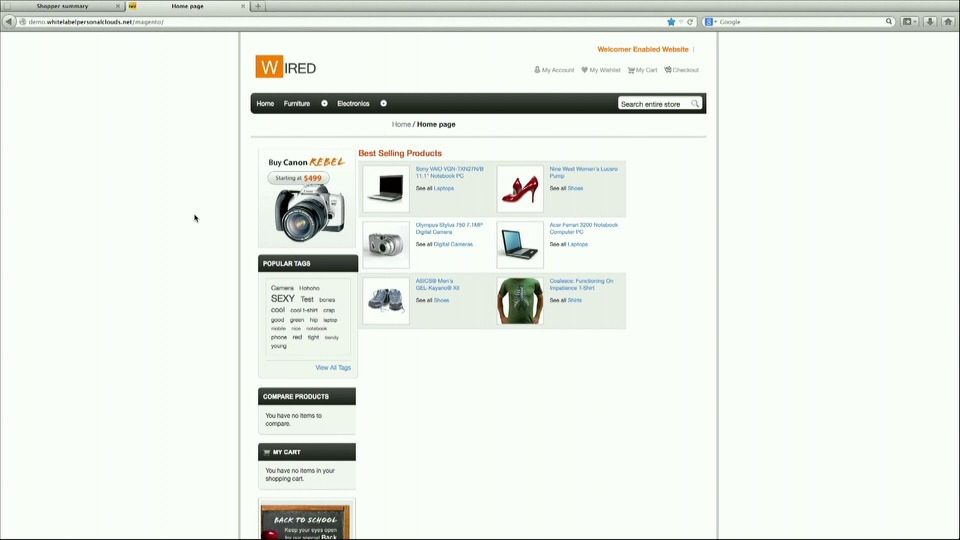
How they describe themselves: People provide the same personal information over and over to different websites. White Label Personal Clouds (WLPC) provides the software and systems to enable the transfer of personal information from one website to another website. This creates a better customer experience to improve acquisition and loyalty. The technology works via personally controlled data space residing on a person’s device or through data stored with an organization. This infrastructure also provides an alternative way to achieve many identity tasks. Participants are incentivized to exchange data through an associated financial system.

How they describe their product/innovation: WLPC’s first product is Welcomer. Welcomer will initially be focused towards ecommerce sites and the technology is intended across a range of different segments. Welcomer removes the need for websites to have usercodes/passwords to identify returning customers. Websites that deploy Welcomer can – with the person’s permission – allow the person to move personal data securely between websites. This includes personal details such as name and address, preferences such as clothing size or preferred seat and also a person’s cards and accounts.

Product Distribution Strategy: Direct to Consumer (B2C), Direct to Business (B2B), through financial institutions, and through other fintech companies and platforms

Contacts:

Bus. Dev., Press & Sales: Rory Ford, Product Manager, [email protected], +61423168914

FinovateAsia 2013 – Yodlee

FinovateAsia 2013 – Yodlee

How they describe themselves: Yodlee is the platform for financial innovation. With the largest collection of consumer and small business transactional data on the planet, Yodlee powers the next generation of digital services, from personal financial management (PFM) to digital wallets, and so much more.

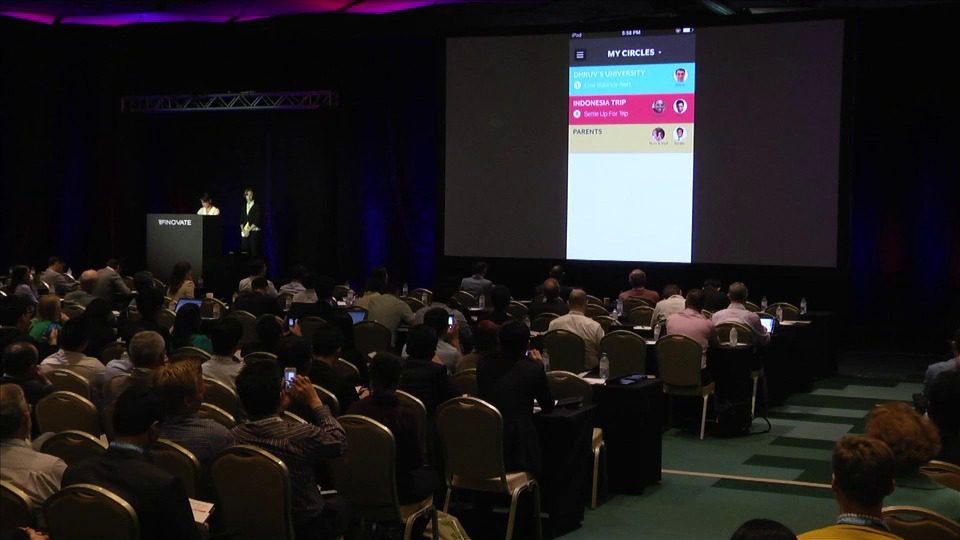
How they describe their product/innovation: Most people have multiple “shared finances” in their life. Spouses. Children. Elderly parents. Accountants. Advisors. Friends. So Yodlee is introducing Tandem – the first collaborative financial app that lets users securely establish and manage their social financial relationships. From tagging transactions, to sharing documents, to sending money, to collaborating with advisors and accountants, Tandem gives users the power to establish financial circles based on levels of trust and account sharing access. And Tandem gives financial institutions the ultimate mobile banking app.

Product Distribution Strategy: Direct to Business (B2B), through financial institutions & through other fintech companies and platforms

Contacts:

Bus. Dev.: Jason O’Shaughnessy, International VP, [email protected], +44 20 7664 8845
Press: Melanie Flanigan, Sr. Marketing Director, [email protected], +1-650-980-3707
Sales: Dhruv Manga, Regional Sales Director, [email protected], +91 120 436 6081