This site is operated by a business or businesses owned by Informa PLC and all copyright resides with them. Informa PLC's registered office is 5 Howick Place, London SW1P 1WG. Registered in England and Wales. Number 8860726.
Finovate Blog
Tracking fintech, banking & financial services innovations since 1994
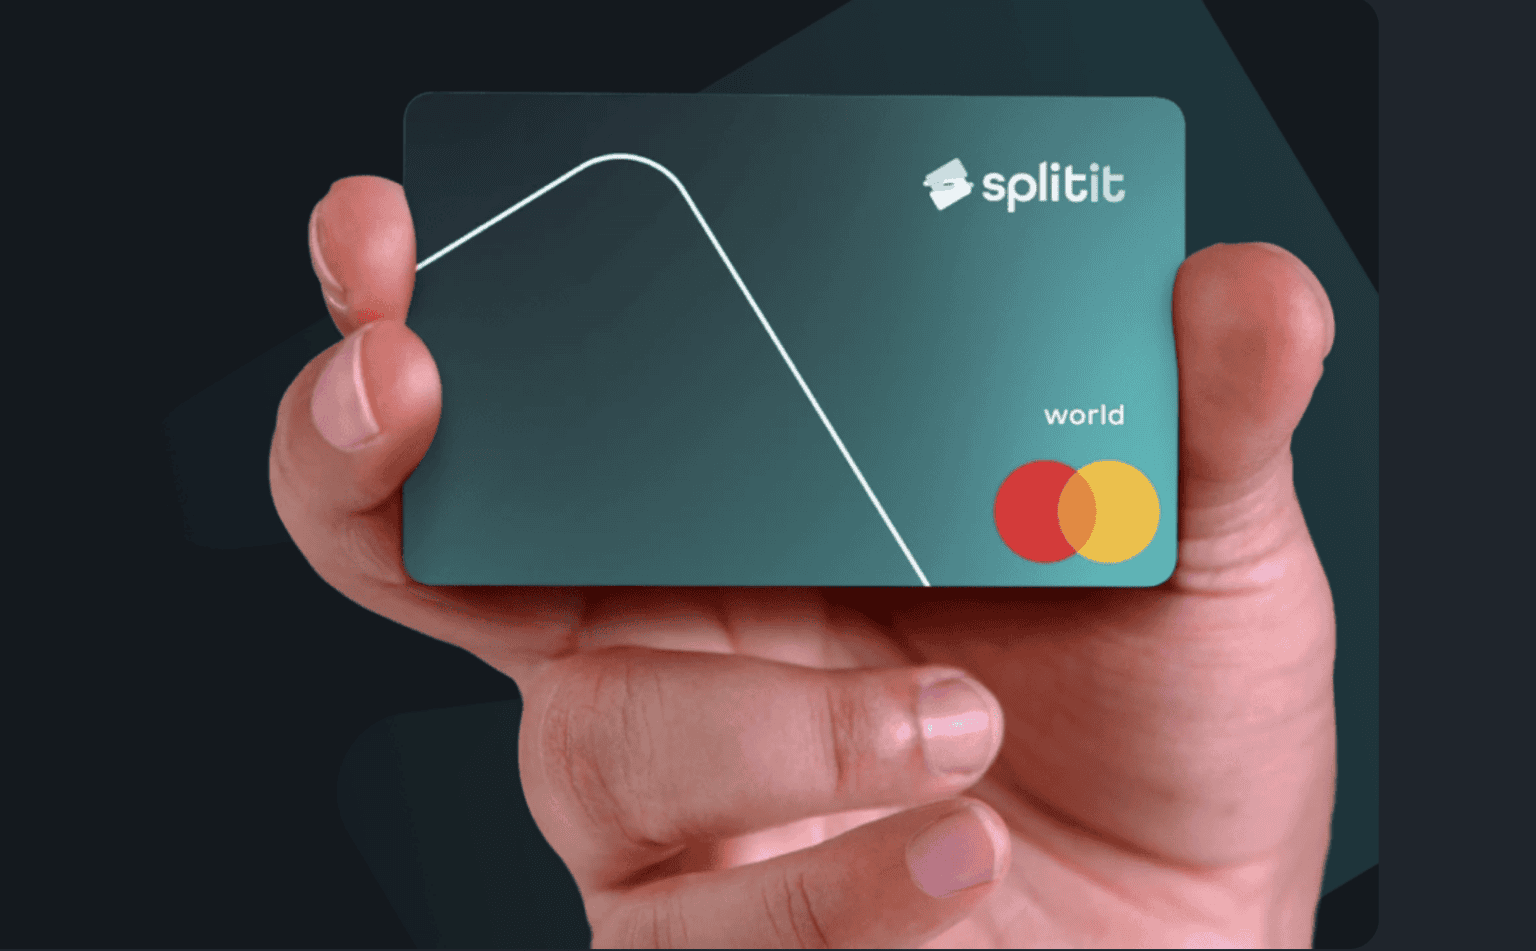
Splitit unveiled plans for the Splitit World Mastercard, a white-label credit card that combines traditional credit card functionality with flexible installment payments.
The card allows consumers to automatically split purchases above a customizable spending threshold into monthly installments, with the option to adjust repayment plans.
The offering, expected to become available in early 2027, will help mid-sized banks and credit unions compete with BNPL providers while maintaining ownership of their customer relationships.
Georgia-based BNPL solutions provider Splititunveiled plans for the Splitit World Mastercard, a new white-label credit card that offers the flexibility of installment plans.
Shoppers can use the new credit card to make everyday purchases and use the app to set their own spending threshold. Any purchases over that amount can be automatically split into monthly installments to repay. Throughout the month, cardholders can switch a purchase to pay-in-full or they can adjust the installment plan before the statement is due.
Splitit World Mastercard combines Mastercard’s network infrastructure with Splitit’s installment technology. Because banks bring their own customers and brand, the new card offering allows banks to expand their lending and payment offerings to provide greater choice and flexibility while maintaining ownership of the customer relationships.
“The Splitit World Mastercard is a new type of credit card built for banks and credit unions that resembles the simplicity of debit for consumers and pairs it with the flexibility of installments,” said Splitit CEO Nandan Sheth. “Banks already have the relationship, the brand and the primary account. What many of them lack is a way to offer installment plans at the point of purchase without having to build a lending business from scratch. Our white-label card gives them that, under their own name.”
Splitit plans to begin shipping its World Mastercard to financial institutions in early 2027.
Splitit was founded in 2012, went public in 2019, and went private again in 2023 after it was acquired by Motive Partners. With an overall goal to simplify flexible payments, the company launched a partner program called the Agentic Commerce Partner Program in 2025. The new initiative allows autonomous shopping agents to make payments using card-linked installments.
The launch marks an interesting evolution for Splitit, which, for 16 years, has focused on enabling installment payments using consumers’ existing credit cards rather than issuing new credit products. Bringing installment functionality directly into a white-label credit card gives mid-sized banks and credit unions a way to compete with standalone BNPL providers without building their own installment infrastructure.
Notably, the approach also allows financial institutions to retain ownership of the customer relationship rather than ceding that engagement to third-party financing providers. This ownership question has become a hot topic lately, especially as consumers have started to turn to AI tools or other third party players to address their financial needs.
A partnership between BMO Financial Group and financial education platform Zogo will help boost financial literacy among young adults in Canada.
The partnership targets young adults between the ages of 18 and 24 and provides practical lessons and quizzes to help users build financial knowledge that will have real-world applications in their lives.
Founded in 2018 and headquartered in Austin, Texas, Zogo won Best of Show in its Finovate debut at FinovateFall 2019.
BMO Financial Group announced this week the launch of Zogo in Canada. The new offering brings Zogo’s interactive, gamified financial literacy experience to eligible students throughout Canada. Designed for young adults aged 18 to 24, the partnership will help them develop their financial knowledge in order to make informed financial decisions throughout their lives.
Zogo features practical lessons and quizzes to help users learn about budgeting, saving, credit, and money management. Through the Zogo mobile app, BMO clients can complete financial lessons, earn points, and redeem rewards while building practical skills they can apply to their everyday lives.
“Bringing this experience to Canada alongside BMO makes this partnership especially meaningful for us,” Zogo President Ben Brooks said. “BMO’s commitment to helping the next generation make financial progress is evident in the care its team has put into this launch. Together, we’re making financial education more accessible, engaging and rewarding for Canadian students, with practical skills they can carry well beyond the classroom.”
BMO’s partnership with Zogo is part of the banking group’s drive to make financial literacy more accessible. BMO recently announced a strategic partnership with MoneyPrep, which provides teachers with free access to financial literacy lessons and tools designed for elementary school-aged children. The first financial institution to bring Zogo to Canada, BMO sees the partnership as an extension of its support for financial literacy across all stages of learning, from the classroom through adulthood.
“Building financial knowledge and confidence early can help establish the foundation for lifelong financial well-being and real financial progress,” said Sumit Sarkar, Head of Everyday Banking Products for BMO. “With Zogo, BMO is making financial education more engaging, accessible, and relevant for young Canadians, empowering them to navigate important financial decisions at every stage of life.”
The eighth-largest bank in North America by assets, BMO Financial Group has total assets of $1.5 trillion as of July 2026. The firm offers a wide range of financial services, including personal and commercial banking, wealth management, and investment banking across Canada, the US, and select international markets. In addition to its partnership with Zogo and MoneyPrep, BMO offers tools and resources for financial education and wellness, including BMO SmartProgress, an online financial education platform; BMO My Financial Progress, a digital goal-planning platform; BMO Insights, a spend-monitoring solution; and BMO Credit Coach, a credit-health management platform.
Zogo won Best of Show in its Finovate debut at FinovateFall 2019 and returned to the Finovate stage two years later for FinovateFall 2021. Founded in 2018 and headquartered in Austin, Texas, Zogo also introduced its Zogo Shorts financial video series earlier this month, designed to make learning about finance fit into users’ everyday routines. The company also announced an integration with Alkami that brings its financial education resources directly into Alkami’s digital banking experience.
nCino launched its Loan Officer Productivity Suite, a set of AI-powered and automated tools designed to streamline mortgage origination workflows and improve loan officer productivity.
The suite includes six capabilities spanning borrower eligibility checks, underwriting summaries, pre-approvals, disclosures, and connectivity with external AI agents through MCP.
The launch focuses on workflow execution, potentially helping mortgage lenders increase loan volume without adding staff.
Agentic AI banking platform nCinounveiled its Loan Officer Productivity Suite today. With the new set of tools, the North Carolina-based company aims to help increase the productivity of mortgage originators by adding automated actions.
Launched inside the nCino Mortgage Solution, the new suite uses each lender’s own data, product guidelines, and workflow rules to give originators answers specific to their institution and let them take action. Among the clients already using the Loan Officer Productivity Suite is Educated Mortgage, which uses it for daily origination workflows; and Security National Financial Corporation, which uses the tool to prepare its loan officers by giving them relevant borrower information.
“We’re excited to equip our loan officers with nCino’s intelligent features so they’ll have more confidence knowing exactly what each file needs to keep moving and can trust that routine tasks and borrower questions are being handled along the way,” said Security National Financial Corporation Vice President and CIO Thayne Atkinson.
The Loan Officer Productivity Suite is launching with six major elements:
Mortgage Advisor for Loan Officers: Allows originators to ask questions naturally and receive plain-language answers about their pipeline, individual loan files, and GSE guidelines.
Loan PreCheck: Evaluates borrower eligibility against multiple guidelines and recommends the best-fit loan program before the underwriting process takes place.
Mortgage MCP for Loan Officers: Allows loan officers to connect their preferred AI agents directly to the nCino Mortgage Suite using an MCP connection.
AUS Smart Tasks: Turns underwriting findings into a plain-language summary and surfaces suggested tasks.
Automated Pre-approval: Unifies credit authorization, verification services, fee calculations, and dual AUS integrations into a single process.
Automated Disclosures: Automates Initial Disclosures and Redisclosures for standard loan templates.
“Loan officers are being asked to handle more work without sacrificing responsiveness to borrowers,” said nCino General Manager of Global Mortgage Casey Williams. “The Loan Officer Productivity Suite helps create that capacity by taking routine work off originators’ plates and putting answers and next steps at their fingertips, so they can stay responsive and competitive without adding more hours to the day.”
Since it was founded in 2012, nCino has shifted from a cloud banking tool provider to providing more agentic-focused tools that help clients execute workflows. Because mortgage originators spend a significant amount of time navigating disconnected systems, reviewing borrower information, and completing administrative tasks, shifting to more automated execution could help increase loan volume without adding staff. Additionally, nCino’s support for MCP opens the door for lenders to use external AI agents to interact with their mortgage technology, which could change how loan officers work with their existing systems.
Agentic shopping is taking over the headlines, but are consumers really ready to hand over their credit cards to a bot? Visa recently sponsored a report that measures consumers’ attitudes toward agentic commerce.
The research was conducted by The Harris Poll in May of 2026 and surveyed 2,065 US adults to provide insight into how consumers are navigating the next evolution of AI shopping and payments. The report found that 72% of respondents have used an AI assistant, 23% trust generative AI to handle payments on their behalf, and 61% would trust Visa to handle agentic transactions.
The findings from The Harris Poll’s research reveal four key takeaways for the future of agentic commerce:
Payment providers could retain influence even if AI owns the customer interface
Visa’s research suggests that consumers distinguish between the technology that helps them shop and the payment providers they trust to facilitate transactions. So while they may use an AI agent to recommend a new pair of shoes, compare prices, and select a retailer, when it comes time to pay, many still prefer the protections and peace of mind offered when using a familiar, established payment provider.
The implication: Banks and payment networks may not need to own the entire AI shopping experience to remain relevant. Their competitive advantage could depend on providing trusted payment infrastructure that sits behind the shopping experience.
Trust could become a competitive advantage for incumbent banks
As it is still a new concept, much of the conversation around agentic commerce has focused on the enabling technology, such as APIs, tokenization, agent authentication, and payment execution. And for good reason: figuring out the logistics of the payment that leverages a constantly evolving field of technology with multiple players is complicated.
However, Visa’s research suggests that consumer confidence could be just as important as technical capability. This element of consumer trust and confidence creates a lot of opportunity for established financial institutions that may feel locked out of participating in agentic commerce.
The implication: Fortunately for banks and payment providers, they already have relationships with consumers, established fraud protections, and experience in handling disputes. Each of these elements is a differentiator as AI agents begin initiating transactions.
Agentic commerce could reinforce existing payment infrastructure
Stablecoins have been taking over discussions in banking and fintech, as their low-cost, speedy rails have the potential to improve the overall customer experience while driving down costs. Additionally, their programmable, blockchain-based infrastructure could make stablecoins an attractive payment option for certain agentic commerce use cases. However, as Visa’s study implies, if consumers prioritize familiar, trusted payment brands, card networks may have an advantage in the early stages of adoption.
The implication: This prioritization shows that lower transaction costs and technical efficiency may not be big enough reasons for consumers to adopt unfamiliar payment experiences. For fintechs building alternative payment solutions, trust and consumer protections may be just as important as price and convenience.
The opportunity in autonomous transactions is in making transactions feel safe
Agentic commerce is still in its early stages, and we still have a lot to learn when it comes to best practices. However, the findings in Visa’s study imply that successful agentic payments will require clear permissions, spending limits, authentication, and dispute resolution.
The implication: If shoppers do not feel safe in allowing agentic AI to make payments on their behalf, they will continue to shop via traditional ecommerce methods. However, Visa is already developing infrastructure through its Visa Intelligent Commerce initiative that will offer authentication, transaction security, and consumer controls. Consumers may be more willing to embrace agentic commerce when trusted financial services providers establish the necessary safeguards, rather than leaving the experience to a fragmented group of unfamiliar players.
It’s a dual holiday today in the US, with Americans celebrating both Columbus Day and Indigenous Peoples’ Day to start the week. There’s no break in the fintech news flow, though, and Finovate’s Fintech Rundown has you covered. Be sure to check back all week long for the latest updates.
Fraud prevention
Document intelligence specialist Veryfiintroduces its Fraud Detection and Prevention Suite.
Identity document verification and bank card scanning solutions provider OCR Studio and payment infrastructure company FinOnteam up to enhance security across onboarding and online payments.
On-Demand Pay specialist DailyPayannounces $200 million asset-backed securitization of its On-Demand Pay receivables.
Backbase launched Conversational Banking, an agentic AI solution that allows banks to move beyond answering customer questions to executing banking tasks within predefined permissions and controls.
More than 10 banks are already using the solution, with one major South African bank increasing self-service containment from 20% to 70% across 22 million customer interactions.
The launch highlights a broader shift toward AI-powered execution in banking, raising questions about whether banks will prioritize cost savings or leverage AI to deliver more personalized customer experiences.
Engagement banking solutions provider Backbase is launchingConversational Banking this week to bring agentic AI into the customer and employee experiences.
The launch comes 18 months after Backbase unveiled its new AI-powered banking platform that sought to improve customer engagement with AI-powered self-service and real-time support. Conversational Banking, which runs on Backbase’s AI-native Banking OS, takes that a step further by allowing the AI agent to actually execute appropriate banking actions on the behalf of consumers and employees, given that they fall within pre-defined permissions, policies, and approvals as set by the bank.
The Conversational Banking tool works alongside existing digital banking stacks and allows customers to use natural language prompts to have their lost payment card blocked and replaced, check a payment, or progress a service request. By leveraging customer context, permissions, and connected banking systems, AI agents can carry out specific, permitted tasks on customers’ behalf. For requests that require further investigation or human judgment, employees can pick up where the agent left off by examining an overview of the work the agent has already completed.
“Digital banking put the bank in the customer’s pocket. The next step is to let customers say what they need done and have the bank’s agents act on it intelligently,” said Backbase Founder and CEO Jouk Pleiter. “That future has now arrived early: one where agents do the work, and banks stay in control. It completely changes both the customer experience and the economics of serving them.”
Backbase anticipates that by allowing AI agents to carry out tasks on behalf of consumers and employees, banks can scale and increase their service capacity. In fact, according to a report by McKinsey & Company, agentic AI could cut banks’ operating costs by 15% to 20%, as the automation frees up employee time for advice, exceptions, and complex needs.
Currently, 10+ banks have already started using Backbase’s new Conversational Banking and have reported positive feedback. One of the four largest South African banks has so far supported 22 million customer interactions, while improving self-service containment from 20% to 70%.
Backbase’s launch shows that banks are beginning to shift from AI-powered tools to AI-powered execution. Chatbots have historically been limited to providing information and directing customers to the appropriate resources. By handing tasks over to agentic AI, banks can automate the steps required to resolve customer requests. This transforms AI from a customer service tool into a functional layer of the banking experience. With its background in compliance, Backbase is in a great position to add reliable governance and permissions into the agentic process, addressing one of the key hurdles preventing banks from putting agentic AI into production.
The bigger question, however, is whether banks will use these agentic capabilities primarily to reduce operating costs or to meaningfully improve the customer experience. Automating routine service requests can certainly improve efficiency, but the longer-term opportunity may lie in using AI to deliver more proactive, personalized banking services.
This week’s edition of Finovate Global showcases recent fintech news from South Korea.
Gwangju Bank and Toss announce stablecoin QR payment PoC
Korea’s Gwangju Bank announced that it had successfully completed proof of concept (PoC) for stablecoin-based QR code payments in partnership with Seoul-based superapp Toss. The PoC linked the Gwangju Bank mobile app, the Toss app, and Toss Place payment terminals. Selecting stablecoin payment in the bank app opens the QR scanner in the Toss app, where the user can scan the QR code displayed on the merchant’s payment terminal to verify the payment amount and complete the transaction.
The demonstrated flow was designed to transfer stablecoins from the customer’s wallet to the merchant’s wallet. The payment result could then be verified in the Gwangju Bank app, completing the app-to-app payment process. The PoC used a virtual merchant, and no actual customer data or assets were involved.
The two entities added that they plan to streamline the process by reducing the number of steps customers must take. The bank and fintech are also discussing a second phase of testing involving actual merchants in the Jeonnam and Gwangju regions.
“The PoC conducted with Toss is significant in that it established a technological foundation to proactively respond to the digital asset payment environment and verified the user experience from a customer perspective,” Gwangju Bank Vice President Byun Mi-Kyung said.
Gwangju Bank is a regional South Korean financial institution and a subsidiary of JB Financial Group. Founded in 1968, the bank reported total assets of approximately KRW 34.4 trillion ($54 billion) at year-end 2025. It operates branches in Gwangju, Jeonnam, Seoul, Incheon, and Seongnam.
Founded in 2015 as a money transfer service, Toss has grown into one of Korea’s leading superapps with 30 million users. Toss offers an ecosystem of more than 100 financial management and e-commerce services, along with more than 10,000 mini apps through its Apps in Toss platform, which runs within the Toss app.
Canton Foundation forges strategic partnership with LG CNS
In a bid to expand institutional adoption of the Canton Network in Korea, the Canton Foundation has announced a strategic partnership with Seoul-based IT services provider and systems integrator LG CNS. Together, the Canton Foundation and LG CNS will develop technical capabilities to support Canton implementation as help build a broader technical partner ecosystem.
“Korea is a critical market for institutional adoption of Canton in Asia,” Canton Foundation Head of APAC Thomas Chou said. “This partnership is about building the market together, combining Canton’s growing institutional ecosystem with LG CNS’s deep technology capabilities and relationships across the Korean financial sector. Together, we aim to help institutions move from identifying opportunities to implementation, while building the broader technical ecosystem needed to support adoption at scale.”
The Canton Network is a public, permissionless blockchain designed specifically for institutional finance, while individual applications can define their own permission requirements. Announced in 2023, the network’s mainnet went live in July 2024. It was designed to balance blockchain transparency with the confidentiality required by regulated financial institutions and markets. Canton operates as a modular blockchain ecosystem in which participating institutions maintain their own ledgers while connecting with others via a shared synchronization layer. Canton’s “network of network” architecture enables real-time secure synchronization and settlement, atomic transactions that ensure that complex exchanges involving multiple parties are completed in full or not at all, and privacy for sensitive financial information.
The partnership between the Canton Foundation and LG CNS will focus on three areas: institutional market development, technical enablement and implementation, and technical partner ecosystem growth. LG CNS has been a major player in Korea’s blockchain-based financial industry since 2015. Beginning with the issuance of blockchain-based electronic securities, the company has built the infrastructure for the issuance, distribution, settlement, and trading of digital assets such as CBDCs, tokenized deposits, security tokens, and stablecoins, as well as digital wallets and KYC systems for financial institutions. LG CNS has also built and operated core systems for major commercial banks, insurers, credit card companies, and securities firms for more than 30 years.
“Financial institutions are increasingly moving from exploring blockchain technology toward practical implementation,” said LG CNS EVP and Head of Digital Business Division Hongkeun Kim. “Through our partnership with Canton Foundation, we look forward to combining LG CNS’s technology and implementation capabilities with the Canton ecosystem to develop meaningful opportunities with institutions in Korea. We also look forward to contributing our experience to the development of a broader technical partner ecosystem that can support institutional adoption over the long term.”
The Canton Foundation is the advocacy and expansion arm of the Canton Network. The organization is dedicated to expanding the network’s reach and promoting broader institutional adoption.
Korea Fintech Industry Association announces new anti-hacking strategy
In response to a series of suspected, AI-assisted cyberattacks and data leaks that struck at least seven major South Korea financial institutions in recent weeks, the Korea Fintech Industry Association brought fintech firms and electronic payment providers together this week to discuss the importance of coordinated data-sharing and early risk checks to enhance their defense against cyberattacks.
Kim Jong-hyun, chairman of the association, said recent cyber incidents should not be viewed as problems affecting individual companies alone, but as threats to public confidence in financial services as a whole. His remarks underscored the need for coordinated information-sharing and greater cooperation with regulators to strengthen security. The chairman also emphasized the importance of building systems that will enable teams to identify risks early and respond proactively.
The discussion also covered the Financial Supervisory Service’s (FSS) IT security self-inspection checklist, which the country’s Financial Services Commission has asked firms to use. The 12-point checklist addresses threat intelligence and blocklists, system abnormality detection, access controls and vulnerabilities, system hardening, and incident investigation.
Here is our look at fintech innovation around the world.
Central and Eastern Europe
Czech fintech Dateio secured its biggest contract to date thanks to a partnership with ING.
Bulgaria’s Fibank partnered with Bitpanda Enterprise to integrate crypto investing into its My Fibank app.
Poland’s mBank introduced BLIK Recurring Payments, the ninth bank in the country to offer the service.
Middle East and Northern Africa
Valley National Bank acquired Israeli fintech Bluevine for $340 million.
Diebold Nixdorfannounced that it will deploy cash recyclers for digital wallet and mobile payments company stc pay Bahrain.
US-based money transmitter Viamaericas has added Ethiopia and Morocco to its remittance network.
Central and Southern Asia
TBC Uzbekistan launched its first secured lending product for SMEs.
India’s Pine Labs introduced a unified payments platform for merchants in Singapore.
DK Bank to establish a subsidiary in the UAE, becoming the first Bhutanese bank to expand its financial services offering internationally.
Latin America and the Caribbean
Brazilian fintech Asaas raised $55.6 million in new funding to supports its payment, financial management, and credit tools for small businesses.
SoFi Tech Solutions (formerly Galileo) teamed up with Orbi and Mastercard to launch a crypto-linked card in Mexico.
Latvia’s Regula and Chile’s Bernini.ai announced a partnership to provide ID verification for AI agents.
Asia-Pacific
South Korea’s Gwangju Bank and fintech Toss successfully completed a proof of concept involving stablecoin payments using QR codes.
Vietnam’s MB Bank partnered with OceanBase to modernize its database infrastructure.
The Korea Fintech Industry Association announced new anti-hacking measures in the wake of series of recent cybersecurity incidents involving financial services companies.
Sub-Saharan Africa
Pan-African payments aggregator PawaPay secured a Payment Service Provider (PSP) license from the Bank of Mozambique.
South Africa’s WalletDoc launchedVisa Payment Passkeys for merchants in the country.
Pan-African neobank Mukuru introduced its new account and card in South Africa, in partnership with Bank Zero and Mastercard.
Know Your Business (KYB) platform Intrepid Fox has teamed up with KYB data and public register provider Topograph.
The partnership will combine Intrepid Fox’s KYB workflows with live company records from official registers for onboarding and ongoing reviews.
Intrepid Fox most recently demoed its technology at FinovateEurope 2025 in London.
UK-based Know Your Business (KYB) platform Intrepid Foxannounced a partnership with Topograph, a company that provides the data layer for B2B onboarding. The partnership is designed to close the information gaps that can develop after business customers are initially onboarded and keep databases up to date with information on a company’s status, ownership, address, and more. Intrepid Fox’s AI agents provide updated company information that can be compared with data that is already on file. The agents can determine whether follow-up is required and can create context to support human agents in their investigations.
The goal is to combine detection with action through a structured review that records the evidence, follow-up, and human decision-making. This enables compliance teams to focus on those changes that are most critical instead of having to manually review and refresh every company file.
“Monitoring tells you that something changed. A compliance team still needs to understand what changed, whether it matters to the relationship, and what evidence supports the next step,” Intrepid Fox CEO and Co-founder Roman Zilber said. “Working with Topograph helps us connect that signal to a review where context and human judgement remain visible.”
As vital as KYB processes are, they are only as reliable as the records they start with. By monitoring company records directly from their official registers, Topograph provides updated information that is live and traceable to its source. This approach avoids the problems of stale databases, manual searches, and compliance gaps. The company offers a single API that enables teams building onboarding and KYB flows to get live company data, beneficial ownership information, and official documents, while monitoring their systems for changes—all of which is normalized across markets and traceable back to the source. Headquartered in Paris, Topograph was founded in 2024.
“Compliance decisions are only as good as the data behind them,” Topograph CEO and Co-founder Pierre-Henri Janssens said. “That’s what guides our work at Topograph: we connect to more than 100 official registers ourselves, which lets us monitor company records in real time and trace each data point back to its source. Intrepid Fox builds on that foundation, so compliance teams can work through each change with the full context in front of them.”
Founded in 2024 and headquartered in London, Intrepid Fox made its Finovate debut at FinovateEurope 2024 and returned the following year for FinovateEurope 2025. The company leverages GenAI to power document collection and accelerate business customer onboarding for banks and fintechs. Intrepid Fox’s technology helps reduce follow-ups and the operational burden of KYC, while enriching collected data from online and open sources.
Intrepid Fox’s partnership news comes just a few weeks after the company announced an integration with real-time company data provider Kausate. Like Topograph, Kausate connects platforms directly to official registers to provide real-time access across European jurisdictions.
For much of the financial services industry, the conversation around AI has focused on creating efficiencies by automating processes, reducing costs, and replacing manual work. But banks may be overlooking AI’s biggest opportunity. Rather than focusing on what AI can eliminate, financial institutions may find greater value in using the technology to better understand their customers, anticipate their financial needs, and deliver personalized experiences that drive revenue.
In this conversation from FinovateFall 2026 in New York, we speak with Oban MacTavish, Co-Founder and CEO of Spade, about why the industry’s enthusiasm for AI agents may be misplaced and how better transaction data can help banks unlock AI’s potential. MacTavish explains why traditional payment data isn’t built for modern intelligence tools and how financial institutions can use AI to recreate the personalized relationships customers once had with their local bankers, but at scale.
“I think most of their customers are looking for a better experience, and it’s one of the ways that we actually see the biggest opportunity for AI in financial services is helping them turn their data into revenue,” said MacTavish.
MacTavish is Co-Founder and CEO of Spade, a New York-based financial data and AI company he co-founded in 2021. Under his leadership, Spade has expanded its platform to help financial institutions make better use of payments data for fraud prevention, customer engagement, analytics, and AI-powered applications. MacTavish also participated in a fireside chat at FinovateFall 2026 on how AI is changing offers, cross-sell, and personalization.
Founded in 2021, Spade transforms raw transaction data into structured, actionable merchant intelligence. Its platform helps banks, fintechs, and other financial services companies identify merchants, enrich transaction records, and build more personalized financial products and experiences. Spade raised $40 million in Series B funding in March 2026, led by Oak HC/FT, to expand its data and AI capabilities.
UK-based open banking platform TrueLayer raised $27 million in a funding round led by CDP Venture Capital, bringing its total funding to $348.8 million.
TrueLayer is expanding beyond one-time pay-by-bank payments with recurring payment capabilities and its acquisition of BNPL provider in3, positioning itself to compete more directly with traditional card networks.
The investment reflects Europe’s push for greater financial sovereignty, supporting the development of European-owned payment infrastructure as pay-by-bank adoption grows across the region.
UK open banking platform TrueLayer has brought in $27 million in a funding round this week led by Italy-based CDP Venture Capital with additional contributions from existing and new investors. The investment adds to the $321.8 million already raised and brings TrueLayer’s total raised to $348.8 million.
“We started TrueLayer with a simple belief: Europe deserves payment infrastructure built in Europe. Having Italy back that belief means a great deal to us personally, especially to our talented team in Milan, who work hard every day to build the future of European payments,” said TrueLayer Co-Founder and CEO Francesco Simoneschi.
Founded in 2016, TrueLayer powers $150 billion each year in online pay-by-bank payments for more than 30 million consumers in 22 countries. The company provides the connectivity and commercial payment experience that make payment rails accessible to businesses. By cutting out the middlemen involved in the payments stack, TrueLayer’s pay-by-bank tools help merchants lower payment costs by up to 40%, increase average order value by 20%, and reduce fraud by eliminating the need for payment cards. Among TrueLayer’s competitors are Trustly, Visa-owned Tink, and Volt.
Earlier this year, TrueLayer announced support for recurring payments and acquired Dutch buy now, pay later (BNPL) provider in3. The move adds a financing component to an offering historically focused on immediate bank payments. These two developments show that TrueLayer is seeking to compete beyond the pay-by-bank space. The company is slowly shifting its focus to compete with card payments at ecommerce checkout, replace card-on-file for subscriptions and repeat purchases, support merchant refunds and instant disbursements, and offer purchase financing without depending on traditional card rails.
While pay-by-bank has seen limited growth in the US, its usage is growing in Europe. In July of this year, the UK’s open banking ecosystem reached two major milestones, reaching more than one billion open banking payments and 100 billion API calls recorded across the CMA9 banks since the launch of open banking started more than eight years ago.
As European policymakers and investors increasingly emphasize financial sovereignty, TrueLayer offers an opportunity to build an alternative to payment infrastructure dominated by US-based companies such as Visa and Mastercard. CDP Venture Capital’s investment underscores that ambition, positioning pay-by-bank as both a lower-cost payment option and a strategic component of Europe’s financial infrastructure.
“Europe needs payment infrastructure it owns and controls, and we are investing across the continent to help build it,” said Mario Branciforti of CDP Venture Capital. “TrueLayer is a clear example of what that looks like in practice, with a network already operating at scale in 22 countries.
All 72 demo videos from FinovateFall 2026 are now available for viewing—100% free. Whether you are looking to catch up on demos that you missed at the conference last month or just want to get another gander at a few of your favorite presentations, the demo videos for FinovateFall 2026 can now be viewed either at our Finovate blog video archive or at our FinovateTV channel on YouTube.
To whet your viewing appetite, consider starting your FinovateFall 2026 demo video watch-a-thon with these eight videos from the companies that took home Best of Show awards from the event.
Gusto unveiled three updates for its 23,000+ accounting firm customers: a rebuilt Gusto Pro, a multi-client Model Context Protocol (MCP), and an expanded Gusto Partner Program.
The new tools use AI to help accountants scale their practices, automating payroll preparation and reporting while allowing accountants to retain control over approvals and focus on higher-value advisory work.
The company’s multi-client MCP brings its payroll data into accountants’ preferred LLMs, signaling a shift in which financial software can remain the underlying system of record even when an AI assistant becomes the primary interface.
Payroll, benefits, and HR management solutions company Gusto is shipping three new updates to help its more than 23,000 accounting firm customers serve their small business clients. The California-based company is adding a rebuilt Gusto Pro, a new multi-client Model Context Protocol (MCP), and an expanded Partner Program.
The new capabilities let firms put AI agents to work on payroll prep while staying in control of approvals. Gusto aims to empower its accountant clients to better serve their own customers while scaling their practices.
Gusto Pro, the company’s accountant payroll software, has been updated to include new AI-assisted workflows, an AI assistant with visibility into multiple clients, automated reporting, and a simplified dashboard built to free up accountants from manual tasks. While the updated platform is now available to eligible clients, the company is planning to make the updates generally available later this year.
“Gusto Pro provides advisory forward-thinking insights and tools,” said Wyatt Kneaper, founder and CEO of The Lighthouse Group, an accounting firm based in Eureka, California. “When a client is engaged, we can surface insights based on Gusto Pro to say, hey, let’s have a conversation. What are your goals? What direction do you want to head in the next two to five years? There’s a huge door that potentially opens.”
Additionally, the company now offers accountants a multi-client MCP that brings Gusto’s business context directly into the accountant’s preferred LLM. Because the MCP is multi-client, accountants can use their LLM to ask questions across their book of business without having to log in multiple times or set up multiple different windows for conversations.
Finally, Gusto has upgraded its Partner Program to help accountants grow their firms and receive more revenue share when they serve more clients on Gusto.
The Gusto Partner Program incentivizes firms to grow their practices by offering rewards. When accountants serve more clients on Gusto, they receive more revenue share as well as increased strategic support to invest back into their firms. Gusto offers marketing support, development funds, access to a consultant network, and the use of AI agents to help firms win new clients and deepen advisory revenue.
These updates show that fintechs are responding to their clients’ interests in leveraging AI to better serve their end customers. In Gusto’s case, the fintech is using AI agents to take over more of the preparation itself, leaving accountants to review and approve the work and spend more time on higher-value advisory services. Additionally, the multi-client MCP allows accountants to access Gusto data and prepare payroll from the LLMs where they already work.
In the broader fintech context, the MCP connection may be the most interesting piece of today’s announcement, as it shows that Gusto is acknowledging that the primary interface for financial software isn’t necessarily its own platform but rather the customer’s LLM. Gusto will remain the system where payroll data lives and transactions ultimately take place, while accountants choose to interact with that data through their AI assistant.