This site is operated by a business or businesses owned by Informa PLC and all copyright resides with them. Informa PLC's registered office is 5 Howick Place, London SW1P 1WG. Registered in England and Wales. Number 8860726.
Finovate Blog
Tracking fintech, banking & financial services innovations since 1994
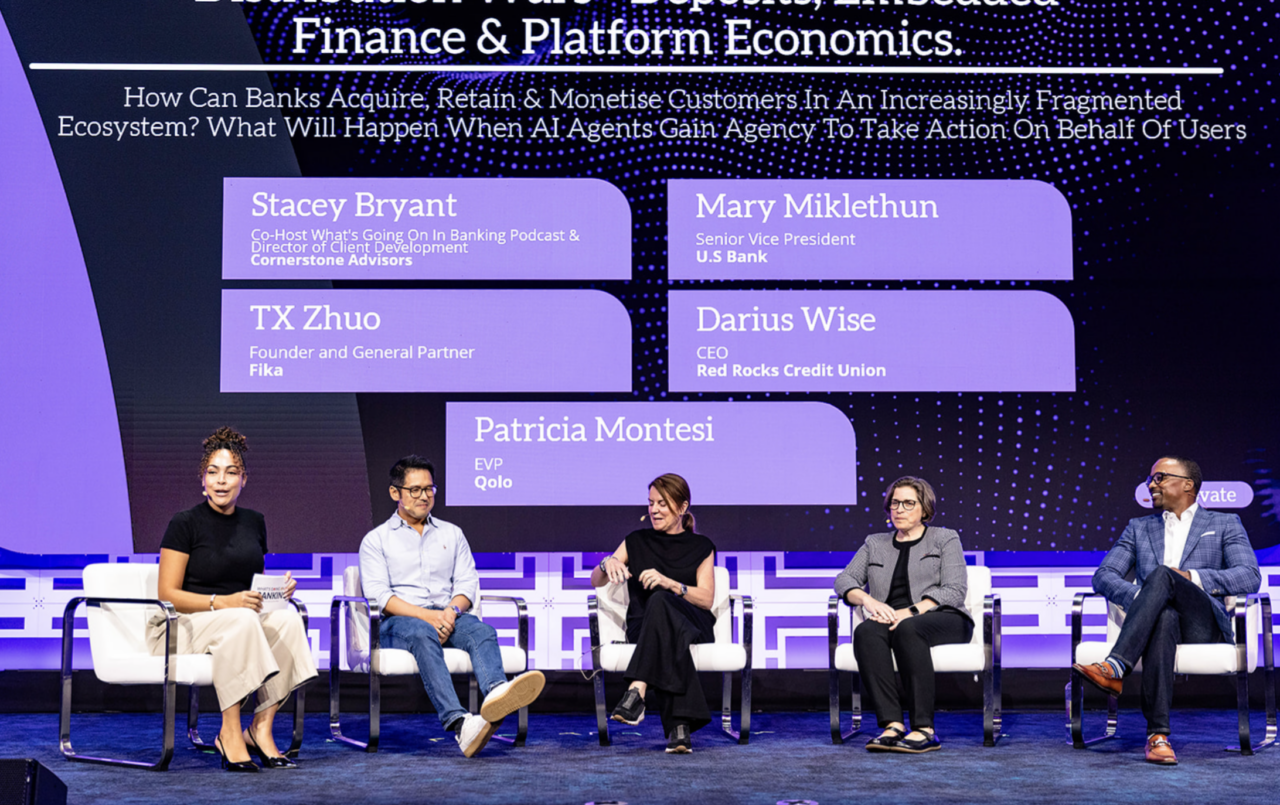
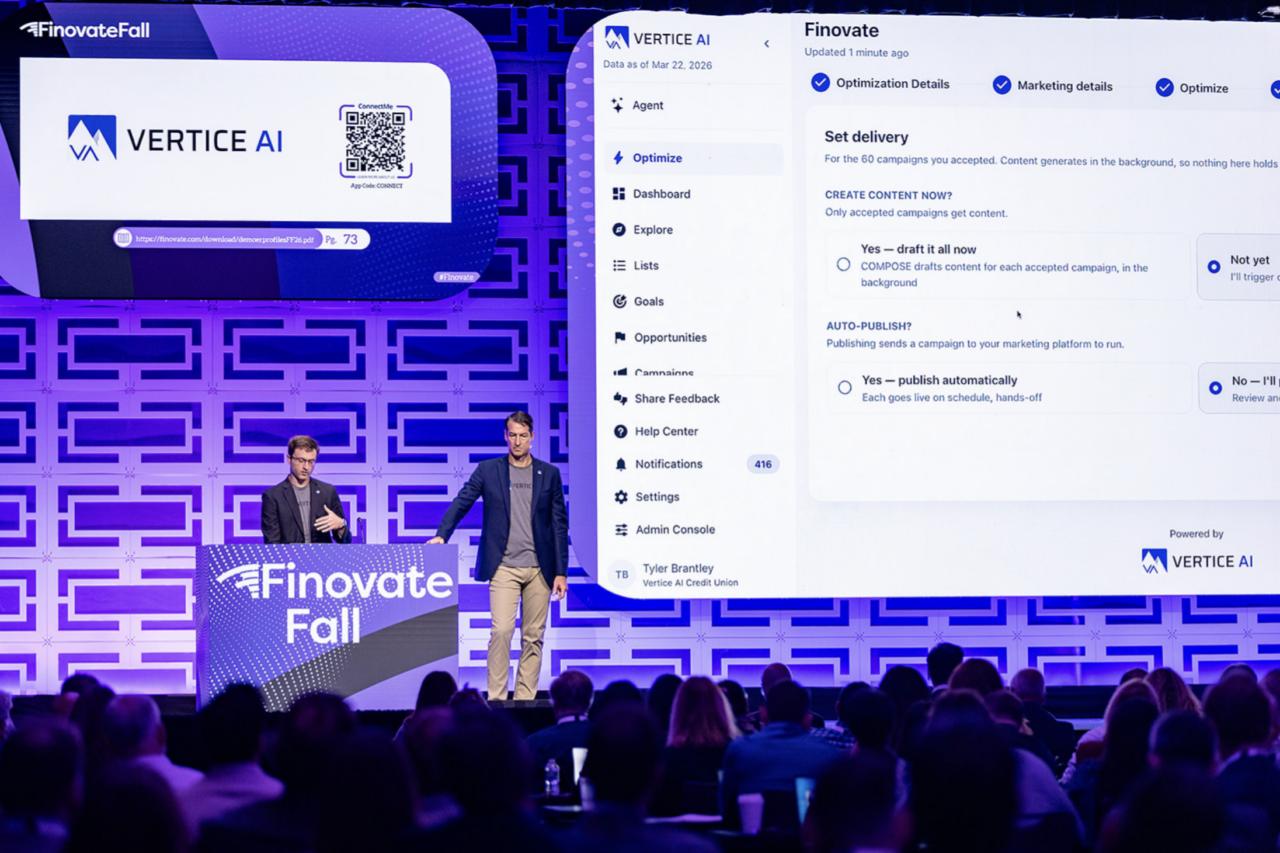
Whether you missed out on FinovateFall in New York earlier this month or you were there in person, it’s worth checking out the massive number of photos that came out of the three-plus day event.
The event was full of meaningful conversations, fast-paced demos, a reunion of familiar faces, and new connections. And while speakers and attendees were busy talking and learning about all things fintech and banking, Finovate’s photographer was capturing the event in more than 1,000 photos.
The photos are broken down into 31 categories, including demos, industry stage sessions, and networking drinks. New this year, you can search for photos that you appear in by uploading a selfie. Here is a sampling of a few photos to help summarize FinovateFall 2026.
With the midterm elections only six-odd weeks away, control of the US House is one of the questions that will shape the next Congress. I wanted to think a little about what a future Democratic House might mean in terms of policymaking for banking, fintech, and financial services.
New Sheriffs with Old Badges
The biggest difference could be in the leadership of various House committees. For example, the House Financial Services Committee is currently chaired by French Hill, a Republican from Arkansas. Maxine Waters, a Democrat from California and the committee’s current ranking member, previously chaired the committee. If the Democrats control the House, Waters could again become chair.
As chair, Waters previously emphasized consumer protection, affordability, diversity/inclusion, and congressional oversight. More recently, she has raised concerns about bank safety and soundness, cybersecurity and the financial risks associated with AI, as well as cryptocurrencies and digital assets.
What could the committee accomplish? Oversight would be one of the committee’s most significant tools, along with the ability to issue subpoenas and compel testimony from banks, other financial institutions, and regulators. Hearings, investigations, and committee reports could provide additional opportunities to examine financial policy and bring those issues before the public and the press.
Community Banks and Regulatory Clarity as Common Ground
Given the acrimony between the parties, are there any opportunities for a Democratic House and the Trump administration to work together on banking policy?
While Democrats and Republicans have very different priorities when it comes to banking and finance, there are some areas of potential compatibility. Both Democrats and Republicans have said that they support efforts to help reduce regulatory burdens on smaller financial institutions. The devil is in the details, but it is not impossible to imagine a compromise in which reduced regulatory burden on community banks and credit unions was paired with a commitment to continued, if not intensified, oversight when it comes to the big banks and larger financial institutions. In fact, Hill and Waters actually worked together on the bipartisan 21st Century ROAD to Housing Act, which included provisions benefiting community banks.
Providing fintechs with greater regulatory clarity over issues like bank-fintech partnerships, for example, is another area where a Democratic House and the Trump administration may be able to find commonality. But one major sticking point might be crypto, where there is a great deal of suspicion about the role of digital assets—including meme coins—among many Democrats, as well as concerns and questions over President Trump and his family’s own involvement in the cryptocurrency industry. As such, policies focused more on stablecoins, which occupy a more specific policy and payments question compared to digital assets as a whole, represent a more fertile ground for bipartisan discussion.
Policy Debates and Paradigm Shifts
Most importantly, Democratic control of the House of Representatives next year would set the stage for a broader debate on the country’s financial priorities. Under the Trump administration, deregulation and lowering compliance costs have been central, along with limiting the authority of regulatory agencies such as the Consumer Financial Protection Bureau (CFPB). For Democrats, fortifying these agencies is a major goal, as is restoring an emphasis on consumer protection, financial stability, and regulatory independence.
What is interesting to me is how current concerns and controversies—the pace of AI development, the proliferation of prediction-market and gambling activity, concerns over government ethics and conflicts of interest, and the broader affordability debate—could interact with the traditional stances politicians on both sides of the aisle have championed and defended. How much will concerns about the longer-term risks of AI change the debate over regulation in financial services and other sectors? And, in a divided-government scenario, where will there be enough common ground for Congress and the administration to address specific problems facing banks, fintechs, and their customers?
Numeral raised $100 million in Series C funding, bringing the tax compliance platform’s total funding to $157.5 million since its 2023 founding.
The company will use the capital to accelerate product development, expand into additional industries, and grow its team, while launching a new accounting partner program.
Numeral is using agentic AI to automate more of the tax compliance workload while keeping humans in the loop, as businesses face growing complexity across markets and jurisdictions.
Sales tax compliance platform Numeral has raised $100 million in Series C funding, boosting its total raised to $157.5 million since it was founded in 2023.
Insight Partners led the round, which saw participation from Salesforce Ventures, Geodesic, Benchmark, Mayfield, FCVC, Y Combinator, and Uncork.
San Francisco-based Numeral aims to simplify sales tax compliance details such as nexus tracking, registrations, filing, rate calculation, remittance, exemption certificate management, and virtual mailbox services. In addition to sales tax, the company works with VAT and GST compliance in more than 90 countries. Numeral has recently recorded a 327% year-over-year increase in total transaction volume and expects to process more than 80 million transactions via its tax engine.
“Sales tax has become a much bigger operational challenge as companies grow across markets, systems and business models,” said Numeral Co-Founder and CEO, Sam Ross. “Businesses need infrastructure that can keep pace as rules and requirements change across jurisdictions, without adding more manual work for their teams. We’re building Numeral to provide that foundation, backed by tax expertise and service that customers can rely on.”
Numeral will use today’s funding to accelerate product development, expand its offering for industries, and grow its team. The company is also launching its accounting partner program that will allow partnering firms to refer clients, resell the platform, use it to deliver their own services, or advise clients through implementation to stay closely involved in their clients’ tax decisions. Overall, Numeral’s technology leverages agentic AI while keeping humans in the loop.
“Our customers want to know that their tax obligations are being handled accurately while still having access to a person when a complex issue comes up,” said Ross. “That expectation shapes how we build the platform and how we support each customer. As Numeral moves into additional industries and serves larger businesses, we’ll continue investing in both the technology and the tax expertise behind it.”
As tax compliance is becoming more complex for businesses operating across multiple markets, Numeral is using AI to automate more of the work traditionally handled by internal tax teams and accounting firms. Rather than simply using AI to help employees complete compliance tasks, Numeral’s technology aims to take on more of the operational burden itself, while keeping tax professionals available for complex cases.
Identity network and fraud intelligence platform Baselayer has secured $35 million in new funding. The Series A round was led by M13, and featured participation from Torch Capital, Picus Ventures, Afore Capital, and Matt Thompson of fellow Finovate alum Socure.
Along with the investment announcement, Baselayer unveiled its Agentic Identity Suite, an interoperable trust layer that helps institutions verify autonomous AI agents.
New York-based Baselayer made its Finovate debut at FinovateSpring 2026.
Business identity network and fraud intelligence platform Baselayer has raised $35 million in Series A funding. The round was led by M13 with participation from Torch Capital, Picus Ventures, Afore Capital, and Matt Thompson of fellow Finovate alum Socure.
In addition to the investment, Baselayer announced the launch of its Agentic Identity Suite, an interoperable trust layer and agentic fraud consortium for the global agentic economy.
“Every era of commerce has required a new trust layer, but historically that infrastructure gets built only after fraud and abuse make the problem impossible to ignore,” Baselayer Co-Founder and CEO Jonathan Awad said. “Agentic commerce is moving too fast for the industry to repeat that mistake. We already help one in five US financial institutions answer, ‘Can I trust this business?’ Now we’re building the infrastructure they need to answer, ‘Can I trust this agent, who does it represent, and what is it allowed to do?”
Agentic commerce is growing rapidly. According to Stripe, 70% of the commands used to access its data through its API now come from AI agents. Major card networks like Visa, Mastercard, and American Express have launched agent commerce protocols, and Shopify has activated agentic sales channels by default for approximately one million merchants. At the same time, agentic commerce is moving faster than the trust infrastructure necessary to ensure safe and secure transactions. Current financial infrastructure is built to recognize individuals and companies, not autonomous AI agents operating for them. This means that banks, merchants, and platforms need to know who an agent represents, what it is authorized to do, and whether the party the agent is acting on behalf of can be trusted.
Baselayer already answers these questions for businesses, providing identity verification and risk infrastructure to more than 2,300 financial institutions and payments companies. Now, the company is extending that same identity and risk infrastructure to autonomous AI agents.
“Agents don’t carry ID, and the infrastructure built to verify humans and businesses simply doesn’t recognize them,” Baselayer Co-Founder and CTO Timothy Hyde said. “Static fraud controls end up blocking good customers while sophisticated attacks walk through. We built the Agentic Identity Suite so any institution can know, cryptographically, which agent it’s dealing with, who that agent represents, and whether its own agent can safely proceed with any transaction.”
Baselayer was founded in 2023 and is headquartered in New York. In its Finovate debut at FinovateSpring earlier this year, the company demonstrated its Portfolio Monitoring solution that continuously monitors current business customers for material changes. These include Secretary of State status updates, dissolutions, officer changes, new UCC/tax liens, bankruptcy filings, litigation, adverse events, fraud signals, and sanctions list additions. Portfolio Monitoring integrates with the full Baselayer platform and delivers configurable alerting via API or email notification to enable proactive risk management and early warning of customer deterioration without requiring manual periodic reviews.
Baselayer’s funding and product launch announcements follow news that the company has partnered with agentic payments infrastructure company Nevermined. The partnership brings Baselayer’s identity and risk infrastructure into Nevermined’s delegated payment environment, enabling agents to acquire Baselayer API access autonomously while the companies work toward establishing trusted identity for agents and their counterparties.
J.P. Morgan Payments selected Thunes to expand Xpedite Remit, combining its payments infrastructure with Thunes’ Direct Global Network for faster, more transparent cross-border payments.
The partnership gives J.P. Morgan access to 12 billion bank accounts and mobile wallets across 100+ corridors, reducing the need to establish local connectivity market by market.
Chase’s 94 million consumer and small business customers will also benefit, including through faster, real-time inbound payments into the US.
J.P. Morgan Payments has selectedThunes to expand its cross-border capabilities through the bank’s Xpedite Remit solutions suite.
The new suite of tools combines J.P. Morgan Payments’ connectivity with local, real-time payments rails and Thunes’ Direct Global Network to offer a reliable cross-border payments tool. The bank’s Xpedite Remit tool offers protection, end-to-end traceability, and faster payouts, regardless of whether the payment takes place in the same currency or uses a foreign exchange conversion.
The cross-border capabilities offer access to 12 billion local bank accounts and mobile wallets across more than 100 corridors around the clock. Cross-border payments have traditionally required financial institutions to navigate multiple correspondent banking relationships, local payment rails, currencies, and regulatory requirements. Combining J.P. Morgan Payments’ infrastructure with Thunes’ network will enable the bank to extend its reach into local bank accounts and mobile wallets without having to establish that connectivity market-by-market.
“Our clients want simpler, faster ways to move money across borders and to reach people through the payment methods they prefer,” said J.P. Morgan Payments Global Head of High Value Payments & FX, Gayathri Vasudev. “That’s why we are continuing to enhance our cross-border capabilities and further expanding our solution through the collaboration with Thunes. Building on milestones, like our recent progress with Swift’s retail payments scheme, we’re helping clients grow in new markets while delivering the faster, more seamless experiences they have come to expect.”
JPMorgan Chase’s Consumer and Community Bank will also benefit from Xpedite Remit’s expanded cross-border capabilities. The bank’s 94 million consumer and small business customers will receive faster payout experiences with real-time inbound payments into the US.
“As customers increasingly move money across borders as part of their everyday lives, they expect the experience to be fast, intuitive, and reliable,” said Chase Head of Banking Payments, Ashish Ajmera. “These enhancements mark an important step in our efforts to modernize cross-border payments and expand the capabilities available through our broader suite of products and services, helping customers send money internationally with greater speed, transparency and confidence.”
Thunes was founded in 2016 as TransferTo and rebranded to Thunes in 2019. The company offers a cross-border payments and collection network that supports 80 currencies, enables payments to 130 countries, and offers 320+ payment acceptance methods. Unlike traditional cross-border payments providers that often rely on correspondent banking networks, Thunes offers a direct, proprietary global network. This direct network delivers faster, cheaper, and more transparent transactions and allows it to compete against players like Wise and Airwallex.
AI infrastructure provider for regulated industries, Go.AI, has secured $85 million in Series A funding in a round led by Updata Partners. The investment takes the company’s total funding to $90 million.
The capital will enable Go.AI to grow its engineering team, accelerate development of its key solutions, and scale go-to-market efforts beyond regulated industries.
Go.AI made its Finovate debut earlier this year at FinovateSpring 2026 as Go Abacus. The Chicago-based company returned to the Finovate stage for FinovateFall 2026 in September.
Go.AI, an AI infrastructure provider for regulated industries, has raised $85 million in Series A funding. The round was led by Updata Partners with participation from existing investors GFT Ventures and LAUNCH. The investment takes Go.AI’s total funding to $90 million. In a statement, the company said it will use the funding to grow its engineering team and accelerate development of both its operating system, Go.OS, and its hardware line. The company will also scale its go-to-market efforts, expanding beyond regulated industries such as financial services and defense into a broader range of compliance-oriented organizations.
“When Lisa Gillespie and I co-founded the company, we were two people with a big idea,” Moscatelli said. “Today, we have over 50 team members, and the company we’ve built is doing exactly what we said it would do for the institutions that trust us most. This funding lets us keep building at that pace, but the thing I’m most proud of isn’t the growth number, it’s the education. AI doesn’t have to be something people fear or don’t understand. Done right, it works alongside the people who use it. That’s what this round lets us prove, at scale.”
Go.AI offers an on-premises AI appliance that puts enterprise-grade AI inference directly into a bank’s or financial institution’s own environment. Featuring zero cloud dependency and zero data egress, Go.AI’s Go1 is SOC 2 Type II, ISO 27001, and HIPAA compliant, making it purpose-built for regulated industries. This allows institutions to run AI on sensitive data while remaining compliant and auditable. Go1 is paired with Go.AI’s operating system, Go.OS, which automates model management, GPU allocation, and serving without any cloud connection. Go1 provides full model lifecycle governance, including versioning, rollback, and real-time monitoring. Go.AI’s customers are currently running on-premises AI deployments that are processing more than 12.5 million queries a day.
Headquartered in Chicago, Illinois, Go.AI made its Finovate debut at FinovateSpring 2026. The company returned to the Finovate stage earlier this month for FinovateFall. Go.AI’s funding news comes just a few weeks after the company announced its rebrand from Go Abacus to Go.AI. In a statement, Moscatelli said the company’s work in on-prem AI, security, and safety “has matured into a category-defining position” and that the company has succeeded in making “that complexity feel simple, without ever compromising trust or control. Go.AI is the name that finally matches that ambition.”
Payments expert ACI Worldwideannounced it now offers intelligent payments routing for Swift ledger transactions. The capabilities are available using ACI Connetic, the company’s cloud-native payments hub.
Swift’s blockchain-based ledger was announced last year to help banks move tokenized deposits across borders beyond traditional operating hours. While the 17 banks involved stand to benefit from the infrastructure, many have not fit tokenized deposit payments into their day-to-day operations.
Using ACI Connetic, banks will be able to process tokenized deposit payments, as well as traditional payment types, into the same payments environment banks already use to route, monitor, control and reconcile payments at scale. Because banks can use the same operational controls, workflows, and infrastructure for tokenized payments as they do with traditional payments, it eliminates the need for separate digital-asset payment operations.
“Digital assets should extend a bank’s payment capabilities, not force it to build a second payment operation,” said ACI Worldwide SVP, Head of Account-to-Account Payments, Craig Ramsey. “Banks need a practical way to operationalize tokenized deposits at scale using the people, controls and processes they already trust. With ACI Connetic, payments orchestrated through Swift’s ledger can be managed alongside other payment flows within a common operational framework.”
Swift’s ledger may provide the infrastructure to move tokenized value across borders, but banks still need a way to incorporate those transactions into their existing payment operations. By routing Swift ledger transactions alongside traditional payments, ACI Connetic could lower one of the barriers to adoption by allowing banks to experiment with and scale tokenized deposits without building a parallel payments stack. As tokenized deposits move from pilots toward production, that ability to integrate new rails into existing infrastructure will become increasingly important.
ACI Worldwide’s ACI Connetic works by unifying payment types, payment rails, and controls in a single platform that uses bank- and customer-defined rules to automatically select the best clearing and settlement path. This automatic routing gives banks flexibility while maintaining consistent controls and visibility and allowing for scale without relying on a separate operation.
Founded in 1975, ACI Worldwide’s solutions power intelligent payments orchestration in real time to allow banks, billers, and merchants to modernize their payment infrastructure. The company combines a global footprint with local expertise to help its clients manage evolving payment methods and infrastructure. ACI Worldwide, which presented at our developer’s conference at FinDEVr Silicon Valley 2016, is publicly traded on the Nasdaq under the ticker ACIW.
FintechOS raised $28 million in combined debt and equity, bringing its total funding since 2017 to $178.9 million.
The capital will support US expansion, deeper European client relationships, and team growth as the company shifts from efficiency mode back toward faster expansion.
FintechOS enters that growth phase from a stronger financial base, having reached profitability while growing recurring revenue 40%, operational EBITDA more than 102%, and its U.S. business 130% in 2026.
Fintech enablement platform FintechOS has closed $28 million in combined debt and equity. The funding, when added to the company’s previous rounds, boosts FintechOS’s total funding to $178.9 million since it was founded in 2017.
Today’s equity funds come from existing investors Bek Ventures, IFC, Cipio Partners, and Molten Ventures. The debt facility comes from Santander CIB. FintechOS will use the investment to fund its US expansion, deepen its European client relationships, and grow its team.
“Santander CIB’s support, alongside other investors that trust us, is a strong vote of confidence in the path we’re on, and it gives us the capital to go after the extraordinary potential we see ahead, particularly in the US, without compromising the discipline that got us to profitability in the first place,” said FintechOS Founder and CEO Teo Blidarus.
FintechOS aims to help banks launch new technologies by offering them low-code solutions that facilitate fast and inexpensive deployment of new products and services. The company’s Unified Origination tool is an AI-first, cross-product origination solution to help retail and commercial banks accelerate time-to-market. It also offers a composable core product for insurers.
2026 has been a strong year for FintechOS. The company became profitable, boosted its recurring revenue by 40% and grew its operational EBITDA by more than 102% year-over-year, and grew its US business by 130%. Also this year, FintechOS expects to set a new record of client acquisistion, adding more than 20 banks to its client list for FintechOS 8.
“Reaching profitability was not an accident, it was the outcome of a deliberate, multi-year effort to get our cost base, our margins and our delivery practice right before we pushed harder on growth again,” said FintechOS CFO Cyril Desouza. “Now that discipline is paying off twice over: the business has reached profitability, and we’ve already made the shift back into high growth, which is exactly the combination that lets us take on a round like this one.”
The funding comes at an interesting inflection point for FintechOS. After spending the past few years prioritizing efficiency and profitability, the company is now using that stronger financial footing to accelerate growth, particularly in the US.
The mix of debt and equity indicates that instead of relying solely on another dilutive venture round, FintechOS is adding debt capital as it scales, a financing option that is more accessible as it has moved into profitability. For banks, FintechOS’s expansion adds another well-capitalized competitor to the growing field of providers promising to modernize product origination and core infrastructure without requiring them to rip and replace their existing technology stacks.
It’s the last full week of September, which means that the calendar is ready to flip to the final quarter of 2026. Check out what fintechs are up to in this week’s look at the top fintech news. We’ll continue to update this post with news throughout the week.
DeFi
Aracore and Teizato work on institutional stablecoin settlement model between South Korea and Malaysia.
Spriveraises $10 million for mortgage prepayment tool.
Credit and analytics
Nationwide Building Society partners with EquifaxUK to give customers free access to their credit score.
Agentic commerce
GoCardless announces that it has processed the UK’s first agentic account-to-account transaction in the UK.
Wealth management
UK-based, Sharia-compliant, cross-border digital banking platform Nomoteams up with investment service provider AllFunds to establish a fully digital Sharia-compliant investment product.
Lending
Kastlesecures $24 million in Series A funding to support its AI workforce platform for consumer lending.
Plaid and ID.me are teaming up to help US government agencies verify both benefit recipients’ identities and ownership of the financial accounts receiving payments.
The partnership combines identity and account verification into a single flow, helping agencies reduce manual processes, duplicate payments, and the risk of funds being diverted.
Connecting identity with payment destination could help modernize government benefits, enabling legitimate recipients to receive funds faster while strengthening fraud prevention and auditability.
Plaid has selected digital identity network ID.me to enable US government agencies to verify both the person requesting a benefit and the associated financial account receiving it.
Plaid is leveraging ID.me’s digital identity wallet to solve the identity piece and is using its own financial account verification tools to help state and federal agencies verify that the account receiving a benefit payment belongs to the recipient before funds move.
“Identity verification tells an agency who is asking to be paid, but it does not tell them where the money is going,” said ID.me CEO and Founder Blake Hall. “That gap is where benefits go missing, and it’s costing our government and everyday Americans billions of dollars. Through our partnership with Plaid, agencies would be able to confirm the account belongs to the verified person before a dollar moves, and eligible people get paid faster.”
For beneficiaries, the partnership allows users to verify their identity using ID.me and securely link their bank account, eliminating the need to upload bank statements or wait for manual verification. For agencies, account ownership information is sourced directly from the recipient’s financial institution and matched with their verified identity before funds are released. The solution creates a dated record linking the verified recipient with the account that received the payment, while limiting the financial information shared with the government.
The partnership will help agencies consolidate legacy capabilities, reduce the possibility of duplicating payments in error, and make it easier for beneficiaries to receive funds they are entitled to.
“For too long, getting benefits to the people who qualify for them has meant a slow, manual process that fraudsters have learned to exploit. Agencies have gotten very good at confirming who someone is. What’s been missing is the same confidence about where the money actually lands,” said Plaid COO Eric Sager. “By partnering with ID.me, we’re closing that gap so eligible people get paid in minutes, and every dollar reaches the person it was meant for.”
Fraud prevention in government payments has long relied on multiple, often disconnected layers of verification. Identity verification alone is not enough if agencies cannot also verify the destination of the funds. By connecting those two layers, Plaid and ID.me are helping government agencies modernize benefit delivery in a way that could make payments both faster for legitimate recipients and harder to divert fraudulently.
Coinbase and Stablecore are teaming up to help community and regional banks and credit unions offer digital asset services, including trading, custody, and stablecoin payments.
The partnership reflects the broader rebundling of financial services, bringing capabilities that once required separate crypto platforms back inside customers’ existing banking relationships.
Coinbase is positioning itself to benefit either way; it can either own the customer relationship, or it can provide the infrastructure that allows banks to retain it.
Crypto exchange platform Coinbase is teaming up with crypto and DeFi banking infrastructure company Stablecore to help banks and credit unions offer digital asset services through their existing banking platforms.
Under the agreement, Coinbase will tap Stablecore’s expertise to bring digital asset services such as trading, custody, and stablecoin payments to Stablecore’s 3,000+ bank and credit union partners. The goal of the solution is to help traditional financial institutions offer regulated digital asset products without rebuilding their infrastructure. Crucially, the new launch also allows bank customers and credit union members to participate in the decentralized economy without having to leave their existing banking platform.
“Community banks and credit unions shouldn’t have to choose between staying local and staying current,” said Coinbase Head of Infrastructure Business Alec Lovett. “Together with Stablecore we are helping put them on the cutting edge of payments technology—cheaper, faster money movement, and the tools they need to stay strong for the communities they serve.”
Founded in 2025, Stablecore exclusively serves community and regional banks and credit unions. The Texas-based fintech offers white-labeled solutions that integrate into existing banking technology to bring together all of the necessary components so financial institutions can offer tokenized deposits, stablecoins, and digital asset products.
Among the financial institutions piloting the digital asset offering is Amarillo National Bank. Leveraging the new tool, the Texas-based bank can offer digital asset services under its own brand and on its own terms, while keeping deposit and lending relationships within local institutions.
“Banks and credit unions should not have to move to completely new technology platforms to support digital assets for their clients,” said Stablecore Co-Founder and CEO Alex Treece. “We built Stablecore to bring together all of the pieces so they don’t have to.”
The partnership is another example of how firms are rebundling financial services across the industry. Digital assets initially developed largely outside the traditional banking ecosystem, requiring consumers to establish separate relationships with crypto exchanges and wallets. Infrastructure providers like Stablecore are helping reverse that fragmentation by bringing those capabilities back inside the bank. The rebundling will offer community financial institutions an opportunity to remain the primary financial relationship by incorporating new products, especially as customer expectations evolve.
What’s interesting here is who is offering banks access to crypto. As a third-party fintech, Coinbase competes directly with this product. Consumers could go directly to Coinbase for digital assets, but the fintech is also making its capabilities available through banks so that the bank can retain the interface and relationship. In that sense, Coinbase is positioning itself to benefit from the rebundling trend rather than fight it. If consumers increasingly prefer to access digital assets alongside their other financial products, Coinbase doesn’t necessarily need to own the customer relationship; it can own the infrastructure powering it. For banks, the partnership offers another way to defend their position as the place where customers manage their broader financial lives.
AI-powered insurance decisioning firm Earnix launched its Agent Hub this week.
Integrated within the company’s AI Orchestration System, Earnix AIOS, the Agent Hub enables insurance-specific agents to directly access Earnix pricing, underwriting, and customer decision solutions to automate workflows and enhance business performance.
Headquartered in Boston, Earnix made its Finovate debut at FinovateSpring 2016.
Insurance decisioning firm Earnixunveiled its Agent Hub this week. Located within Earnix AIOS—the company’s AI Orchestration System powering pricing, rating, underwriting, and customer engagement—Agent Hub will enable more intelligent workflows by bringing together more than 25 insurance-specific agents and apps.
Agent Hub builds on Earnix’s multi-modal AI strategy, enabling agents to work across an insurer’s existing technology environment rather than as standalone assistants. Agents can draw on context from policy administration systems, data platforms, underwriting workbenches, and customer portals, while maintaining defined permissions, traceability, and human oversight. These specialized agents can then be used for high-value insurance workflows, accelerating execution, enhancing consistency and auditability, and facilitating faster, better-informed decisions, while keeping humans in the loop to ensure accountability.
Earnix’s new offering arrives at a time when insurers are facing a volatile insurance environment that is challenging their ability to grow, achieve profitability, and improve portfolio performance. AI is enabling insurers to analyze, recommend, and act faster, but this intelligence also brings with it higher standards for governance, explainability, and accountability.
“Agentic AI changes the equation because, for the first time, AI is moving from informing people to acting within insurance workflows,” Earnix CEO Robin Gilthorpe said. “That creates enormous potential to shorten the distance between intelligence and action—but it also raises the standard for trust, governance, and accountability. The winners will not be the insurers with the most agents. They will be the insurers that can turn agentic AI into better business performance while remaining firmly in control.”
Examples of the insurance-specific agents available via Earnix’s Agent Hub include a model feature mapper that connects model features to the right data variables to improve transparency and auditability for pricing and actuarial teams, and a product expert advisor that uses approved product information to provide real-time answers to product queries to facilitate faster customer guidance. Another is a premium explainer that provides easy-to-understand, personalized explanations of policy premiums.
“Agentic AI becomes much more powerful when it can work with the data, models, and business context relevant to the task,” Earnix Chief Product and Technology Officer Be’eri Mart said. “The opportunity is not simply to automate a task, but to keep the information current as risk, customer behavior, and market conditions change. That is how insurers become more agile without losing control.”
Founded in 2001, Earnix made its Finovate debut at FinovateSpring 2016. Today, the Boston, Massachusetts-based fintech processes more than four billion transactions annually and serves customers in the insurance industry in more than 35 countries across six continents.