Marco Ma of Ventus AI on Transforming Data into Behavioral Intelligence

Marco Ma of Ventus AI on Transforming Data into Behavioral Intelligence

For our latest installment of Finovate First-Timers, a new series profiling companies that recently made their debuts on the Finovate stage, we catch up with Marco Ma, Co-Founder and CEO of Ventus AI. Ventus AI helps banks personalize every touchpoint across the customer journey, boosting engagement, lifetime value, and assets under management.

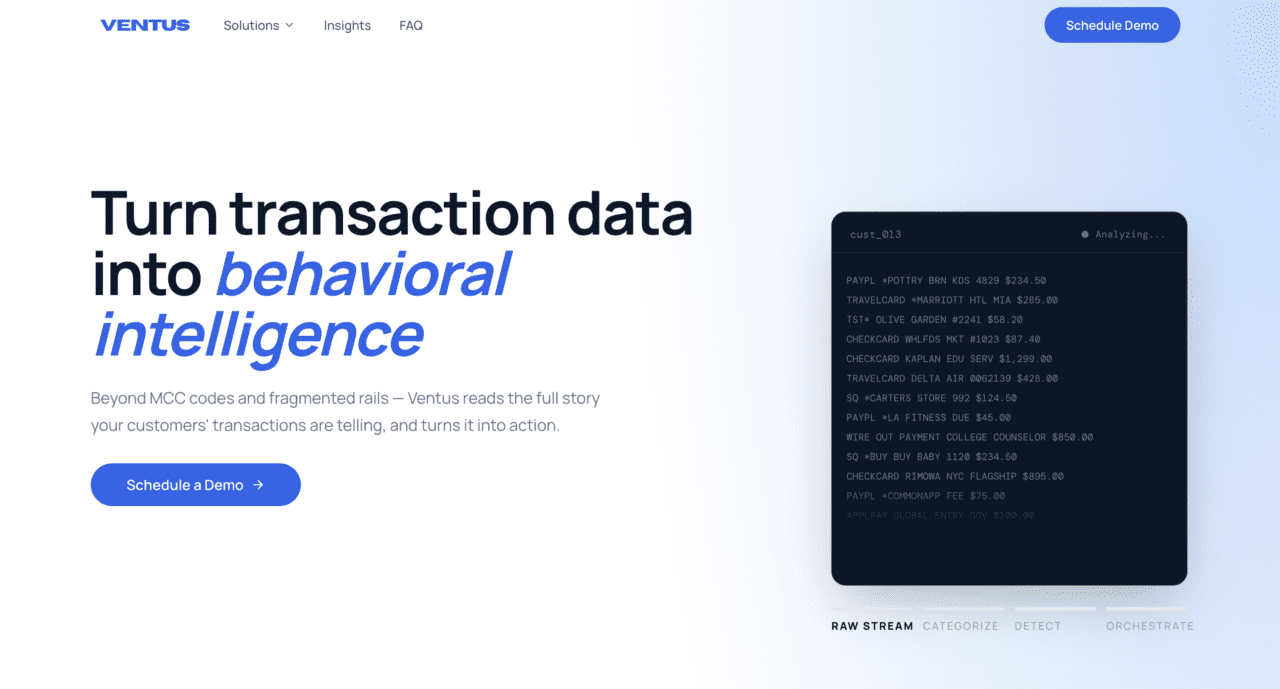
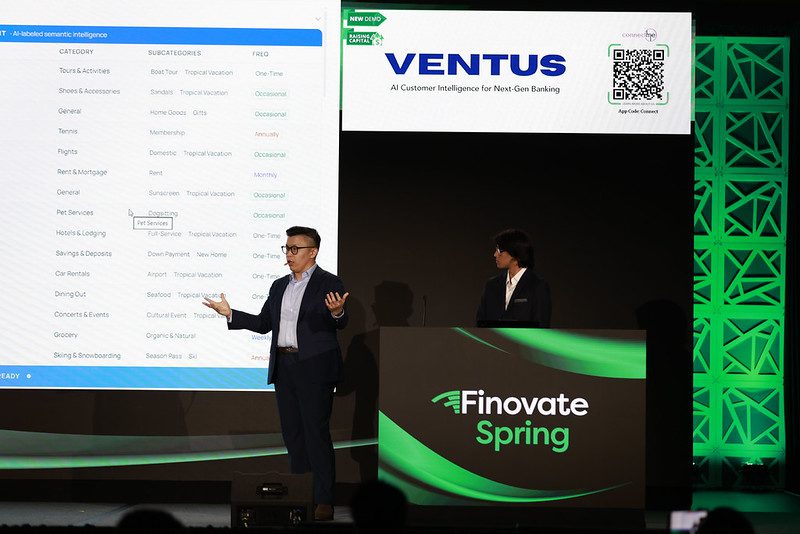
The company’s technology transforms raw transaction data into a cross-categorized behavioral intelligence layer that spans more than 3,000 spending subcategories to surface life events, dynamic personas, and real-time intent signals. Founded in 2025 and headquartered in New York, Ventus AI demoed its technology at FinovateSpring 2026 in San Diego, California.

In this week’s conversation, Ma talks about the challenges banks and credit unions face when it comes to leveraging data to create better, more personalized experiences for customers and members. He explains how Ventus AI plugs into existing stacks to provide a new analytics layer that delivers answers to questions about customer preferences and pain points without building anything new.


What problem does Ventus AI solve and who does it solve it for?

Marco Ma: Banks sit on enormous volumes of transaction data, but most of it stays trapped as raw, messy records their teams can’t actually read. The result is a lose-lose: customers get served demoralizing generic experiences which leads to lost relationships and deteriorated customer economics. We solve this for banks and credit unions that want to understand and serve their customers more deeply.

How does Ventus AI solve this problem better than other companies?

Ma: We built a proprietary customer intelligence and personalization engine. It works across every account and payment rail and detects the full picture: lifestyle patterns, life-event triggers, financial vulnerability signals, and semantic budgeting. Where most tools stop at cleaning up a merchant name, we surface what’s actually happening in a customer’s life, and we deliver it into the tools banks already use rather than asking them to rip anything out.

Who are Ventus AI’s primary customers, and how do you reach them?

Ma: US financial institutions, with our initial focus on banks and credit unions in the $1 billion to $50 billion asset range, alongside an active enterprise pipeline. We reach them through industry programs and conferences like Finovate and the Fintech Sandbox network, direct relationships built by the founding team, and warm introductions through our advisors and ecosystem partners.
Can you tell us about a favorite implementation or partnership experience?

Ma: Our favorite work is on rewards and deals. The insight that makes it special is that the same offer can mean completely different things to different people. People don’t wake up one day and say “I want to shop at Crate & Barrel.” Some people want a new coffee machine, some people want a new side table. Because we understand the behavior behind the spend, the bank can present the same deal in the way that actually resonates with each person, turning a generic coupon book experience into something that feels personal.

What in your background gave you the confidence to respond to this challenge?

Ma: We have a strong founding team with backgrounds spanning Visa, McKinsey, AWS, and Credit Suisse, along with prominent advisors from the banking world. That mix of payments, data, and institutional banking experience meant we understood both the technical problem and the way banks actually buy and adopt technology.

You demoed at FinovateSpring in May. How was the experience?

Ma: It was a great moment for us. Banking is deeply personal. It touches the most important moments in people’s lives, and our hero demo follows an expecting-parent spending pattern across rails to show we can extract major life event signals and orchestrate the existing tech stack—rewards, product, relationship—to be personalized to help this customer through this journey. Demoing that live on the main stage reminded us why this matters: done right, this technology lets a bank show up for someone at exactly the moment it counts. We’re returning for the Fall show.
You were accepted into the Fintech Sandbox Data Access Residency. What is it, and why does it matter?

Ma: Fintech Sandbox gives early-stage fintech companies access to high-quality financial data and infrastructure to build and refine their products. For us, it’s meaningful because behavioral intelligence is only as good as the data it learns from. The residency accelerates our ability to develop and validate our engine against real, rich datasets, which directly strengthens what we deliver to banks.

What are your goals for the rest of 2026 and into next year?

Ma: Grow our pipeline through business development, move active conversations into live deployments, return to the Finovate main stage in the Fall, and close our current funding round. Beyond that, we’re heads-down building, deepening the behavioral signal we deliver and expanding what banks can do with it.


Photo by Floriane Vita on Unsplash
FreeAgent Unveils New AI Tool for Landlords

FreeAgent Unveils New AI Tool for Landlords
  • Accounting software provider FreeAgent launched a new AI-powered tool to enable landlords to capture and categorize rental statements.
  • The new offering helps bookkeepers and accounting firms better serve their customers in property management as the Making Tax Digital initiative comes into effect throughout the UK.
  • Headquartered in Scotland and founded in 2007, FreeAgent made its Finovate debut at FinovateEurope 2013 in London.

Scotland-based fintech FreeAgent unveiled a new feature for its FreeAgent for Landlords accountholders. The new AI-powered tool enables rental statement capture and categorization, transforming letting agent statements into entries that are structured, categorized, and reconciled automatically.

“If you work with landlord clients, you’ll know exactly what we mean,” FreeAgent noted in a blog post announcing the new offering. “Every month, letting agents send out rental statements. On paper, they look straightforward enough. But a single statement can be a jumble of rental income, management fees, repair costs, contingency balances, and a net payout.” The challenge for accountants is recording all of this information accurately, especially for tax purposes. With data as diverse as this, separate categories for rent invoices, bills for fees and repairs, and more will have to be created and eventually reconciled against a final bank payment. For accountants managing a large number of landlord clients, this work can become overwhelming.

“Our new feature captures and categorizes rental statements using AI to lighten the load,” FreeAgent explained. “All you need to do is upload the letting agents’ statement. Then FreeAgent will extract rental income and fee data, match line items to the correct property, assign the right accounting categories, and reconcile the final net bank payment in seconds.”

Platforms like FreeAgent have become valuable resources for companies looking to comply with the Making Tax Digital (MTD) initiative launched by the UK’s HM Revenue and Customs (HMRC) office. MTD is designed to modernize the country’s tax system by fully digitizing all aspects of tax administration. The goal is a more effective, efficient, and transparent process for taxpayers by reducing errors, delivering real-time information about tax liabilities, and simplifying tax compliance via digital record-keeping and reporting.

“We know that the real challenge of MTD isn’t just about hitting submission deadlines,” FreeAgent Director of Product Craig Clarke noted. “Overcoming the manual, disjointed bookkeeping that makes managing property finances a headache is going to be just as tall a hurdle. That’s exactly why we built FreeAgent for Landlords—a product specifically designed to make accounting for rental income as simple as possible.”

A Finovate alum since 2013, FreeAgent offers accounting software and support for small businesses and their accountants and bookkeepers. The company has more than 200,000 users who rely on FreeAgent’s software to manage finances from daily administration to big-picture, financial planning.


Photo by Adam Wilson on Unsplash

UK Credit Union Selects Illuma to Protect from Voice Fraud

UK Credit Union Selects Illuma to Protect from Voice Fraud
  • Kentucky’s UK Credit Union is deploying IllumaSHIELD to strengthen fraud prevention and member authentication across its contact center and self-service channels.
  • IllumaSHIELD shifts away from security questions and passwords as banks and credit unions adopt voice biometrics to combat AI-powered fraud, including voice cloning and social engineering attacks.
  • Illuma’s technology continuously authenticates members as they speak, helping financial institutions reduce friction, shorten call times, and improve security without disrupting the customer experience.

Voice authentication solutions provider Illuma announced its latest partnership this month. The Texas-based company is teaming up with Kentucky-based UK Credit Union to help the credit union reduce fraud.

Specifically, UK Credit Union will implement IllumaSHIELD to bring authentication and fraud prevention capabilities to its contact center and self-service channels. IllumaSHIELD, which was unveiled at FinovateFall 2020, is the company’s voice security platform that leverages real-time voice authentication technology that passively verifies members as they speak, which reduces reliance on security questions and ultimately minimizes call handle time. Because the platform continuously evaluates risk throughout the interaction, it allows the credit union to step up authentication only when needed.

“AI-driven fraud is forcing financial institutions to rethink how they secure the voice channel,” said Illuma Founder and CEO Milind Borkar. “UK Credit Union is taking a forward-looking approach by adopting voice security that continuously verifies identity, blocks threats in real time, and improves both the member and agent experience—while eliminating friction from every interaction.”

As advances in generative AI have made it easier for fraudsters to clone voices, automate social engineering attacks, and bypass traditional knowledge-based authentication methods, financial institutions are having to secure voice interactions beyond asking for security questions and passwords. By providing continuous, biometric forms of identity verification, Illuma is authenticating users based on how they speak rather than what they know. Crucially, platforms like IllumaSHIELD aim to help banks and credit unions deliver this authentication without friction.

UK Credit Union anticipates that IllumaSHIELD will help it move beyond traditional knowledge-based authentication. “At UK Credit Union, protecting our members while delivering a seamless experience remains a top priority,” said UK Credit Union President and CEO Ryan Ross. “Partnering with Illuma allows us to modernize how we approach authentication and fraud prevention while creating a faster, more natural experience across our service channels.”

Headquartered in Plano, Texas, and founded in 2016, Illuma specializes in voice authentication solutions for credit unions and community banks. In addition to IllumaSHIELD, the company also offers advanced fraud prevention, adaptive multi-factor authentication (MFA), deepfake detection, and human-AI collaborative intelligence. The company most recently demoed at FinovateSpring 2025, where it won Best of Show for its deep fake detection technology.

Introducing IMPACT: A New Event for Fintech Founders and Investors

Introducing IMPACT: A New Event for Fintech Founders and Investors

For years, Finovate has helped fintechs connect with banks and other customers. This September, we’re launching a new event designed to help fintechs connect with the people who fund them.

Taking place on September 11 alongside FinovateFall in New York, IMPACT: Funders & Founders brings together fintech startups, scaleups, and investors for a full day of networking, content, meetings, and startup pitches. While FinovateFall is built around helping fintech companies meet potential customers, IMPACT is designed to help fintech founders build relationships with investors.

Who Should Attend?

IMPACT is for fintech founders and their teams and investors.

On the startup side, the event is geared toward fintech startups and scaleups, particularly companies that have raised up to a Series A round. On the investor side, we’re bringing together venture capital firms, angel investors, private equity investors, family offices, and limited partners.

Whether a company is actively fundraising or simply looking to build relationships for the future, IMPACT offers an opportunity to connect with investors who understand the fintech landscape.

Why Are We Creating IMPACT?

While investors have long attended Finovate events, we’ve seen growing demand for a dedicated event focused specifically on fundraising, investing, and startup growth.

IMPACT creates structured opportunities for founders and their teams and investors to connect through pre-arranged, one-on-one meetings, networking sessions, roundtable discussions, and live startup pitches featuring investor feedback and Q&A. The goal is to create an event where meaningful conversations and connections can happen more efficiently than through traditional networking alone.

What Can Attendees Expect?

The event features two dedicated content tracks.

The Investor Stage will explore topics such as AI in investment operations, emerging fund structures, venture capital trends, and the future of fintech investing.

The Founder & Startup Stage will focus on fundraising strategy, go-to-market planning, scaling a fintech company, building industry connections, and leveraging AI for growth.

In addition to attending content sessions, eligible startups can participate in the IMPACT Zone, a dedicated showcase area in Finovate’s Exhibit Hall where companies can meet investors and fellow founders throughout the day. Startups raising pre-seed through Series A funding can also apply to deliver a four-minute pitch in front of investors.

How Is IMPACT Different from FinovateFall?

While IMPACT takes place alongside FinovateFall, the two events serve different purposes.

FinovateFall helps fintechs connect with buyers and partners through live demos and networking. IMPACT helps fintechs connect with investors and advisors who can help fuel their next stage of growth.

Together, the events support fintech companies throughout their journey in everything from raising capital to winning customers. Whether you’re a founder seeking your next investor, a startup executive looking to expand your network, or an investor searching for the next breakout fintech company, IMPACT offers a new way to connect with the people shaping the future of financial services.

If you’d like to register or learn more, check out our website to learn about opportunities that best fit your needs.

Tru Cooperative Bank Partners with DataVisor for Fraud Prevention

Tru Cooperative Bank Partners with DataVisor for Fraud Prevention
  • Fraud and financial crime prevention platform DataVisor has partnered with Tru Cooperative Bank (formerly First West Credit Union).
  • Via a pre-integrated deployment with VeriPark’s digital banking platform, Tru Cooperative Bank will leverage DataVisor’s technology to enable real-time fraud detection across the full digital banking journey.
  • Headquartered in Mountain View, California, and founded in 2013, DataVisor made its Finovate debut at FinovateFall 2023 in New York.

AI-powered fraud and AML platform DataVisor will put its fraud prevention technology to use protecting the members of Tru Cooperative Bank (formerly First West Credit Union). The offering will be delivered via DataVisor’s pre-integrated deployment with VeriPark’s VeriChannel digital banking platform, and will provide Tru Cooperative Bank with seamless, out-of-the-box fraud protection.

VeriPark is a London-based fintech, founded in 1998, that helps financial institutions embed real-time decisioning into every customer interaction, from omnichannel delivery and customer engagement to branch automation and loan origination. The company made its Finovate debut at FinovateMiddleEast 2019 in Dubai. Ozkan Erener is CEO.

DataVisor’s platform provides real-time fraud detection across the full digital banking journey, covering onboarding, login, profile changes, Interac e-Transfer, and billpay. The solution offers future-proof defense against a growing range of sophisticated financial crimes, replacing traditional solutions and enabling growth without introducing additional friction for members.

“As we build on our transition to a federally regulated cooperative bank, protecting our members is fundamental in everything we do—especially as we continue to evolve our digital banking experience,” Tru Cooperative Bank Chief Transformation & Information Officer Darrell Jaggers said. “DataVisor strengthens our ability to prevent fraud earlier across the digital journey, supporting a secure, seamless experience our members can trust.”

Formerly First West Credit Union, the financial institution transitioned to Tru Cooperative Bank in April 2026. The credit union’s members voted with 84% approval to apply for the right to operate under federal regulation rather than simply provincial jurisdiction, enabling the firm to serve members outside of British Columbia and to operate nationally across Canada. The name “Tru Cooperative Bank” was adopted with 87% approval from the institution’s members. While still operating its four regional brands in British Columbia: Envision Financial, Island Savings, Valley First, and Enderby & District Financial, Tru Cooperative Bank is the fourth federally regulated credit union in Canada since 2012. The financial institution has more than $20 billion in assets, nearly 300,000 members, and 45 branch locations.

“As financial crime grows more sophisticated, credit unions need a modern, AI-driven defense that prevents fraud in real time—not one that catches up after the fact,” DataVisor Co-Founder and President of Technology and AI Yinglian Xie said. “We’re proud to support Tru’s digital banking journey through our partnership with VeriPark, and to continue expanding DataVisor’s leadership in fraud prevention across the Canadian market and the credit union community.”

Founded in 2013 and headquartered in Mountain View, California, DataVisor made its Finovate debut at FinovateFall 2023 in New York. At the conference, the company demonstrated how its fraud and risk platform integrates any data source, including third-party data, and combines a rules engine, device intelligence, a decision engine, and case management to increase detection and minimize fraud losses. DataVisor’s platform processes 30 billion events a year, boasts of more than 15,000 queries per second in live production, and delivers real-time scoring latency of less than 100 milliseconds.

DataVisor’s partnership news with Tru Cooperative Bank follows the company’s launch of Vera, a suite of conversational AI agents designed for financial crime prevention. Vera is built into DataVisor’s platform to help teams with fraud detection, strategy optimization, investigation, and reporting, while ensuring that human oversight, auditability, and control remain part of the process.

“With Vera, for the first time, financial institutions can outpace AI-driven attackers,” Xie explained when Vera was unveiled in April. “By unlocking unparalleled speed and intelligence, we are redefining the playing field and enabling a more proactive defense against AI-driven fraud.”


Photo by Aditya Chinchure on Unsplash

Fintech Rundown: A Rapid Review of Weekly News

Fintech Rundown: A Rapid Review of Weekly News

We have officially entered the final week of June, which marks the ending of the first half of 2026. As we close out the first six months of this year, here’s a look at the top news headlines for this week. We’ll continue to add more announcements as the week progresses.


Payments

Nuvion teams with Visa Direct to strengthen real-time global payout capabilities for businesses operating across borders.

Bankaktiebolaget Nordiska (Nordiska) partnered with Finastra’s Swift Service Bureau to enhance access to the global Swift network and Sweden’s central payment rails.

E-commerce, banking, and payments ecosystem Bir teams up with payments platform Paysend to launch international money transfers in Azerbaijan.

Investing

BitDelta Pro selects Iress to power multi-asset trading platform.

AI in Banking

Lloyds targets more than 1,000 new AI roles as it expands agentic AI capability.

Santander empowers employees with AI in order to generate €1 billion in business value.

Embedded finance

Embedded B2B payments infrastructure provider TransferMate inks a strategic partnership with AI-native, agentic, source-to-pay spend management platform Raindrop Systems.

Debt markets

9fin appoints Amit Lalwani as Chief Revenue Officer to lead next phase of global growth.

Small business banking

Rippling launches Business Banking for same-day payroll processing.

DeFi

Blockchain data platform for enterprises Allium raises $40 million in Series B funding.

Ripple receives preliminary approval for its Crypto Asset Service Provider (CASP) license in the EU.

Open finance

Open finance infrastructure provider Spare announces a strategic partnership with UAE-based property technology platform Rewa.

Lending

AI-native loan origination platform for community and regional banks Lama AI raises $20 million in Series A funding.

Credit unions

Jordan Credit Union chooses Mahalo Banking for its Thoughtful Banking platform.


Photo by Luis Quintero

Wise Acquires International Living Guidance Expert Expatica

Wise Acquires International Living Guidance Expert Expatica
  • Wise has acquired expat resource Expatica, gaining access to a website that attracted more than 7 million visits in 2025 from people researching and navigating life abroad.
  • The deal gives Wise an earlier touchpoint with prospective customers, allowing it to build brand awareness and trust before consumers choose a bank, payments provider, or money transfer service.
  • Wise plans to expand Expatica’s content and geographic reach, strengthening its position among the growing global population of expats and internationally mobile consumers.

Cross-border payments fintech Wise announced this week that it has acquired Expatica, an online resource for people living and working abroad. The move places Wise front and center among one of its most important customer groups, expats.

Expatica was founded in 2000 to provide local guidance for people living internationally. The company’s website serves as a directory that covers topics such as relocation, housing, finance, lifestyle, healthcare, and immigration. The website reached more than 7 million visits in 2025, with its largest audiences coming from France, Germany, Portugal, and Spain.

According to the UN, 304 million people (3.7% of the world’s population) were international migrants in 2024. With Expatica serving as a long-standing expert in the field, the acquisition will help Wise reach prospective expats earlier in their relocation journey, increasing the company’s visibility among a broader international audience.

By acquiring Expatica, Wise gains access to consumers when they are researching a move abroad—often before they have selected a bank, payments provider, or money transfer service. That early engagement could help Wise build brand awareness and trust long before a customer needs to move money internationally.

“Expatica has spent years helping people make sense of life abroad with practical, locally relevant guidance. That makes it a strong fit for Wise, because we already support millions of people whose lives span borders,” said Wise Head of Owned Sites Danny Butler. “When people are planning, moving and settling into life abroad, money is a big part of that experience—from getting paid to sending, spending and managing money across borders. Wise is built for those moments.”

Wise plans to maintain and augment Expatica’s website, with investments planned to expand the company’s content, local coverage, markets, and languages over time. As Expatica’s users leverage its resources to navigate life in a new country, Wise wants to become a familiar and relevant choice for expats who need to manage money across borders.

Wise was founded in 2011 under the name TransferWise to facilitate cross-border payments while bringing transparency to the fees involved. The company serves 19 million active customers worldwide, processing over $240 billion in cross-border transactions.


Photo by Gustavo Fring

U.S. Bank’s Deepa Chatterjee: The Future of SMB Banking Is Personalization, Not More Products

U.S. Bank’s Deepa Chatterjee: The Future of SMB Banking Is Personalization, Not More Products

For years, bank-fintech relationships often followed a predictable path. Banks identified promising startups, tested their technology, and viewed acquisition as the ultimate endgame. Today, that dynamic is changing.

At FinovateSpring 2026, I sat down with Deepa Chatterjee, SVP of Business Development and Go-to-Market for Small Business Banking at U.S. Bank, to discuss how bank-fintech partnerships are evolving, where banks are competing with digital-first challengers, and what the future of small business banking looks like.

One of the most interesting takeaways from our conversation was how dramatically the relationship between banks and fintechs has changed. While banks once viewed fintech partnerships as potential acquisition opportunities, many are now embracing deeper, longer-term collaborations. “The way that we worked with fintechs was primarily thinking of potentially acquiring them,” said Deepa. “Now that tha markets have changed we are far more likely to work and partner with fintechs in a much deeper way, and so ownership is not necessarily on the table.”

Deepa Chatterjee is SVP of Business Development and Go-to-Market for Small Business Banking at U.S. Bank. She leads business development, partnerships, sales enablement, product marketing, data insights, and automation initiatives for the bank’s small business segment. Before joining U.S. Bank, Chatterjee held leadership roles at Dayforce and Oportun and spent more than a decade at American Express in strategy, marketing, and business development positions. She holds a bachelor’s degree in economics from Barnard College at Columbia University and an MBA from the Yale School of Management.

U.S. Bancorp, the parent company of U.S. Bank, is one of the largest banking institutions in the United States, serving millions of consumer, business, commercial, and institutional clients. The bank offers a broad range of financial services, including business banking, payments, treasury management, merchant acquiring through Elavon, lending, and wealth management solutions. U.S. Bank has increasingly expanded its digital capabilities through fintech partnerships and embedded financial services designed to help small businesses streamline their financial operations.


Photo by Vitaly Gariev

Coinbase Wants to Become Your Primary Financial Platform

Coinbase Wants to Become Your Primary Financial Platform
  • Coinbase is evolving beyond crypto into an “everything exchange,” adding AI-powered advice, agentic trading, tokenized stocks, and expanded credit offerings in a bid to become consumers’ primary financial platform.
  • The new launches highlight two major fintech trends: AI moving from financial guidance to autonomous action, and the continued blurring of lines between banks, brokerages, fintechs, and crypto platforms.
  • By combining investing, lending, payments, wealth management, and AI tools into a single experience, Coinbase is betting that convenience and integration will define the next generation of financial services.

Crypto exchange platform Coinbase wants users to think of it as much more than a cryptocurrency exchange. This week, the company unveiled a series of new products as part of its effort to become a primary financial platform for consumers.

Since it was founded in 2012, the company has been slowly building out a comprehensive banking platform. What started as a crypto wallet has evolved into a full service financial platform with debit and credit cards, prediction markets, derivatives, crypto-backed lending, and more.

“Coinbase is building the future of finance, where you can manage your money with just one interface, and one login,” the company said in its blog post announcement. “We’re saying “no” to financial fragmentation, and the new products we’re introducing today take us several steps closer to that future.”

Here’s a rundown of the top five new tools and features Coinbase is unveiling this week and why each matters:

Coinbase advisor

Coinbase has launched an AI financial advisor to provide personalized financial guidance based on a customer’s holdings and financial situation. While many fintechs are hesitant to give financial advice because of the regulatory requirements, Coinbase registered with the SEC as a Registered Investment Advisor and with the CFTC and NFA as a Commodity Trading Advisor.

Why it matters: The move places pressure on both traditional financial institutions and fintechs offering robo-advisory technology to offer more sophisticated, real-time financial guidance at a lower cost. Offering AI-powered financial advice caters to consumers of all levels because it allows them to communicate using natural language, comes at a lower cost, and does not require the consumer to change their existing habits or switch apps. When compared to traditional wealth management, which has historically been reserved for affluent customers, the advisor tools will have a wider reach and be a valuable tool for customer retention.

Agentic trading

Customers can deploy AI agents to execute personalized trading strategies on their behalf while maintaining ultimate control over the account. Investors can confine their agent to an isolated sub-account and set limits around capital allocation, asset permissions, and trade sizes. Coinbase joins Robinhood, which launched agentic trading earlier this month, in pioneering this feature.

Why it matters: With agentic tools, AI implementation makes the leap from informing decisions to taking action. Having an agent move funds on an investor’s behalf can help with treasury management, cash flow management, and micro-investing decisions that would be too tedious for human investors.

Expanded stock and options trading

In a move that continues to expand Coinbase beyond crypto, the company announced broader access to stock trading and options trading. The company first unveiled stock trading in December 2025 and expanded it to all US users in February of this year. This week’s announcement highlights the next phase of Coinbase’s strategy that will focus on transforming it into a full-service financial platform.

Why it matters: Even though stock trading is not new for Coinbase, it highlights the company’s new position as a universal investment platform. Similar to how Robinhood expanded into banking and SoFi branched out into investing, Coinbase’s move to broaden its offerings will make the company a more holistic banking platform. The move is also an example of how lines across financial services are beginning to blur. The distinction between crypto platforms, brokerages, and banks is increasingly disappearing.

Tokenized US stocks

Coinbase plans to enable non-US customers to trade tokenized US equities around the clock. Tokenized stocks are backed 1:1 by the underlying asset, representing true equity ownership, including dividend payouts and complete shareholder rights. Additionally, investors will be able to lend their shares to earn yield, use them as collateral for a loan, or even gift them directly to someone else.

Why it matters: Tokenized trading offers 24/7 trading, potentially faster settlement, and broader global access to US markets. This changes the traditional models of limited trading hours, clearinghouses, and custodians that have dictated the legacy stock market since its inception.

Expanded access to Coinbase One Card

The company expanded USDC-backed access to the Coinbase One Card, a card built for users who are generally overlooked by traditional credit bureaus. The update allows users who aren’t approved for a traditional line of credit to secure a Coinbase One Card using USDC as collateral. The card offers Bitcoin rewards on everyday purchases while paying rewards on the underlying USDC deposit every week.

Why it matters: Offering a credit builder card allows Coinbase to tap into a new set of users who have historically been ignored by traditional financial institutions. And because Coinbase’s credit builder card still pays out rewards and offers additional benefits like the new Travel Portal that provides cardholders access to all of the same travel protections and benefits offered through the American Express Network.

From the looks of these new products and tools, it appears that Coinbase is making a bid to become a full-service financial institution without calling itself a bank. Combining investing, lending, payments, wealth management, and AI-powered tools into a single experience will allow Coinbase to provide a more unified experience to customers that care less about traditional financial categories and more about convenience. As the lines between banks, brokerages, fintechs, and crypto platforms continue to blur, Coinbase’s latest moves offer a glimpse into what the next generation of financial services may look like.

Three Top Takeaways from the HSBC, Google Cloud Partnership

Three Top Takeaways from the HSBC, Google Cloud Partnership

A newly announced, multi-year partnership between HSBC and Google Cloud will enable the financial institution to work with engineering teams from Google Cloud and DeepMind to develop new AI-powered tools and capabilities. The partnership will allow HSBC to benefit from access to Google’s latest agentic AI capabilities including Gemini and the Gemini Enterprise Agent Platform.

The agreement will enable more than 200 new AI use cases for HSBC over the next two years, with a focus on the highest value initiatives for investment and delivery. HSBC estimates each of these could return more than $100 million in either direct revenue gains or broader efficiency improvements.

“AI is becoming one of the defining technologies of our time, allowing us to create a personalized experience for each customer, delivered in real time and at scale, while keeping human judgment, decision-making, and accountability at the core,” HSBC Group CEO Georges Elhedery said. “A partnership like this one with Google Cloud helps us empower our colleagues with the tools they need to be future-ready, and supports our work in building a simple, agile, faster, and more personal HSBC.”

These new opportunities fall into three main categories: wealth management, fraud and financial crime, and support for frontline/relationship manager client service. Here is a closer look at each element of the new partnership and its implications for AI in banking and financial services.


Hyper-personalized wealth management

The partnership will enable HSBC to combine smarter, AI-driven insights with the expertise of relationship managers. This will transform the way the bank serves its wealth management clients and empower thousands of relationship managers to provide proactive, customized financial support and real-time advice to customers at every stage of the client journey.

What this says about AI: The ability to achieve hyper-personalization is increasingly regarded as the Holy Grail of customer engagement. AI enables banks and other financial institutions to leverage their data to better understand the unique needs of individual customers, businesses, and enterprises. This allows them to not only develop customized solutions and services that directly respond to each client, but also to respond quickly to shifting preferences and even anticipate emerging trends and circumstances that customers might not immediately recognize.

What this says about banks: More and more banks are realizing the opportunities in delivering wealth management services. This is driven by a number of factors, from the so-called Great Wealth Transfer and the growing number of high-net-worth households to the democratization of wealth management brought about by fintechs and robo-advisors.

Wealth management is also an area where more banks and financial institutions can provide greater value, especially for mid-tier and non-HNW customers for whom bespoke, concierge-level wealth management services are typically out of reach. AI plays a key role here, helping translate client data—from financial records to conversations with advisors—into actionable insights that lead to better and more accurate financial guidance. The fact that AI is able to provide this at a competitive cost means that these higher-value, higher-margin services can be offered to a wider range of customers.

Stronger financial crime risk management

HSBC will leverage its relationship with Google Cloud to deploy both generative and agentic AI to build a financial crime architecture that identifies fraud risk as early as possible. The bank’s goal is to detect and intervene twice as quickly once risk is detected across the nearly one billion transactions monitored by the bank every month for financial crime and fraud.

What this says about AI: Helping financial institutions detect fraud faster, including real-time monitoring, is one of the most broadly accepted use cases for AI technology. AI is able to analyze vast amounts of data in real time to detect suspicious patterns and activities that traditional, rules-based systems can miss, while also providing predictive analytics that can enable institutions to anticipate potential financial crime risks before they materialize.

What this says about banks: For banks and other financial institutions, financial crime risks have only grown larger in recent years. The Nasdaq Verafin 2026 Global Financial Crime report indicated that the economic impact of financial crime internationally has grown by $1.3 trillion in the past two years from 2023 to 2025. With regard to fraud-specific losses, fraud scams were the fastest-growing category costing $62 billion in 2025 alone. In the face of this, moves like HSBC’s to embrace AI-powered solutions for fighting fraud have become increasingly common. The 2026 Global Financial Crime report noted that 75% of financial institutions said they planned to boost their use of AI for financial crime detection.

Enhanced client service for frontline and relationship managers

Courtesy of the partnership, HSBC’s frontline staff and relationship managers will have expanded access to an AI-powered decision assistant that has already proven capable of reducing administrative and client meeting prep times from hours to minutes for thousands of users. HSBC will also codify regulatory procedures into an AI structure to give bankers consistently structured options and analysis to enhance decision-making and provide faster insights without losing human judgment and oversight.

What this says about AI: One of the great promises of automation and AI is freeing human labor and talent from mundane, often tedious, and inefficient manual processes. The fact that so much of AI innovation is being designed for in-house use by frontline workers and employees to enable them to better serve their clients underscores that AI, in its best light, actually creates space for more human connections between customers and service providers.

What this says about banks: Empowering frontline workers and relationship managers with AI-powered tools is helping a growing number of banks boost efficiency and reduce costs. From enhancing underwriting analysis to streamlining workflows, financial institutions are increasingly comfortable with AI-powered tools. This is especially the case when institutions deploy these solutions as complements to existing systems rather than as replacements for them.


Photo by Kit Suman on Unsplash

Ripple Contributes to Flutterwave’s Series E Round

Ripple Contributes to Flutterwave’s Series E Round
  • Ripple participated in Flutterwave’s Series E round, helping push the African payments company’s total funding above $500 million and valuing it at $3.2 billion.
  • The partnership will embed Ripple’s RLUSD stablecoin and XRP Ledger into Flutterwave’s payment infrastructure to support faster settlement, liquidity management, remittances, and cross-border payments.
  • The deal highlights the growing race to control stablecoin infrastructure, with Ripple seeking to establish RLUSD and XRPL as foundational components of a major payments network rather than simply offering a standalone digital asset.

African payments infrastructure company Flutterwave revealed that it has received an undisclosed amount of funding from digital asset company Ripple, which contributed to its Series E Round this week. The funds boost Flutterwave’s total raised to more than $500 million.

Notably, the new round values Flutterwave at $3.2 billion as the company moves into the next phrase of its stablecoin strategy that integrates stablecoin-powered settlement, liquidity, and remittance rails. The company hopes this new infrastructure will empower African businesses to bypass frictions associated with legacy payment systems.

Ripple is coming on as a strategic investor, and as such will embed Ripple’s stablecoin, RLUSD, into its payment rails and Send App to create a stablecoin-first payment architecture that eliminates traditional bottlenecks. Flutterwave will also leverage the XRP Ledger (XRPL) for faster transaction clearing and will deploy an API to bridge its domestic network with Ripple’s global payments network.

“Flutterwave has built one of the most advanced payments networks in Africa, and as its infrastructure evolves, stablecoins are becoming central to that story,” said Ripple Managing Director MEA Reece Merrick. “Our investment will establish RLUSD within that infrastructure, with Flutterwave driving stablecoin flows over the XRPL and deepening its role as a settlement layer for real-world payments across the continent. Together, we also plan to bring Ripple Payments’ speed and efficiency to cross-border transactions in the region, opening up faster, lower-cost financial services to businesses and consumers at scale.”

Flutterwave will use the funds to bridge traditional financial systems with next-generation digital asset infrastructure. Since it was founded in 2016, Flutterwave has processed over a billion transactions worth over $50 billion. The company accepts payments in more than 30 currencies, processing an average of 500,000 payments each day. In addition to its payments technology, Flutterwave also offers invoicing technology, business loans, and analytics tools. Adding to these capabilities, the company agreed to acquire Mono, an open banking technology company, earlier this year.

This funding announcement and strategic partnership are both reminders of the race for ownership and control in the new stablecoin economy. While Ripple is investing in Flutterwave’s growth, it is also bidding to establish RLUSD and XRPL as foundational components of a major payments network, controling how stablecoins move through the global financial system.


Photo by Damilare Adeyemi

Zocks Launches Client Queries to Transform Advisor Conversations into Actionable Insights

Zocks Launches Client Queries to Transform Advisor Conversations into Actionable Insights
  • AI platform for financial services Zocks has launched its Zocks Client Queries solution.
  • Zocks Client Queries enables financial advisors to uncover potential growth opportunities and respond to unmet client needs by querying data using plain language.
  • Founded in 2022 and headquartered in San Francisco, California, Zocks made its Finovate debut at FinovateSpring 2026. Mark Gilbert is Co-Founder and CEO.

AI platform for financial services Zocks unveiled its Zocks Client Queries solution this week. The new offering is an agentic AI product that enables financial advisors and enterprises to uncover organic growth opportunities and unmet client needs in seconds, using plain language. Advisors can use Client Queries to ask questions such as “which clients have a 401(k) with a previous employer that we could consolidate” or “which clients have a review due this quarter with over $500,000 in held-away assets,” and Client Queries will deliver a list of clients who fit those parameters. The solution then presents advisors with a set of automated next steps, including sending a personalized email, creating opportunities in a CRM system, or scheduling a meeting.

Zocks Client Queries also helps advisors address potential service gaps. Advisors, for example, can inquire, “which clients have a significant age milestone in the next 90 days, and we haven’t spoken with them in the past 12 months?” or “which clients mentioned a major life change but haven’t updated their estate plan?” allowing advisors to deliver proactive service to all clients regardless of account size.

“Every advisor-client relationship and conversation contains signals that point to the next opportunity, whether that’s a life change, a servicing need, or a held-away asset,” Zocks CEO Mark Gilbert said. “With Client Queries, firms can query across personal and financial information to operationalize those signals for every advisor, and deliver on the scale and consistency that manual processes can’t. What once required hours of research can now happen in minutes, at a fraction of the cost.”

Zocks leverages AI-powered intelligence to continuously build and maintain a comprehensive profile for all clients, drawing from CRM records, financial plans, tax, portfolio, estate, and insurance data, as well as conversations, meetings, emails, and documents shared with advisors. Zocks Client Queries analyzes these profiles in real time to deliver actionable lists and automated workflows in seconds. This gives advisors the opportunity for deeper insights and greater personalization compared to traditional lead generation and prospecting strategies.

“For our advisors, Client Queries removes the friction between having an idea to engage clients and quickly acting on it,” RFG Advisor VP of Technology and Operations Jordan Hutchison said. “For the enterprise, it gives us a way to operationalize growth across every advisor’s book simultaneously.”

Founded in 2022 and headquartered in San Francisco, California, Zocks made its Finovate debut at FinovateSpring 2026. At the conference, the company demonstrated how its AI assistant for financial advisors automates administrative tasks including meeting prep, account opening, document processing, and more. Zocks’ technology transforms client conversations into structured insights that bolster relationships and support business growth.

Zocks’ AI assistant saves advisors more than 10 hours a week, enabling them to build plans and onboard clients faster, discover new growth opportunities, anticipate client needs, and scale their business. Zocks counts more than 5,000 firms as its customers, including six of the nine Barron’s Top Mega RIAs and two of the top three life insurance carriers.


Photo by Shen Pan on Unsplash