OnePay Teams with Upgrade to Add Personal Loans to its Banking App

OnePay Teams with Upgrade to Add Personal Loans to its Banking App
  • Walmart-backed OnePay has partnered with Upgrade to launch personal loans ranging from $1,000 to $50,000 directly within the OnePay app.
  • OnePay will use existing customer data to streamline applications and underwriting, potentially extending same-day offers to eligible users.
  • The partnership advances OnePay’s super app ambitions while giving Upgrade access to a larger customer base and highlighting fintech’s broader rebundling trend.

Walmart-backed digital banking platform OnePay is getting an upgrade this week. The New York-based company has teamed up with alternative lender and fellow digital banking platform Upgrade to launch Personal Loans, bringing a new element into its banking app.

With the new Personal Loans product, OnePay will allow eligible borrowers to apply for a loan ranging from $1,000 to $50,000, receive and accept an offer with APRs ranging from 7.74% to 35.99%, and pay back their loan within the OnePay app. The company sees the new product as a significant step forward in its mission to make everyday financial services simpler, more accessible, and more useful.

“Getting access to credit in America today is harder than it should be,” said OnePay CEO Omer Ismail. “It’s never been more important to give consumers access to financing that’s simple, transparent, and meets them where they already are—and we’re excited to partner with Upgrade to introduce another financing option for our customers with OnePay Personal Loans.”

Because it can leverage information customers have already shared, OnePay can reduce repetitive entry during the application process, minimizing friction. Additionally, because OnePay is able to leverage customer information such as their average daily balance, overdraft occurrences, and spending habits for underwriting purposes, it is able to extend financing offers as soon as the same day to some of its active customers.

OnePay has tapped San Francisco-based Upgrade for the lending infrastructure and expertise, offering it the ability to offer larger-dollar lending directly within its app. Founded in 2017, Upgrade offers checking and savings accounts, personal loans, credit cards, and rewards programs that focus on low fees and responsible credit usage to help consumers improve their financial lives. With more than 7.5 million customers, Upgrade has facilitated over $42 billion in credit with tools such as its Upgrade Card, which encourages customers to pay off balances quickly and avoid revolving debt and build credit responsibly.

“Our personal loans offer consumers the breathing room they need to get on the best financial path,” said Upgrade CEO and Co-founder Renaud Laplanche. “We’re proud that this partnership makes that resource more accessible to millions of OnePay customers.”

The addition of a personal lending product is a major step for OnePay, which has been building out its banking super app since it was founded in 2021. By embedding unsecured lending directly into its app, OnePay is evolving beyond a digital wallet and deposit platform into a more comprehensive financial services hub. The partnership is another example of recent rebundling efforts in fintech. Rather than building every product in-house, digital banking providers are increasingly partnering with specialized fintechs to quickly expand their offerings.

For Upgrade, the deal opens the door to OnePay’s growing customer base, while OnePay gains proven lending infrastructure and underwriting expertise without taking on the complexity of developing it internally. As competition among digital banking platforms intensifies, strategic partnerships like this one are becoming an increasingly common way to deepen customer relationships and increase engagement.
Fintech Fundraising Has Changed. What Should Founders Focus On?

Fintech Fundraising Has Changed. What Should Founders Focus On?

Many of us fondly remember when, just a handful of years ago, VC funding was abundant. It was a golden era in which startups competed for investor attention, valuations climbed quickly, and founders optimized for growth.

Fast forward five years, and the situation is much different. Venture funding has become much more selective, and while it often favors cutting-edge technologies such as AI and the blockchain, investors have much higher expectations than they did at the dawn of the decade, wanting to see proven traction much earlier. Between the changing economics and new technologies, it is clear that the fundraising environment for fintechs has evolved.

AI is reshaping where venture dollars go

By now, it’s no secret that AI-focused fintechs and ideas are garnering a lot of VC funding. According to CB Insights’ State of Venture 2025 report, AI startups raised $226 billion in 2025, a figure that represented 48% of all global venture funding. This doesn’t mean investors have lost interest in fintech. Instead, fintech companies are increasingly expected to demonstrate how AI strengthens their product, operations, or competitive moat.

All of this is happening while deal counts continue to decline and total venture funding has increased, suggesting that more money is flowing to fewer companies. In other words, fintech fundraising has become increasingly challenging. Generalist investors who previously backed broad fintech opportunities may now devote more attention to AI infrastructure and applications. Therefore, fintech founders need to explain not only why their business matters, but also how AI strengthens their competitive advantage.

Investors are rewarding efficiency more than growth

In 2021, many investors were myopically focused on growth. Today, it is clear that the “growth at all costs” mentality has ended as investors have shifted their focus to long term sustainability. Higher interest rates, a more disciplined venture market, and several years of valuation resets have encouraged investors to prioritize sustainable businesses over rapid expansion. Five years ago, investors used to focus on how fast a company can grow and today they are asking if companies can survive, scale responsibly, and solve a meaningful problem.

What is clear is that investors are looking for sustainable unit economics, realistic customer acquisition costs, recurring revenue, capital efficiency, and credible pathways to profitability. The question has shifted from “How quickly can this company grow?” to “Can this company build an enduring business?” In the fundraising environment of 2026, disciplined execution and financial resilience have become just as compelling as ballooning growth projections.

Relationships matter more than ever

In a world where funding is more competitive than ever, what’s the best move for a founder? Just as with enterprise sales, relationships, fit, and timing matter when it comes to fundraising. At a time when fewer companies are receiving funding, warm introductions and a precise founder-investor fit become the two elements that can make the difference between getting a meeting and getting funded.

Given this, the strongest approach for founders is to spend time building relationships before formally raising capital. Instead of pitching everyone, founders’ strategy looks like building credibility with the right investors.

What’s a founder to do?

None of these changes mean fundraising has become impossible. But they do mean that founders need a different playbook than they did just a few years ago.

That’s one reason Finovate launched the new IMPACT Funders & Founders event. As fundraising becomes more relationship-driven and investors become more selective, founders benefit from opportunities to meet qualified investors, hear directly from active VCs, and build connections before they need them most.

The good news is that capital will continue flowing to companies solving meaningful problems. The founders who understand and adapt to today’s investment landscape will be best positioned to secure it.

Finovate’s IMPACT Funders & Founders event takes place on September 11, 2026 in New York. Reserve your spot today and check out our blog coverage for more detail on what to expect.

For more founder-focused insights on the current market, check out a panel conversation from FinovateSpring where investors discussed where investment will continue, shared their thoughts on M&A expectations, and analyzed whether or not the bubble has already burst in fintech.


Photo by Edge Training

Fintech Rundown: A Rapid Review of Weekly News

Fintech Rundown: A Rapid Review of Weekly News

Congratulations to Spain for winning on the global stage of the World Cup yesterday! The country won against Argentina a final match with a score of one to zero after a nearly six-week long event. Today we turn to examine who is winning in fintech. Here’s a look at the top news headlines for this week. We’ll continue to add more announcements as the week progresses.


AI in banking

FIS partners with Anthropic to use Mythos 5 through Project Glasswing to bolster its security.

Databricks announces strategic funding at a $188 billion valuation.

Identity and verification

Know Your Customer (KYC) orchestration platform Fourthline announces plans to merge with identity verification platform Veridas.

Payments

Payfinia and Member Access Processing (MAP) team up to deliver embedded payments for credit unions.

Airwallex enables Wero payments for merchants throughout Europe.

Domopay selects Salt Edge to provide open banking capabilities for rent collection.

European paytech Teya upgrades its offering with billpay and cashback cards.

Buckzy Payments and FinXP forge strategic partnership to enable cross-border payments for merchants in Europe.

DeFi

Crypto.com announces $400 million strategic investment from Citadel Securities.

Digital asset platform MoonPay acquires Glide for its deposit and payments technology.

Stablecoin infrastructure firm Cyclops secures $20 million in Series A funding in a round led by Nava Ventures.

Wealth management

Investment platform Stratiphy opens its public funding round.

Lending

Financial marketplace ClearScore partners with open-banking-powered lender Abound for its automated debt consolidated technology, Clearer.

Digital banking

Banking platform Lumin Digital raises more than $70 million in new capital from its own clients.

Business financial management

Spend management software company Expensify unveils ints new corporate Expensify Card for users in the UK and select countries in the EU.


Photo by Sam Williams on Unsplash

Stable Launches StablePay to Bring Stablecoin Payments to the Mainstream

Stable Launches StablePay to Bring Stablecoin Payments to the Mainstream
  • Stable has launched StablePay, enabling users to send and receive USDT globally in seconds with no transaction fees.
  • The app hides blockchain complexity by allowing payments through phone numbers, email addresses, or QR codes while supporting fiat and stablecoin transfers.
  • StablePay also offers yield on idle USDT and plans to expand its on- and off-ramp capabilities, payment integrations, and referral features.

Stablecoin blockchain Stable launched StablePay to allow global users to send and receive USDT instantly and for free. The tool is built on StableChain, Stable’s settlement infrastructure, to remove technical complexities of operating in crypto.

StablePay is marketed both as a direct-to-consumers product and to and payment providers. The company aims to bring the benefits of stablecoin infrastructure within a TradFi-like experience that allows users to transition between stablecoins and fiat without the difficulties of managing wallets, gas fees, or blockchain accounts. While StablePay brings the simplicity of TradFi payments, it does not have the multiple intermediaries that TradFi has or take days to settle. StablePay settles borderless USDT payments in seconds with no fees or delays.

“Money should move as fast as the internet does,” said Stable CEO Brian Mehler. “The world’s largest financial institutions are already shifting to stablecoin-native settlement; that is the direction where payments infrastructure is heading. StablePay puts the benefits of stablecoins into a product anyone can use, no crypto knowledge required: speed, global reach, and near-zero cost.”

Founded in 2025, Stable is a Layer 1 blockchain that uses USDT as its native gas token, eliminating the need for users to hold a separate, potentially volatile cryptocurrency to pay transaction fees. The company is already powering live payment flows across multiple regions, with early use cases spanning peer-to-peer transfers, cross-border remittances, and international payroll.

Like other consumer payment apps, StablePay lets users send money using a phone number, email address, or QR code, hiding the complexity of blockchain addresses from end users. Beyond payments, the app also includes an Earn feature that enables users to generate yield on idle USDT, similar to how consumers earn interest on cash held in a high-yield savings account.

Looking ahead, Stable plans to add broader on- and off-ramp support, new payment integrations, and referral-driven growth features in the coming months.


Photo by Pixabay

Where Are They Now? Updates from Six FinovateFall 2025 Best of Show Winners

Where Are They Now? Updates from Six FinovateFall 2025 Best of Show Winners

Last year’s FinovateFall conference brought together attendees, fintechs, and bank representatives from across the world.

On the second day of the event, 63 companies took the stage to showcase their newest solutions. Of that group, six fintechs brought home Best of Show honors for the work they showcased on stage.

With FinovateFall coming up September 9 through 11, we wanted to look at how last year’s Best of Show winners have grown and influenced their markets. Here’s a look at what Casap, Eko, Krida, LemonadeLXP, LendAPI, and Vertice AI have been up to since taking home Best of Show.


Casap

What won Best of Show: Casap impressed the audience with its AI-powered platform that helps financial institutions automate disputes, reduce fraud losses, accelerate resolution times, and strengthen customer relationships.

Where they are now: Since winning Best of Show, Casap has continued expanding its dispute automation platform, reporting customer results including 97% chargeback win rates, 51% fewer fraud losses, and 40% lower call volumes. Earlier this year, the company also participated in Filene’s FiLab program, where credit unions evaluated how Casap’s AI can reduce manual workloads and improve member experiences during fraud disputes.


Eko

What won Best of Show: Eko demonstrated how embedded investing can help financial institutions increase digital banking engagement, grow deposits, and improve customer retention.

Where they are now: Since FinovateFall, Eko has continued expanding its embedded investing platform with additional financial institution deployments, including Brooklyn Cooperative Federal Credit Union. The company remains focused on helping banks and credit unions integrate investing directly into digital banking rather than sending customers to third-party brokerage platforms.


Krida

What won Best of Show: Krida showcased technology that shortens lending cycle times, reduces manual work, and minimizes borrower drop-off, helping banks originate loans faster while improving customer relationships.

Where they are now: While Krida has kept a relatively low public profile since its Best of Show win, the company continues developing its lending automation platform aimed at streamlining loan origination and underwriting for community financial institutions.


LemonadeLXP

What won Best of Show: LemonadeLXP earned Best of Show for InsightAI, its platform that helps financial institutions improve employee education, customer knowledge, and operational efficiency through AI-powered learning.

Where they are now: Over the past year, LemonadeLXP has continued investing heavily in AI-powered employee enablement while expanding its leadership team. In November, the company launched AI Conversations, an AI-powered voice conversation training tool that helps make employees more confident. LemonadeLXP was also selected to demo at FinovateFall 2026 in New York.


LendAPI

What won Best of Show: LendAPI demonstrated a collaborative platform that enables technology, risk, and compliance teams to build lending products together on a shared infrastructure.

Where they are now: LendAPI has continued expanding its embedded finance platform, positioning itself for the emerging era of agentic AI in lending. The company started the year by surpassing 100 million credit applications processed on its platform, and has since strengthened its leadership team with new appointments, launched instant commercial DDA onboarding for credit unions, and joined an accelerator program.


Vertice AI

What won Best of Show: Vertice AI showcased its AI-powered customer growth platform, which translates customer data into personalized product recommendations and marketing campaigns for community financial institutions.

Where they are now: Since winning Best of Show, Vertice AI has grown its customer base to more than 80 clients, formed a strategic partnership with Ceto, teamed up with Member Driven Technologies (MDT), and launched a new CUSO called CUltivate. Additionally, the company’s Vertice COMPOSE solution was selected for Filene’s FiLabs 2026 Testing for its acceleration of compliant, personalized CU marketing at scale. Best of all, Vertice AI was selected to demo at FinovateFall in New York this September.


If you’d like to see the next generation of fintech innovators before everyone else does, join us in New York September 9 through 11 for FinovateFall 2026. There’s still time to get exclusive hotel discounts if you book your room before August 17.


Photo by Ivana Rodriguez

Spreedly Unbundles Its Payment Vault

Spreedly Unbundles Its Payment Vault
  • Spreedly is launching a standalone payment vault, enabling merchants to securely store and manage payment credentials without adopting the company’s full payments orchestration platform.
  • The portable vault supports more than 100 payment providers, giving merchants greater flexibility to switch processors, build their own routing logic, and expand payment capabilities without migrating stored credentials.
  • By unbundling its vault, Spreedly is challenging the traditional processor lock-in model and increasing pressure on payment providers to offer more open, interoperable payments infrastructure.

Payments orchestration platform Spreedly launched a standalone payment vault that gives merchants the ability to securely store and control their own payment credentials without using Spreedly’s payments orchestration platform.

Unbundling the payment vault means a merchant can now use Spreedly’s vault separately from its other products to securely store payment credentials; continue using its existing payment processor, even if it is with Stripe, Adyen, or Worldpay; keep their existing payment routing logic; and have the option to decide whether to adopt Spreedly’s orchestration platform or build its own.

“The vault has become the control point in modern payments,” said Spreedly CEO Justin Benson. “More of what determines payment performance now lives in the credential itself, and providers are finally opening up to let merchants own it. Merchants want that control—the ability to run the providers they have today and change course tomorrow. An independent vault lets them start now and decide the rest as they grow. They shouldn’t have to commit to everything on day one.”

The standalone vault offers merchants a direct path to additional payment capabilities on the Spreedly platform without migrating payment credentials, PCI DSS Level 1 tokenization that keeps raw payment data out of merchant systems, and portable payment credentials that work across more than 100 payment providers with no processor lock-in. Additionally, Spreedly’s built-in network tokenization and account updater services help keep payment credentials current and improve authorization rates.

Spreedly’s stored credential transactions now account for 40% of its transaction volume. That figure, which is up from 34% in 2022, reflects merchants’ increasing demand for payment strategies built around portable credentials rather than a single payment processor.

Spreedly said that it is unbundling the payment vault because the value of where the payment sits has changed in five major ways:

  1. The vault is no longer passive storage because the payment credential and who controls it have become a competitive advantage as network tokenization, account updater services, and stored-credential optimization increasingly determine authorization rates and payment performance.
  2. Payment providers that used to control credentials are increasingly supporting merchant-controlled vaults and credential portability. This removes a long-standing barrier to adding or switching providers.
  3. A growing number of merchants want to own the routing and decisioning layer that sits outside of their providers.
  4. As AI agents begin initiating purchases, merchants in control of portable payment credentials will be best positioned to support them.
  5. Keeping their payment vault independent helps merchants preserve optionality without being locked into a commitment.

“A vault shouldn’t lock you into anyone’s roadmap, including ours,” said Spreedly CTO Mike Rivers. “When credentials stay portable, a merchant can run a single provider per region today and add routing, orchestration, or new payment methods whenever they’re ready. Portability is what keeps the future open.”

The launch will likely intensify competition across the payments ecosystem. Traditionally, processors and gateways have strengthened customer retention by controlling merchants’ stored payment credentials, making it costly to switch providers. By offering a standalone, portable vault, Spreedly is challenging that model and encouraging merchants to treat payment credentials as infrastructure they own rather than an asset managed by a single payments provider. If the strategy gains traction, it could put pressure on processors, gateways, and orchestration platforms alike to make their own ecosystems more open and interoperable.

Spreedly was founded in 2007 to help merchants build their payments stack on a single platform. The North Carolina-based company’s payment orchestration stack processes over $50 billion in annual transaction volume on behalf of more than 400 customers across 100+ countries. Spreedly also offers fraud prevention, payment optimization tools, and more. Among the company’s clients are BMW, CLEAR, HBO Max, Hopper, Lemonade, Getty, Warner, The New York Times, and others.


Photo by Polina Tankilevitch

Flex Raises $70 Million to Improve Payments for High Net Worth Business Owners

Flex Raises $70 Million to Improve Payments for High Net Worth Business Owners
  • Business banking platform Flex raised $70 million in a Series B1 round to expand its business finance, payments, private credit, and ERP offerings while doubling its workforce.
  • The company also launched Flex Global, a cross-border banking service that combines multi-currency accounts, global payments, and stablecoin infrastructure to enable faster international money movement.
  • With Flex Global, Flex is positioning itself to compete more directly with Brex and Ramp by offering globally active businesses a unified platform that blends banking, payments, credit, and wealth management.

The business banking space is heating up again. Business banking platform Flex landed $70 million in a Series B1 investment, boosting its total equity funding to $180 million and total debt funding to $300 million.

Halo Fund lead the investment, which comes seven months after Flex’s $60 million Series B round. Portage Ventures, Wellington, Crosslink Capital, 53 Stations, Titanium Ventures, Spice, Florida Funders, Spice, and others also contributed. Halo’s participation is especially notable, as its co-founders span the sports and entertainment space, bringing expertise in sports and entertainment distribution into audiences that include millions of successful middle-market business owners and entrepreneurs.

With this round, Flex plans to expand across business finance, personal finance, payments, private credit, and ERP. The company will also use the funds to double the team size from 110 employees to more than 200 by year-end.

Flex made its debut in 2022 to bring private banking to high net worth business owners. The California-based company offers banking, private credit, payments, billing, and accounting tools for businesses, as well as a business credit card that pays up to 5% cashback. The company’s average customer uses four or more of these products on its platform. Flex has crossed $10 billion in annualized total payment volume and is currently growing 4x year-over-year.

“I’ve spent my career helping entrepreneurs win, and they all have the same problem: their business and personal financial lives are completely intertwined, but every bank treats them as two different customers, missing what they’re actually trying to build,” said Halo Fund Owner Co-founder Ryan Smith. “Flex is the first team creating a real private bank around the owner and the entire household’s finances, and the gap they’re filling is just as real globally as it is in the US. Zaid and the team have built an enduring business that is becoming an institution for the world’s most ambitious owners.”

Along with today’s funding announcement, Flex is launching Flex Global, a service that brings together local currency accounts, cross-border payments, and stablecoins for always-on, fast funds transfers. The service is aimed to serve cross-border businesses by issuing global credit cards, leveraging stablecoin payment rails and wallets in 100+ countries, and offering institutional USD accounts for foreign business owners. Flex’s multi-currency accounts support 32 currencies across 76 countries, enabling busineses to hold, send, and receive funds in the currencies they actually operate in.

Flex’s goal is to make the underlying payment rails invisible to customers by embedding stablecoin settlement into its private banking experience. Rather than requiring businesses to manage crypto wallets or navigate blockchain technology, Flex uses stablecoins behind the scenes to make international payments feel as seamless as domestic ones.

“Middle-market business owners are one of the most important and underserved customers in finance globally,” said Flex CEO and Founder Zaid Rahman. “Depending on the type of owner, they’ll tell you their vendors are spread across the US, Poland, Brazil, etc; their accounts hold currency outside of just USD; and they have to oscillate across 2-3 vendors and layers of fees just to do business outside their country.”

Flex Global raises the competitive stakes for Brex and Ramp by expanding Flex beyond domestic banking, credit, and expense management into global financial infrastructure. Both rivals already support international cards and vendor payments, while Brex has also been developing stablecoin-based global transfers. Flex differentiates itself with its focus on middle-market business owners and its effort to combine cross-border payments, multi-currency accounts, credit, banking, and personal wealth management within a single private-banking relationship. That approach could help Flex compete less as another spend-management platform and more as the primary financial institution for globally active entrepreneurs.


CSI Acquires Qolo for Undisclosed Amount

CSI Acquires Qolo for Undisclosed Amount

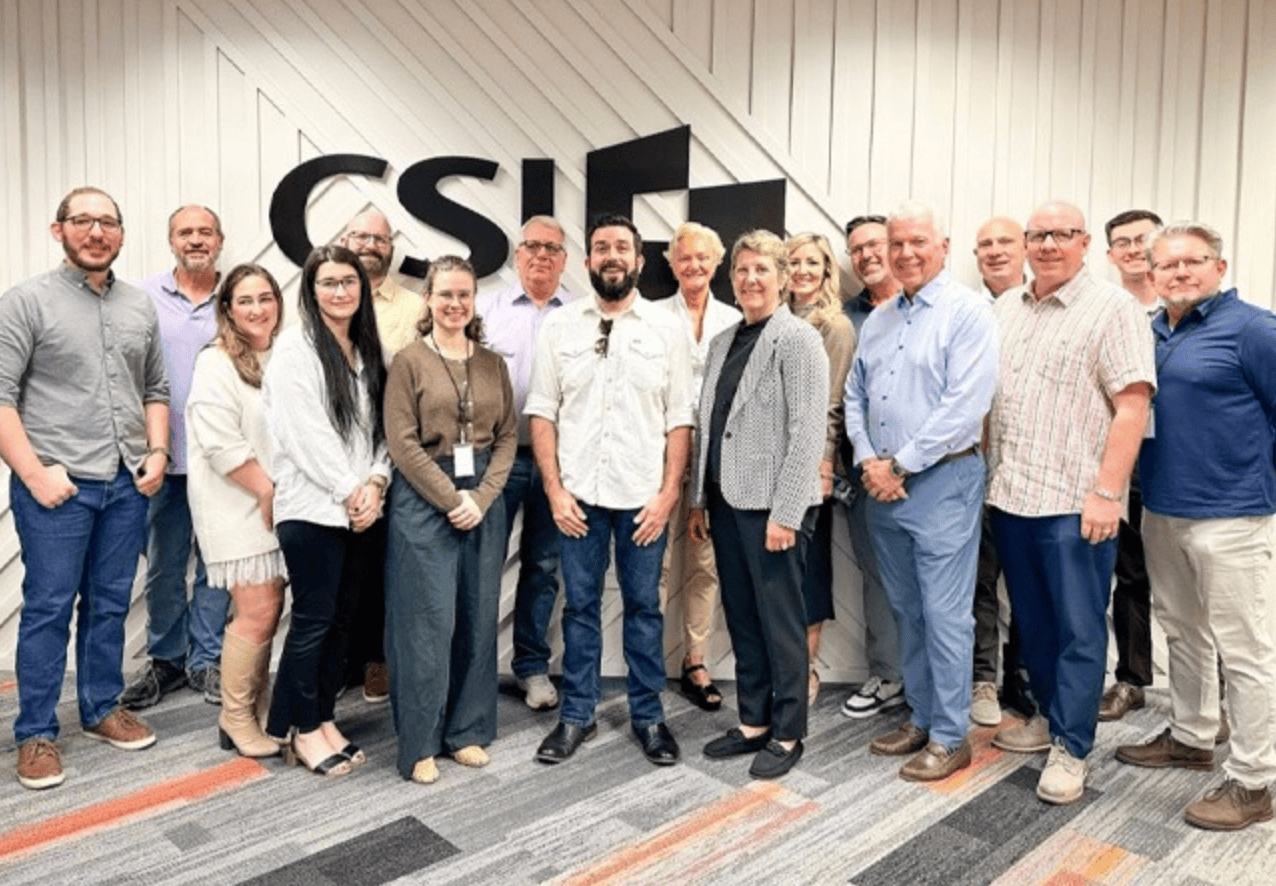
Fintech solutions provider CSI has acquired payments infrastructure and treasury solutions provider Qolo for an undisclosed amount.

CSI anticipates that the acquisition will strengthen its commercial banking solutions by offering its community financial institution clients more flexible deposit structures and expanded commercial card programs. Adding Qolo’s existing clients to its own roster will also extend CSI’s geographical reach.

More specifically, CSI will use Qolo’s technology to serve as the orchestration layer across payments, accounts, and workflows. The Kentucky-based company will integrate with CSI’s core banking platform, digital banking solution, and broader API capabilities to bring community financial institutions prepackaged, pre-integrated commercial banking solutions, including:

  • A real-time account ledger that gives banks and businesses instant visibility into balances, transactions, and authorizations.
  • Multi-rail payment orchestration that offers a unified payment engine to orchestrate domestic and international money movement across multiple payment rails and business workflows.
  • Enhanced card capabilities that expand integrated issuing and processing across debit, prepaid, virtual, and secured corporate credit card programs.

Qolo, which demoed at FinovateFall 2022, was founded in 2018 with the aim of simplifying payments through a unified infrastructure layer. Its platform combines an embedded ledger, card issuing, money movement, real-time reconciliation, and cross-rail connectivity into a single API. Rather than requiring banks to replace legacy cores, Qolo overlays its technology on top of existing systems, enabling institutions to deploy new payment capabilities in months, not years.

CSI said that the combined company will remain focused on serving community financial institutions with new ways to attract, retain, and grow customer relationships by offering modern commercial banking capabilities typically found at large banks. Keeping up with current, constantly changing technology can help small community banks compete more effectively with banks that have large R&D budgets.

“Community financial institutions are built on trusted relationships, local expertise, and deep knowledge of their markets,” said CSI President and CEO Nancy Langer. “But businesses in their communities also need sophisticated banking capabilities that simplify and fit more naturally into their day-to-day financial operations. With Qolo, CSI is helping community banks bring those capabilities to market in ways that help them grow commercial relationships and become more central to how businesses operate. At the same time, it expands our ability to support fintechs and B2B payments providers as demand grows for financial services embedded directly into everyday business workflows.”

For community banks, the acquisition is less about adding another payments tool and more about simplifying how commercial banking services are delivered. As businesses increasingly expect real-time payments and integrated treasury capabilities, banks are looking for unified platforms that reduce technology complexity while enabling them to embed financial services more naturally into their customers’ day-to-day operations.

“The line between traditional banking and embedded finance is becoming increasingly blurred,” said Qolo Co-founder and CEO Patricia Montesi. “Whether you’re a community bank modernizing your commercial offering or a fintech building embedded finance products, you’re often running into the same challenges: fragmented vendors, disconnected payment rails, and manual workarounds that limit growth. By joining CSI, we can invest more deeply in the infrastructure that powers modern financial experiences and help our customers become a more seamless part of how businesses manage and move money every day.”

In an interview at FinovateFall last year, I sat down with Montesi to discuss how the company helps modernize payments infrastructure. “We set out to build an entire, comprehensive payments stack that includes ledger, card, payments, virtual account management—everything all available through a single API served up to you so that you can then focus on your customers,” said Montesi.

Rather than replacing legacy cores outright, banks are increasingly layering modern payments, ledger, and treasury capabilities on top of existing infrastructure. Qolo built its platform around that philosophy, making it a natural fit for CSI’s strategy of helping community financial institutions modernize without undertaking large-scale core replacements.

Entrust Launches Agentic AI Trust Accelerator

Entrust Launches Agentic AI Trust Accelerator
  • Entrust launched its Agentic AI Trust Accelerator to help enterprises build the identity, authorization, and governance infrastructure needed to deploy autonomous AI agents in production.
  • The program focuses on identity, authorization, cryptographic assurance, and accountability to ensure AI agents can be authenticated, governed, and audited.
  • As banks increasingly explore agentic AI for sensitive tasks and transactions, trust infrastructure is becoming a critical requirement for enterprise adoption.

Identity solutions company Entrust unveiled its Agentic AI Trust Accelerator, a program that will help firms build the identity and trust infrastructure needed to move autonomous AI projects from pilot to production.

Entrust’s new tool helps bridge the gap between the utility of AI agents and the lack of formal governance around them. AI agents notoriously lack the necessary infrastructure to ensure AI agents are who they say they are, to verify that the person behind the agent is who they say they are, and to authenticate the relationship between the person and the bot. Additionally, organizations need to know who authorized the agent, what it is allowed to do, and how its actions can be proven after the fact.

“AI agents are advancing faster than the trust infrastructure needed to govern them,” said Entrust COO Anudeep Parhar. “Enterprises need to be able to trust autonomous actions across business processes, partners, and systems. Whether organizations are experimenting with AI agents, deploying initial use cases, or preparing for broader adoption, they need a trust foundation that can scale with them. The Agentic AI Trust Accelerator brings together customers and partners to develop practical approaches for identity, authorization, cryptographic trust, and accountability that work with their existing platforms. We call this the trust plane for autonomous AI.”

Founded in 1994 as Entrust Datacard, the Texas-based company offers fraud solutions built around identity to help its customers in over 150 countries proactively verify customer identity, secure connections, and fight fraud and stay compliant by using ongoing monitoring. The new Accelerator program leverages Entrust’s identity and cryptographic security capabilities to help enterprises confidently use AI agents to enhance their operations. The tools help organizations verify identity and proof of action across systems, partners, and workflows.

The Agentic AI Trust Accelerator program centers on four core pillars: identity, authorization, cryptographic assurance, and accountability. The identity component verifies both human users and AI agents while ensuring every agent action can be traced back to a responsible individual. Authorization limits agents to approved roles, policies, and permissions, with human oversight built in when needed. Cryptographic assurance secures agent operations through capabilities such as digital signing, while accountability provides verifiable records of agent actions to support compliance, audits, and regulatory requirements.

Entrust’s Accelerator program addresses a growing need for agent authentication. As organizations move beyond AI assistants to autonomous agents capable of initiating transactions, accessing sensitive data, and making decisions with limited human intervention, identity and authorization are becoming necessary infrastructure. For banks in particular, the ability to verify who is taking an action and to produce an auditable record of that activity will likely become a prerequisite for deploying agentic AI at scale.

“Agentic AI will reshape how enterprises operate, but trust will determine how quickly organizations can move from experimentation to production,” said Entrust CEO Tony Ball. “Entrust is helping customers build the identity, authorization, and cryptographic foundations required for autonomous systems operating in real-world environments.”

At launch, Entrust is opening the Accelerator program to a limited number of customers, banks, and partners.


Photo by Joshua Hoehne on Unsplash

Citi Sees First Bank Goes Live with its Clearing and Token Services Solution

Citi Sees First Bank Goes Live with its Clearing and Token Services Solution
  • Siam Commercial Bank is the first financial institution to go live with Citi’s integrated 24/7 USD Clearing and Citi Token Services offering.
  • The solution uses tokenized deposits on a private permissioned blockchain to support near real-time cross-border USD payments around the clock.
  • The launch shows how banks are combining distributed ledger technology with traditional banking infrastructure to reduce payment delays without relying on public blockchains or stablecoins.

Citi announced that Siam Commercial Bank (SCB) has become the first financial institution to go live with Citi’s 24/7 USD Clearing and Citi Token Services. The integration enables near real-time, 24/7 cross-border US dollar payments for SCB’s corporate and institutional clients.

Adopting Citi’s 24/7 USD Clearing with Citi Token Services will help SCB reduce the friction that has historically limited clients’ global payment operations. Traditionally, cross-border USD payments have been constrained by banking hours, weekends, and holidays, creating delays for companies operating across time zones. Offering near real-time settlement around the clock will give corporate clients greater flexibility in managing liquidity, cash flow, and making time-sensitive international payments.

Citi Token Services leverages a private permissioned blockchain that operates within the traditional, regulated banking system. The new service allows the bank to tokenize deposits held within Citi’s global network. When integrated with Citi’s 24/7 USD Clearing solution, which connects over 300 financial institutions across more than 50 geographies, the service creates an always-on payment rail that bridges Citi and non-Citi accounts across borders.

“At SCB, we continuously invest in innovative capabilities that help our corporate and institutional clients operate more efficiently in an increasingly global and connected business environment,” said Siam Commercial Bank Head of Transaction Banking Thanawatn Kittisuwan. “Through our collaboration with Citi, we are the first bank in Thailand to leverage tokenization to enhance cross-border USD capabilities, helping our clients simplify operational constraints and conduct their international business activities with greater flexibility.”

Demonstrating the utility of the always-on nature of the new system, SCB client Phillip Securities Thailand used Citi’s enhanced 24/7 USD Clearing capabilities and Citi Token Services to transfer US dollars from a Citi London account of a subsidiary to the beneficiary account with SCB in Thailand over the 4th of July weekend, a federal holiday in the US. The transfer marked SCB’s first transaction with the new solution.

For Citi, this partnership is an example of the firm’s effort to modernize cross-border payments by combining tokenization with its existing, traditional banking network instead of using public blockchain infrastructure or stablecoins. Citi is one of many financial institutions that are seeking to use distributed ledger technology to improve the speed and availability of traditional banking services while staying within existing regulatory frameworks.

“Our enhanced 24/7 USD Clearing solution integrated with Citi Token Services is an industry-first that bridges traditional and digital rails to expand our suite of always-on client solutions,” said Citi Asia South Head of Services Mridula Iyer. “It furthers our ‘network of networks’ approach as we build capabilities that are interoperable so that they are multi-bank, multi-market and multi-network. This gives our clients the optionality they need, now and for the future, as the global financial infrastructure continues to rapidly evolve.”


Photo by Tom Fisk

Nu Receives Full Banking License in Mexico

Nu Receives Full Banking License in Mexico
  • Nu Mexico received authorization from the CNBV to begin operating as a bank, moving from its previous SOFIPO status into Mexico’s formal banking sector.
  • The approval makes Nu Mexico the country’s largest digital bank, with more than 15 million customers and a presence in 98% of Mexico’s municipalities.
  • The bank license gives Nu a stronger platform for growth, allowing it to expand its product suite, deepen deposit relationships, and compete more directly with incumbent banks.

Nu, the parent company of Brazil-based Nubank, is making Nu Mexico more official this week. The bank has received authorization from the National Banking and Securities Commission (CNBV) to begin operations as a bank.

The new authorization will make Nu Mexico the largest digital bank in the country, counting more than 15 million customers, a figure that represents more than 15% of the nation’s population.

“We are building a new way of delivering financial services in Mexico, one truly centered on people,” said Nubank Founder and Global CEO David Vélez. “The authorization we receive and the growth we have achieved confirm that this model works and has the potential to transform the relationship millions of people have with their money. Mexico is a key market for Nubank, and this is a decisive step in our long-term commitment to the country, with a total projected investment of $4.2 billion through 2030.”

Until now, Nu has operated in Mexico as a Sociedad Financiera Popular (SOFIPO), a licensed non-bank financial institution in Mexico that can offer services such as savings accounts, loans, payments, and other financial products, often aimed at consumers and underserved populations. “Receiving authorization after an unprecedented process of transforming from a SOFIPO into a bank is a milestone we have not reached alone,” said Nu Mexico CEO Armando Herrera. “We got here alongside millions of Mexicans who have placed their trust in Nu to transform the way they relate to their money. We are ready to keep building with them the financial experience they deserve.”

The authorization moves Nu Mexico from the non-bank fintech category into the country’s formal banking sector. That will allow Nu to broaden its product suite, attract and retain deposits, and compete more directly with Mexico’s incumbent banks. It also validates the company’s strategy of using a digital-first model to reach customers that traditional institutions have underserved.

Nu has operated in Mexico since 2019, adding an average of 12,000 new customers per day over the past seven years. Nu Mexico launched its first product, a no-fee credit card with customizable financing plans, in 2020 and has since added a savings account and new features such as Cajita Turbo and Scam Alert to protect its customers from fraud attempts. The fintech also offers personal loans and secured cards to help customers access credit and build a credit history. Today, Nu Mexico has a presence in 98% of the country’s municipalities, has given 54% of its customers their first credit card, and has helped 60% of its users start a savings habit.

Nu Mexico has 30 days to complete its transformation into a bank. The bank aims to keep the customer experience unchanged during the transition and maintain communication with its users.


Photo by Julio Lopez

Swift Goes Live with New Blockchain-Based Ledger

Swift Goes Live with New Blockchain-Based Ledger
  • Swift launched a blockchain-based ledger that lets banks move tokenized deposits across borders 24/7 before completing final settlement through existing banking systems.
  • The ledger is designed to make blockchain interoperable with bank infrastructure, giving financial institutions a shared layer for digital money without requiring them to abandon current rails or compliance processes.
  • Seventeen global banks will participate in the initial pilot, moving Swift’s blockchain work from prototype to live testing with major transaction banks across six continents.

Swift has officially launched its new blockchain-based ledger that will support 24/7 cross-border payments with tokenized deposits, enabling funds to move in any regulated form, anywhere, with a high level of security.

The shared, blockchain-based ledger offers banks an orchestration layer for bank-issued tokenized deposits on their own ledgers. The blockchain ledger enables banks to move funds for customers 24 hours a day, seven days a week, before completing final settlement through the banks’ existing systems. In addition to always-on settlement, banks can offer clients global liquidity while maintaining compliance, credit, risk, and control standards.

“With our new ledger capability, we’re extending the trust and stability of established finance into the frontiers of digital money,” said Swift Chief Business Officer Thierry Chilosi. “It allows tokenized value to move across borders with the velocity and flexibility modern commerce expects, while maintaining the same high levels of resiliency, security, and compliance global finance requires. The strong support from banks shows the practical value of this approach—one that will help scale benefits globally while creating a foundation for future innovation in areas like programmable money and agentic commerce.”

Unlike other new payments technology, Swift’s ledger brings blockchain-based payments into the infrastructure banks already use. While previous digital money efforts were fragmented across pilots, private networks, and bank-specific systems, Swift’s approach gives banks a shared layer for moving tokenized value across borders while preserving the compliance, resiliency, and settlement processes that each region requires. Rather than asking banks to abandon existing rails, Swift is positioning the blockchain as an interoperable layer that can work alongside them.

Today’s announcement comes ten months after Swift teased the launch of its ledger, testing a prototype blockchain with more than 30 financial institutions across the globe. This is the first use case for Swift’s ledger, which the cooperative anticipates will set a new precedent for interoperability on payments infrastructure. Swift has made it clear that it will offer fee transparency and a faster, more consistent customer experience. Today’s upgrades to the ledger move Swift’s blockchain ambitions out of the experimentation phase and into a live pilot with some of the world’s largest transaction banks.

Swift reports that the speed of payments on the new blockchain-based network exceeds current standards. “A full 75 percent of payments on the network reach beneficiary banks within 10 minutes, and often in seconds, and the cooperative is going even further to advance the industry to meet the G20 targets for international transactions,” the company states. The member-owned cooperative plans to expand the network functionality and availability after an initial pilot phase that will include 17 banks from six continents. Among the pilot banks are ANZ, BNP Paribas, BNY, Citi, DBS, First Abu Dhabi Bank (FAB), FirstRand Bank Limited, HSBC, Itaú Unibanco, Lloyds Bank, Mashreq, MUFG Bank, OCBC, Standard Chartered, UBS, UOB, and Wells Fargo.

“We see interoperability as the key enabler for scaling tokenized deposits beyond individual institutions,” said UBS Managing Director, Group Head of Digital Assets Mr. Andreas Kubli. “Swift’s ledger is an important industry initiative that can help connect digital money networks, supporting real-time settlement, greater liquidity mobility and the broader adoption of tokenized payments and digital assets across the global financial ecosystem.”


Photo by Sonny Sixteen