3 Takeaways from Bilt’s Breakup and Troubled Transition from Wells Fargo

3 Takeaways from Bilt’s Breakup and Troubled Transition from Wells Fargo

The recent crisis involving Bilt, a fintech that specializes in rent-payment rewards, is almost a perfect storm of the challenges faced by fintechs, banks, regulators, and their customers when it comes to third-party partnerships and their discontents.

This week, the Consumer Financial Protection Bureau (CFPB) reported that it had met with Bilt to discuss the issues surrounding the flawed transition process when its partnership with Wells Fargo ended in February of this year. The two companies had been working together since 2022 to offer the Bilt Mastercard. When the partnership ended, Bilt struggled to efficiently move customers into its new Bilt 2.0 structure. Customer complaints were rampant: rent and mortgage payments were returned, delayed, or debited without reaching intended recipients. Card declines were reported amid general confusion about the new arrangement. Massachusetts Senator Elizabeth Warren, who took an early interest in the problem, said that there had been a 1,300% spike in CFPB complaints due to the problems of the Bilt transition.

The CFPB’s statement today expresses confidence in the steps Bilt is taking to remedy the situation, including “reimbursing fees for more than 500 newly identified customers from its outreach following discussions with the CFPB.” The agency also noted that it would “continue monitoring Bilt’s efforts until it is satisfied that full redress will be provided and will share another update at such time.”

What are some of the biggest takeaways from Bilt’s breakup with Wells Fargo and its complaint-ridden transition process?


Partnerships are hard, breaking up can be harder

For all the understandable concern about making fintech/bank partnerships work, there is relatively little discussion about what fintechs should do—or need to do—when a partnership is ending to ensure that the transition does not negatively impact customers or damage relationships with other partners.

Arguably, this is the biggest single takeaway from the Bilt breakup and transition: whether it is because of a regulatory decision, a business challenge, or a bank failure, when transitions out of these partnerships go poorly, the negative impacts tend to fall disproportionately on consumers. There is also some question about who bears the responsibility of protecting customer data and funds during transitions. As such, when these events occur, they can have an industry-wide impact on consumer trust toward fintechs and can blunt innovation by making new technologies and services seem risky to end users and potential partners.


The human touch helps in a crisis

Even though there were reportedly issues with customers accessing live customer support due to “high volumes,” the fact that many Bilt customers were steered toward AI chatbots to resolve issues was a operational and, potentially reputational, mistake.

On the operational level, many customers reported that AI chatbots were unable to answer their questions or provide basic information, let alone resolve specific complaints. Reputationally, this can leave an impression that a firm does not care about effectively triaging customer problems, even if it is understandably not able to solve some problems immediately.

This is also a reminder that human agents that can respond with authentic empathy to confused and frustrated customers are still valuable at a time of increasingly agentic customer care.


Regulatory clarity requires regulatory authority

The lack of regulatory clarity about the ultimate responsibility for safeguarding consumer data and capital during transitions like the one involving Bilt and Wells Fargo is a real problem.

But this lack of clarity is compounded when the disposition of the regulatory body itself is difficult to discern. In its statement, the CFPB underscored its preference for a “collaborative process” rather than what is called a “protracted investigation, followed by a public enforcement action, which could be litigated for years before consumers get any redress.” This, plus a swipe at the Biden-era CFPB director Rohit Chopra, suggests that the CFPB prefers to pursue a less confrontational approach when it comes to holding companies accountable when their actions harm consumers.

This is perhaps better than no approach at all. Recall that the Trump Administration in February 2025 launched a near-shutdown of the CFPB, stopping all enforcement actions, halting new and ongoing investigations, and even locking staff out of buildings. Many of the administration’s actions have been put on hold by a federal court judge ruling in 2025, and oral arguments on a lawsuit challenging the administration’s actions against the CFPB were heard this February. In the meantime, a slimmed-down CFPB has changed its mission to focus on what it calls issues of “clear consumer harm, particularly fraud affecting servicemembers and veterans.”

How well this approach will serve the consumers harmed by the next failed fintech/bank partnership remains to be seen.


Photo by Javier Allegue Barros on Unsplash
6 Arguments For and Against Prediction Markets as Spain Cracks Down

6 Arguments For and Against Prediction Markets as Spain Cracks Down

Spain’s ministry of consumer rights blocked access to Kalshi and Polymarket this week. The country has paused the use of the prediction markets (also known as event contracts) as it determines whether their models are operating legally without a gambling license.

Spain joins France, Belgium, the Netherlands, and Romania, which have all limited or blocked access to Polymarket.

The controversy begs the question: are prediction markets useful forecasting tools, speculative tools, or simply gambling platforms wrapped in fintech language? With that in mind, here’s a look at three arguments for and three arguments against event contracts.

Three arguments for

Supporters argue that prediction markets are not necessarily about gambling, but rather about information discovery.

  • Prediction markets can aggregate information more efficiently than polls or experts
    Prediction markets force participants to put money behind their convictions, which essentially rewards accuracy with financial incentives. Supporters argue this makes them more effective than polls or expert commentary at forecasting future events because markets continuously absorb new information and update probabilities in real time.
  • Financial markets already operate as forms of event contracts
    If you’ve ever invested in single stocks, you’ve essentially participated in prediction markets. The only difference is that, with stocks, investors are limited to predicting the outcome of a company instead of an event. Bonds and derivatives are also a type of prediction as well, as bonds essentially price default risk and derivatives price probabilities. This raises the question, why is betting on election outcomes different from betting on interest-rate moves.
  • Prediction markets could improve forecasting
    Because they are a useful tool for crowdsourcing information, prediction markets can be used by businesses or governments to improve decision-making. Users are more likely to make predictions on events about which they are knowledgeable, and this information could be helpful for forecasting recessions, fraud, supply chains, elections, and demand. Because they can source this information quickly, prediction markets can surface truths faster than committees or social media.

Three arguments against

Opponents argue that event contracts cause unwanted externalities

  • They may incentivize harmful or unethical behavior
    Oftentimes, event contracts offer events surrounding wars, assassinations, elections, and disasters. These are uncomfortable things to bet on, as it may feel as if users are rooting for these outcomes. Additionally, this raises ethics concerns over investors profiting from others’ tragedies.
  • Markets can be manipulated
    Even though prediction market outcomes may appear more organic than the performance of publicly traded companies, they are not immune to manipulation. Deep-pocketed participants willing to absorb larger losses may attempt to distort market odds, while coordinated misinformation campaigns and bot-driven activity can artificially influence sentiment and pricing. As event contracts become more popular, concerns are growing that the markets themselves could shape public perception rather than simply reflect it.
  • They lack consumer protections and regulatory frameworks
    Across the globe, prediction markets are relatively new and therefore lack regulation, as they don’t fit cleanly into existing categories. It is unclear if they are considered securities, gambling, or derivatives and therefore lack proper regulatory oversight and consumer protection standards.

As prediction markets continue to grow in popularity, regulators will increasingly need to decide whether these platforms belong within financial services, gambling, or an entirely new category. Spain’s move suggests that many jurisdictions are still uncomfortable with the idea of turning elections, world events, and public sentiment into tradeable assets.


Photo by Dante Grime Kahan

5 Takeaways from Trump’s Executive Order on Fintech and Regulatory Frameworks

5 Takeaways from Trump’s Executive Order on Fintech and Regulatory Frameworks

In last week’s Finovate Weekly newsletter, I shared some thoughts on what fintechs might hope for from President Trump’s summit meeting with Chinese president Xi Jinping. While the meeting does not appear to have delivered anything of substance from a fintech or financial services perspective, Trump did sign an Executive Order (EO) shortly after returning from Beijing that actually has plenty for fintechs and financial services companies to think about—if not cheer for.

Let’s take a look at five top takeaways from the EO, titled Integrating Financial Technology Innovation into Regulatory Frameworks.


From containment to enablement

The executive order directs Federal financial regulators to review existing policies to “facilitate innovation and greater competition in the provision of financial services.” Even more directly, the order calls upon regulators to “take steps to encourage innovation by, and growth of, fintech firms and federally regulated institutions of all sizes.”

The “fintechs and friends” framing of the executive order is in and of itself telling. After years of trying to strike a balance between the needs of incumbent banks and financial services providers and insurgent fintech innovators, the EO suggests a potential shift from “containment” of fintech innovation to outright enablement.

More access to Fed payment rails

Operationally speaking, some of the biggest news in the EO might be the way it directs the Federal Reserve to review its approach to granting payment accounts and services. This includes potentially expanding access to Fed payment rails for fintechs and nonbanks. Practically speaking, this could incentivize easier access to Fed payment infrastructure, Fedwire, and settlement services typically reserved for bank intermediaries.

The EO criticizes “regulations, guidance, and policies” that it referred to as “relics of a time when financial services where predominantly provided in brick-and-mortar-centric settings.” While this potentially refers to a fairly broad range of existing directives, the tone clearly indicates a willingness to overhaul or at least revisit rules that fail to reflect our increasingly mobile, digital, and even agentic contemporary financial landscape.

Building better bank-fintech partnerships

The EO is also critical of “rules governing financial institution’s third-party risk management” which it claims unfairly favors incumbents “at the expense of innovators.” As such, the order directs regulators to examine supervisory practices, application processes, and guidance that may “unduly impede fintech firms from entering into partnerships with federally regulated institutions.”

This could positively impact opportunities for Banking-as-a-Service companies as well as sponsor bank relationships, charter applications, and more, potentially reducing some of the challenges and complexity brought on by regulatory uncertainty with regard to partnerships between banks and fintechs.

Crypto and stablecoins move toward the mainstream

With the passage of the GENIUS Act, it is clear that the administration is seeking to support, if not encourage, innovation in the digital asset space. This week’s executive order underscores that support, noting that President Trump signed an Executive Order in his first week in office that was designed to “secure” the United States’ position as the global leader in the “digital asset economy,” as well as to establish additional regulatory clarity and guidance for digital assets. Other EOs are also referenced, including the one in March 2025 that established the Strategic Bitcoin Reserve and US Digital Asset Stockpile.

Specifically, this week’s executive order directs the Federal government to “update its outdated regulations to allow integration of digital assets and other novel financial technology into traditional financial services and payment systems.” Clearly and increasingly, the Trump administration sees digital assets, blockchain technology, and stablecoins as key components of US financial system infrastructure rather than as niche products, isolated technologies, or speculative instruments.

A win for regulated fintechs?

From the wave of fintechs seeking bank charters to the increased regulatory clarity provided by recent executive orders, fintechs could be on the precipice of a “best of both worlds” scenario: a financial services industry that feels deregulated and more opportunity-rich due to what mighr actually be greater regulation and guidance. While there remains much to be seen in terms of how fintechs and nonbanks take advantage of this changing regulatory environment—from pursuing bank charters to more aggressively pursuing embedded and open finance technologies—it does seem clear that the US is positioning itself to be more competitive in a shifting, global fintech and financial services landscape


Photo by Tomasz Zielonka on Unsplash
5 Things to Know about the CLARITY Act

5 Things to Know about the CLARITY Act

The US Senate Banking Committee unveiled the latest version of the CLARITY Act this week. The Act aims to establish a clear regulatory framework for digital assets.

The CLARITY Act offers enforceable guardrails for digital asset markets in an effort to protect consumers and investors, counter illicit finance and security threats, and support innovation in the US.

The bill is controversial, as it includes provisions to limit liability for decentralized software developers and enters an ongoing debate around whether stablecoins should be permitted to offer yield or yield-like rewards. After more than 10 months of bipartisan negotiations, the Senate Banking Committee is preparing for a key procedural markup. Here are five things you need to know about the new version of the CLARITY Act.

More than crypto regulation

While crypto regulation is making headlines, the Act comes with broader stakes as it also attempts to define who controls the future infrastructure of digital finance in the US. Supporters argue the Act helps preserve a more market-driven and decentralized approach by defining the boundaries of governmental power while protecting the autonomy of private developers and individual users.

This debate extends beyond crypto trading and will ultimately determine who will own and govern the next generation of financial rails. Stablecoins, tokenized assets, and AI-driven financial agents are on the rise, and the rules governing those future financial rails are yet to be settled. The companies and platforms controlling the new infrastructure could hold influence similar to what cloud providers, mobile operating systems, and card networks hold today.

Delineates between securities and commodities

The debate over whether digital assets are considered securities has been around for about a decade. That’s why determining when a token is treated like a security and when it can transition into a commodity is one of the biggest goals of the CLARITY Act. The determination will dictate how exchanges and platforms operate, which regulator oversees it, and what disclosures are required.

Yield is a battlefield

The debate over whether or not stablecoins can pay yield (or yield-like rewards) has been a major sticking point between banks and crypto firms. While banks argue that stablecoin yield products could compete directly with deposits and pull money out of the traditional banking system, crypto companies argue that restrictions would hurt innovation and competitiveness.

The Act does not explicitly use the term “yield” in relation to stablecoins. However, it does establish a regulatory framework that distinguishes between different types of digital assets based on whether they provide a financial return, such as interest. The CLARITY Act implies that if a digital asset provides a right to interest, it would likely fall under the jurisdiction of securities laws rather than being treated as a digital commodity or a permitted payment stablecoin.

While separate stablecoin legislation continues to evolve in parallel in the form of the GENIUS Act, the CLARITY Act intersects with those debates because of how digital assets offering financial return may ultimately be categorized.

About global competitiveness

Supporters of the Act argue that it is less about embracing crypto speculation and more about preventing the next generation of financial infrastructure from being built outside the US. Europe, Hong Kong, the UAE, and Singapore have already moved ahead with digital asset frameworks, and if the US does not create a set of regulatory guardrails within this arena, banks, fintechs, and crypto firms will feel less safe innovating in the digital asset space.

Even if it passes, the debate is far from over

The legislation does not resolve every concern. In fact, there are still ongoing debates around AML protections, DeFi oversight, systemic risk, political conflicts of interest, and consumer protection. So while the CLARITY Act brings more regulatory transparency to crypto, it also accelerates a broader debate about who will govern the future infrastructure of digital finance as stablecoins, tokenized assets, and AI-driven financial systems become more integrated into commerce and payments.


Photo by akbar fathi

Four Fintechs Driving Payments, Infrastructure, and Embedded Finance

Four Fintechs Driving Payments, Infrastructure, and Embedded Finance

Financial infrastructure is becoming increasingly valuable as it powers payments and financial products. Instead of operating within closed systems, banks are now operating within broader ecosystems in which customers expect seamless integrations, faster money movement, and financial services experiences that become invisible within the customer journey.

Fintechs are working to satisfy the demand for this infrastructure using API-driven tools that can support real-time payments, cross-border transactions, and embedded finance use cases. At FinovateSpring 2026, we’re hosting a group of fresh fintechs that will showcase their solutions designed to simplify payments, modernize infrastructure, and unlock new revenue opportunities. From digital asset infrastructure to cross-border payments and operational platforms, these four companies leading the way.


AlphaPoint

AlphaPoint enables smaller financial institutions to adopt stablecoin payments and treasury capabilities without the cost and complexity of building in-house infrastructure. Its platform provides the tools banks need to support digital asset transactions, helping them modernize payments and compete with larger, more technologically advanced players.

Founded in 2013 and headquartered in New York, AlphaPoint gives banks a faster path to integrating blockchain-based financial services, positioning them to participate in real-time, programmable money.


Quanto

Quanto helps businesses reduce operational friction across financial workflows by streamlining back-office processes, allowing companies to focus on growth.

Founded in 2025 and headquartered in Chicago, Quanto helps organizations scale more efficiently, reduce complexity, and accelerate time to scale.


Reativ

Reativ’s cloud-based treasury management system offers financial institutions real-time visibility into cash positions, liquidity, and risk. Its platform combines automation and AI-driven insights to help banks optimize cash usage, reduce operational costs, and improve decision-making.

Designed for regional and community banks as well as credit unions, Reativ can reduce operational expenses by up to 50% while enhancing regulatory readiness. Founded in 2026 and headquartered in Portland, Oregon, the company offers a modern, centralized approach to treasury management.


Clockout

Clockout helps financial institutions drive deposit growth and customer engagement through embedded financial wellness tools. Its platform is designed to increase direct deposits, boost per-user revenue, and differentiate banks and credit unions in competitive markets.

Founded in 2022 and headquartered in Tennessee, Clockout enables institutions to deepen relationships with their customers while creating new revenue opportunities tied to everyday financial activity.

Why banks should care

Banks are under pressure to offer faster money movement, integrate with third-party platforms, and meet rising customer expectations. At the same time, firms need to manage costs and are constrained by legacy systems.

Fintechs are helping bridge this gap with solutions that simplify treasury management, enable stablecoin and real-time payments, and streamline operational workflows that allow institutions to modernize without large-scale overhauls. At the same time, embedded finance and deposit-driving tools create new opportunities to grow balances, increase revenue per customer, and stay competitive in an increasingly platform-driven financial ecosystem.


Photo by Artur Łuczka on Unsplash
Five Companies Powering Financial Wellness and Consumer Engagement

Five Companies Powering Financial Wellness and Consumer Engagement

For financial institutions, growth involves deepening relationships with existing customers. At a time when switching financial institutions comes at a low cost and fintechs offer many of the same benefits as traditional banks, customer engagement and financial wellness have become strategic priorities.

For traditional financial institutions whose offerings can seem static, providing personalized experiences that help customers save smarter, build better financial habits, and feel more in control of their financial lives can help retain and win over clients. The banks that succeed will be those that can embed themselves into customers’ day-to-day financial decisions.

At FinovateSpring 2026, five companies are focused on helping banks do exactly that. From savings and financial wellness tools to engagement platforms and next-generation consumer experiences, these solutions are designed to drive loyalty, increase product adoption, and deliver measurable value to both customers and institutions.


Plinqit

Business HYS by Plinqit helps banks compete for deposits while giving small and medium-sized businesses (SMBs) more effective ways to manage their cash. The platform is designed to drive deposit growth by offering high-yield savings experiences tailored to business customers, an area where many traditional banks have struggled to differentiate.

Headquartered in Ann Arbor, Michigan and founded in 2015, Plinqit enables financial institutions to attract and retain SMB deposits without overhauling their existing infrastructure which ultimately helps level the playing field to compete against larger competitors and digital-first challengers.


Goodfin

Goodfin is expanding access to alternative investments by opening institutional-grade opportunities to a broader range of investors. Its platform is designed to help financial institutions and fintechs offer differentiated wealth-building tools such as private equity, venture capital, and pre-IPO deals that go beyond traditional stocks and bonds.

Founded in 2022 and headquartered in San Francisco, Goodfin enables banks to meet growing customer demand for access to alternative assets, while positioning themselves as gateways to more sophisticated investment opportunities.


Level

Level helps auto lenders reduce losses by identifying and recovering missed value in total loss insurance claims. Its AI-powered claims management platform centralizes workflows into a single portal, enabling lenders to detect undervalued claims and dispute them at scale.

Backed by licensed claims experts, Level combines automation with human oversight to increase recoveries, reduce deficiency balances, and accelerate time to payment. Headquartered in New York and founded in 2023, the company offers banks, credit unions, and lenders a way to improve operational efficiency while directly impacting the bottom line.


BankUniverse

BankUniverse delivers a privacy-first intent engine that helps financial institutions identify and convert high-value prospects without relying on sensitive personal data. By analyzing user intent signals rather than personal identifiers, the platform enables banks to drive digital sales while maintaining strong data privacy standards.

Founded in 2024 and headquartered in Greece, BankUniverse helps institutions increase conversion rates while navigating growing regulatory and consumer expectations around data protection.


Bluum Finance

Bluum Finance provides a unified platform for embedded investing, combining brokerage, custody, and reporting into a single API. Its infrastructure allows financial institutions and fintechs to launch fully compliant investment offerings quickly, without the complexity and cost typically associated with building these capabilities in-house.

Founded in 2025 and headquartered in Los Angeles, Bluum enhances its offering with AI-powered advisory tools that deliver personalized investment experiences. The platform is built for a wide range of providers looking to bring investing into their existing customer journeys.

Why banks should care

Financial wellness and engagement are quickly becoming primary drivers of growth instead of nice-to-have features. Banks are under pressure to increase deposits, deepen relationships, and create new revenue streams while competing with fintechs that are often more agile and user-focused. Platforms that help customers save more effectively, access new investment opportunities, or receive more personalized financial guidance can translate directly into higher balances, stronger loyalty, and increased product usage.

At the same time, these tools enable banks to expand their role in customers’ financial lives without significantly increasing operational complexity. Whether it’s embedding investing capabilities, improving digital acquisition, or unlocking overlooked sources of value in existing portfolios, financial wellness platforms offer a practical way for institutions to drive both customer outcomes and business performance.


Photo by www.kaboompics.com

Five Companies Advancing Credit Access and Lending Infrastructure

Five Companies Advancing Credit Access and Lending Infrastructure

One of the great promises of fintech innovation is the idea of democratizing finance. This includes everything from helping more deserving borrowers secure access to credit to helping a new generation of savers and investors learn good habits that will ensure financial wellness from young adulthood through retirement. As much of the fintech world becomes increasingly—and understandably—obsessed with the latest developments in AI and decentralized finance, a sizable contingent of innovators continues to solve practical problems for students, young savers, and credit-starved small businesses.

This year at FinovateSpring 2026 in San Diego, May 5 to May 7, we will introduce five fintechs that will show how their latest innovations use advanced technologies to simplify international payments for students, boost financial literacy for teens and their families, and enhance small business lending with AI-powered underwriting and alternative data.


Crebit Pay

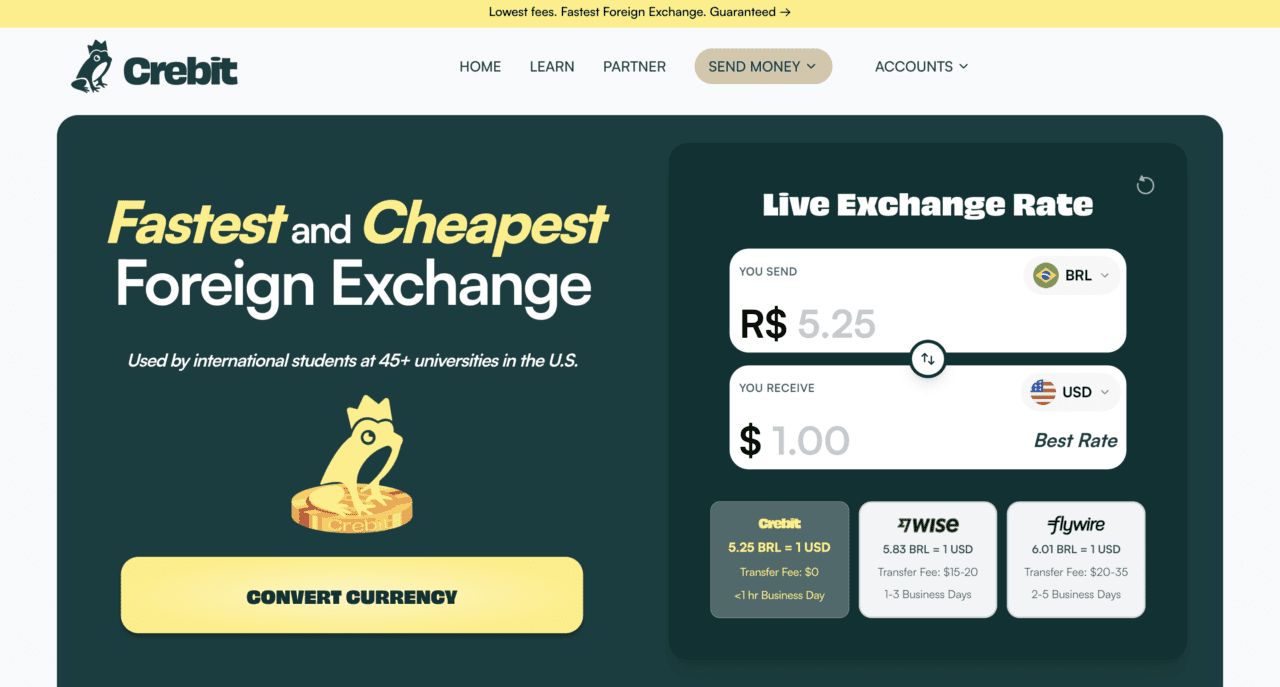
Crebit Pay is a stablecoin-powered FX platform enabling low-cost, near-instant global payments for students, while helping credit unions onboard and serve international members.

Crebit Pay’s platform provides near-instant settlement and is 4-10% cheaper than traditional FX. It serves underserved corridors ignored by major providers, offering a stablecoin infrastructure that is fully invisible to users, fiat in and fiat out.

Founded in 2025, Crebit Pay is headquartered in San Francisco, California.


GenAspire

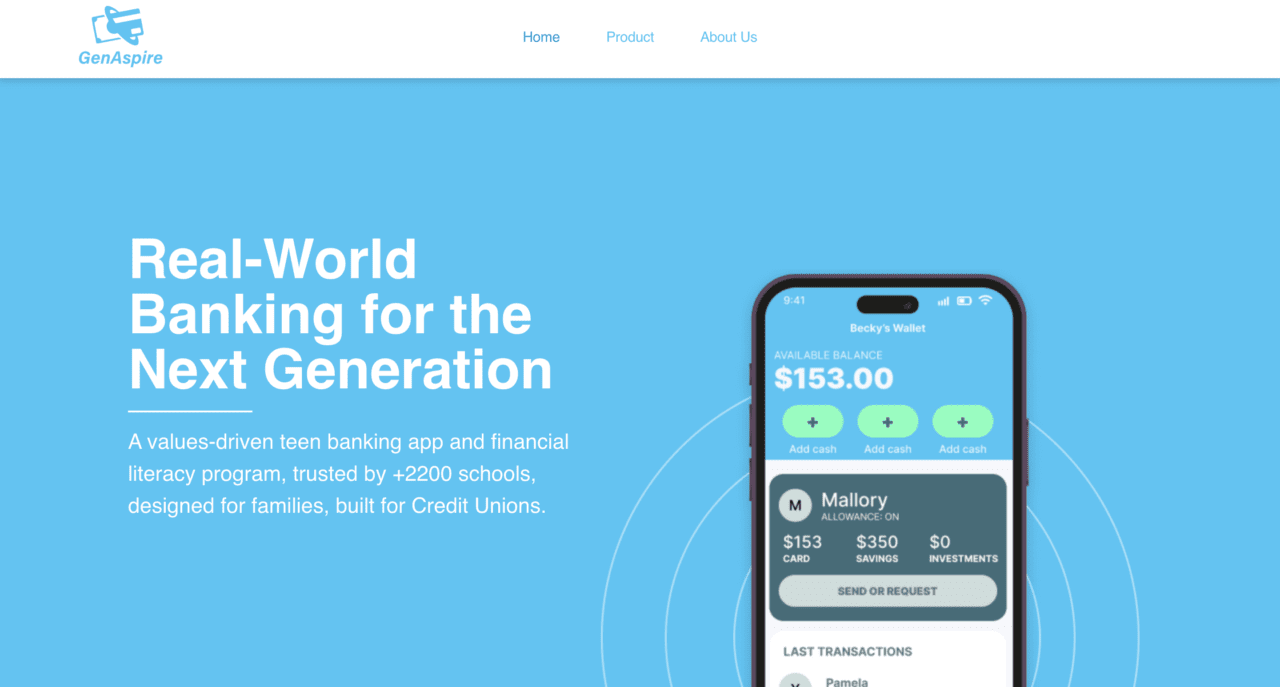
GenAspire offers real-world banking for the next generation. The company’s values-driven teen banking app and financial literacy program is trusted by more than 2,200 schools, designed for families, and built for community financial institutions. Designed for credit unions and community banks, GenAspire’s technology gamifies teen banking and incentives financial literacy.

Headquartered in Boynton Beach, Florida, GenAspire was founded in 2025.


Nextvestment

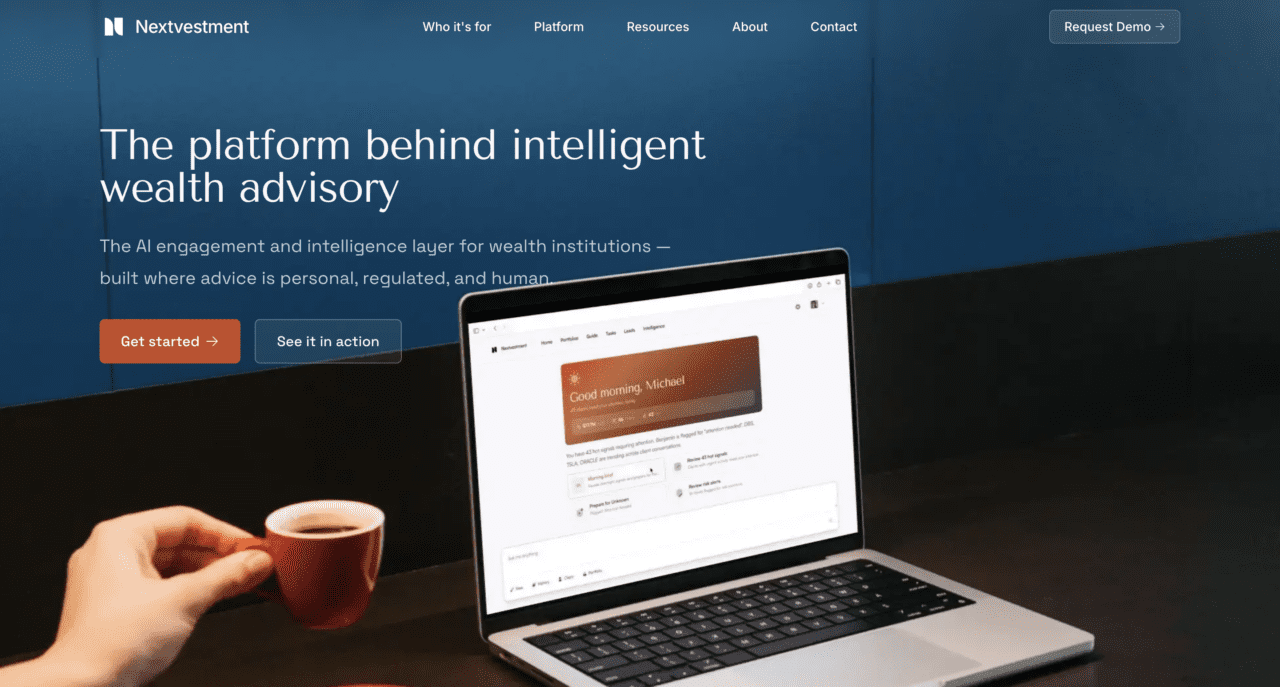
Nextvestment enables safe self-service exploration while guiding advisors to intervene at the right moments, improving client engagement and advisor productivity without changing advisory models. The company’s generative AI platform, designed for financial institutions, family offices, and individual advisors, delivers real-time insights, proactive compliance, and personalized client experiences.

Founded in 2024, Nextvestment is headquartered in Singapore.


PROVIDR

PROVIDR approves more qualified SME loans faster and cheaper but without additional risk through AI-driven, alternative-data underwriting, while reducing costs, improving accuracy, and growing market share. The company’s agentic credit platform gives loan officers the resources they need to make faster lending decisions, with more accuracy and full control.

Headquartered in Boston, Massachusetts, PROVIDR was founded in 2025.


Vine Financial

Vine Financial enables lenders to scale commercial portfolios without adding staff, accelerate deal approvals, and adopt responsibly—turning underwriting from a manual bottleneck into a strategic advantage. The company’s platform lets financiers and borrowers collaborate more effectively, orchestrating the process to ensure that deals flow smoothly.

Founded in 2019, Vine Financial is headquartered in Austin, Texas.

Why banks should care

Expanding access to underserved markets, enhancing financial literacy, and improving operational efficiency and productivity are three areas where fintechs like these can help banks reach more customers, boost engagement, and generate better margins. At a time when it is becoming increasingly difficult for financial institutions to differentiate themselves from the crowd, strategies that can help them attract new customers and empower current customers to become better stewards of their own financial lives are critical.

All of these goals also represent practical opportunities to use technologies such as AI and decentralized finance. AI is making it easier for lenders to analyze both traditional and alternative data to uncover qualified borrowers that traditional underwriting strategies have tended to overlook. Decentralized finance is poised to revolutionize payments, making low-cost, near-instant payment options more broadly available, helping financial institutions better serve international customers while creating new potential revenue streams. Lastly, the ability of AI and DeFi to help eliminate inefficiencies and reduce costs is another main reason why banks and other financial institutions should look closely at the real-world applications of these still-evolving technologies.


If you are enjoying our preview of the companies demoing at FinovateSpring this year, then join us in San Diego on May 5 through May 7. Tickets are on sale now. Save your spot. Book your room. And bring your sunscreen!

Photo by Andrea Piacquadio

Five Innovators Transforming Financial Decisioning with Data and Analytics

Five Innovators Transforming Financial Decisioning with Data and Analytics

How can banks, credit unions, and other financial institutions transform the massive volumes of data they process every day into actionable insights that can drive better decision-making, identify inefficiencies, and engage more customers? How will technologies like AI specifically help financial institutions challenged by competition from non-bank rivals, ever-evolving consumer expectations, and regulatory uncertainty?

This year at FinovateSpring 2026, we are showcasing five innovative fintechs that will demonstrate their solutions to help banks, credit unions, and other financial institutions boost productivity, manage risk, and create compelling experiences for their customers and members.


Bloomfire

Bloomfire transforms financial organizations by centralizing knowledge, accelerating decision-making, ensuring regulatory compliance, reducing operational costs, and driving revenue growth through improved productivity.

Founded in 2011, Bloomfire is based in Austin, Texas.


ContexQ

ContexQ is a forensic Graph AI that detects fraud, money laundering, and hidden beneficial ownership by seeing the relationships every other AI misses.

Headquartered in Singapore, ContexQ was founded in 2024. The company’s technology resolves fragmented identities across more than one billion entities in 12+ languages, predicts emerging fraud patterns using Graph Transformers, and unifies risk and revenue intelligence in one graph.


Finalytics.ai

Finalytics.ai enables financial institutions to instantly unleash the power of AI by offering segment-of-one digital experiences for visitors informed by behavioral, transactional, and third-party data.

Founded in 2021, Finalytics.ai is headquartered in San Francisco, California.


Socratix.ai

Socratix AI helps financial institutions cut fraud losses, reduce false positives, and scale operations without adding headcount—driving efficiency, trust, and stronger customer relationships.

Headquartered in San Francisco, California, Socratix AI was founded in 2025.


Whatfix

Whatfix is an AI-native digital adoption platform that helps banks and other financial institutions accelerate system adoption, enforce compliance, and achieve measurable outcomes across mission-critical workflows.

Founded in 2013 and headquartered in San Jose, California, Whatfix offers technology that provides real-time contextual guidance powered by AI-driven ScreenSense, product analytics tied to workflow adherence and business outcomes, and mirror + AI roleplay for risk-free simulation and behavioral training.

Why banks should care

Managing risk, providing compelling personal experiences for customers, and keeping costs low are three paramount challenges for banks, credit unions, and other financial institutions in 2026. Fortunately, all three are areas where technologies such as automation, machine learning, and AI have proven their effectiveness in detecting fraud, customizing user journeys, and identifying workflow inefficiencies and bottlenecks.

Meeting these challenges by embracing fintech innovation is not only a way for banks to ensure regulatory compliance, stay ahead of fraudsters, and become more efficient—it also offers opportunities for specialization and differentiation within the field. At a time when more and more companies are adding financial services to their product mix, innovations that also help banks and credit unions stick out from the crowd are as valuable as ever.


If you are enjoying our preview of the companies demoing at FinovateSpring this year, then join us in San Diego on May 5 through May 7. Register today using this link and save 20%.

Photo by Markus Winkler

Five AI Platforms Reimagining Banking Operations and Intelligence

Five AI Platforms Reimagining Banking Operations and Intelligence

In 2026, financial services have jumped well beyond the AI experimentation phase. At this point, firms are no longer considering whether or not to adopt AI, and are instead thinking about deployment strategies that will improve operations, decision-making, and internal productivity.

When organizations apply AI to their everyday processes, they can analyze data more effectively, automate workflows, glean insights, and help teams make better decisions with less manual effort. Regardless of the subsector, AI-driven platforms are becoming essential to creating modern banking infrastructure.

At FinovateSpring 2026, a fresh group of five companies will demonstrate their newest technologies that help banks turn AI from a buzzword into a practical tool for operational intelligence and efficiency.


Ventus AI

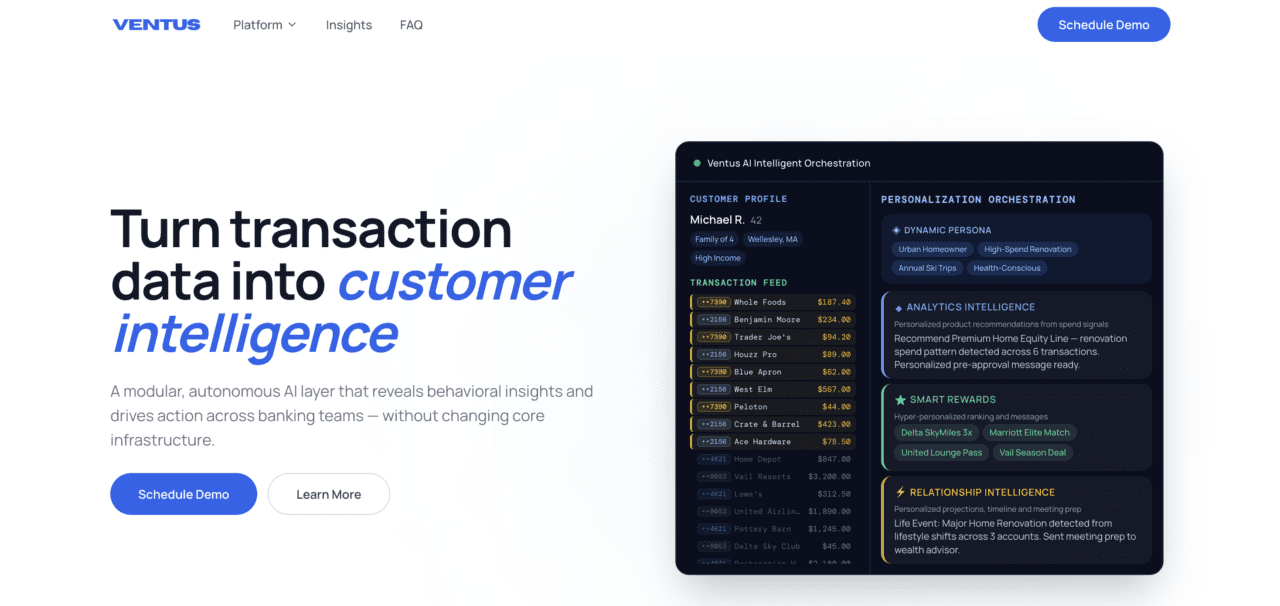
Founded in 2025, Ventus AI transforms raw banking transaction data into semantic customer intelligence to enable personalized experiences, smarter analytics, and human-centered digital banking without changing core infrastructure.

The Delaware-based company helps banks and wealth managers turn transactions into dynamic personas, proactively detect customer life events, and offer plug-in intelligence for any core banking system.


Zengines

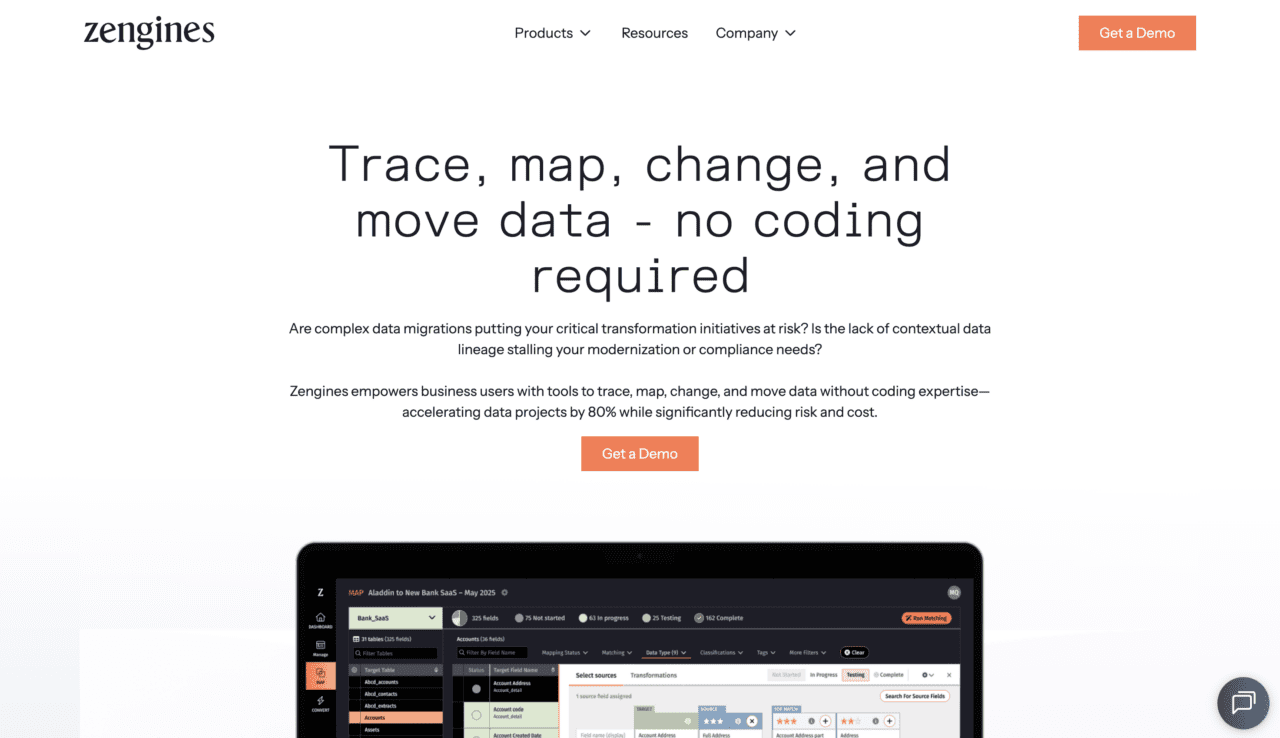
Zengines addresses data transformation challenges to modernize mainframes without losing logic. The platform helps organizations work with legacy code to seamlessly migrate data into modern systems. The company offers two products: Data Lineage, which offers critical and easy-to-understand insights into firms’ legacy systems; and Data Migration, which empowers business analysts to drive the entire process without coding expertise.

Headquartered in Bedford, Massachusetts, Zengines’ modern approach makes legacy systems searchable, which helps firms satisfy auditors faster so transformation and compliance don’t stall.


Lyzr AI

Lyzr Architect is an enterprise AI platform that converts natural language into governed, production-ready agentic applications. Founded in 2023, the company offers a platform that enables secure, compliant deployment across banking, financial services, and insurance enterprises.

The New Jersey-based company helps convert natural language into production-grade multi-agent applications, provides deterministic validation with governance and audit logging, and offers full-stack apps, exportable code, and GPU-optimized model execution.


Saris AI

Founded in 2024 and headquartered in San Francisco, California, Saris AI is an agentic AI solution that builds and launches AI agents to automate back-office workflows. The company helps banks and credit unions scale their operations without adding headcount by automating 90% of their tasks with zero change management.

Saris AI securely integrates with core banking platforms, loan origination systems, document repositories, and communication tools to help organizations lower workflow costs.


Syntex

Syntex’s digital onboarding software helps banks and credit unions verify documents, track approvals, and reduce small-business onboarding to a matter of days.

Founded in 2025, the company offers a self-serve client intake with document verification; provides real-time tracking of documents, approvals, and ownership; and reduces onboarding from weeks to days with a Reg B audit trail.

Why banks should care

For financial institutions, the promise of AI extends well beyond simply delivering a better customer experience. In 2026, fintechs are bringing great opportunities to help firms modernize legacy operations without dramatically increasing costs or headcount.

Banks face mounting pressure to process more data, respond faster to customers, and maintain compliance in today’s increasingly complex regulatory environment. AI platforms that can surface insights from transaction data, automate internal workflows, and help teams navigate complex systems bring a practical way to improve productivity and decision-making.


FinovateSpring 2026 will take place at The Sheraton San Diego on May 5 through 7. Register today using this link and save 20%. Finovate attracts 600 bankers from across the spectrum—afrom the largest US banks to regional banks, community banks, and credit unions.

Photo by Google DeepMind

Videos from the 22 Demos at FinovateEurope 2026 are Live

Videos from the 22 Demos at FinovateEurope 2026 are Live

If you missed out on FinovateEurope earlier this month, you don’t have to feel left out any longer. The 22 demo videos are now live (and free to watch!) on the Finovate website and on Finovate’s YouTube channel.

Each seven-minute video offers a fast and efficient way to catch up on the latest new launches in fintech. We’ve highlighted the three Best of Show-winning demos below to get you started.


R34DY’s ABLEMENTS platform


Serene


Tweezr.io

For more coverage of on-stage content at FinovateEurope, check out our post-show analysis. And if you don’t want to miss out on the live action next time around, be sure to register for FinovateSpring, taking place on May 5 through 7 in San Diego, California. We’ll see you there!

Sustainability, Quantum, and Cloud: Three Dogs That Did Not Bark at FinovateEurope 2026

Sustainability, Quantum, and Cloud: Three Dogs That Did Not Bark at FinovateEurope 2026

Great conferences are defined largely by what does happen: what themes are discussed, what trends generate the most passionate conversations. But great conferences are also defined by what doesn’t happen: by those topics and trends that have become exhausted, failed to live up to the hype in the first place, or simply aren’t ready for prime time.

Having just looked at some of the main topics of discussion at FinovateEurope, today we’re taking a quick tour through the pound to learn more about the dogs that did not bark at FinovateEurope 2026 last week.


Sustaining Sustainability in the Age of AI

Sustainability has been a stronger theme among fintech innovators in the UK and the EU compared to the US—and arguably all the more so given the fusillade of disincentives from the Trump Administration. Past Finovate conferences have showcased fintechs such as Connect Earth (UK), ecolytiq (Germany), and Little Blocks (India) that are helping institutions and individuals calculate their environmental impact; reduce carbon emissions via online marketplaces, and align their investing and banking preferences with their attitudes toward the environment.

While never a large fraction of the demoing companies at any given show, it was notable that no companies focused on sustainability on the demo stage. This likely reflects at least in part the shift in emphasis toward AI and blockchain-related innovations, especially as these innovations are increasingly moving from the experimental to real-world use cases. Even as these enabling technologies appear to be in their earliest stages, the fact that they already are responding to real problems in financial services makes them an especially attractive field for innovation compared to sustainability.

It is important to note that this does not necessarily mean that there has been a decline in interest in sustainability and climate-related fintech innovation. In fact, investment in climate-related fintech—and climatetech in general—increased from 2024 to 2025. Europe represented a significant amount of the $103 billion raised globally at 56%, with US-based funds contributing 16% toward the international total. But sustainability is increasingly being seen less as a standalone solution, and more as a cost-cutting feature to be integrated as in embedded finance or as part of a broader risk and data analytics package. Those looking for sustainability to return to the center stage will likely need to see the rise of stronger regulatory mandates such as those for stricter environmental financial disclosure or other incentives. Technological innovation alone may not do it.


Quantum Computing: Waiting for the Great Leap Forward?

While there was a sole presentation on quantum computing at FinovateEurope, the discussion of this technology still remains limited in most fintech forums. This is despite the conviction by analysts that quantum computing will make a significant impact on all technology—including financial technology—in the years to come. It is also interesting insofar as we are seeing emerging, enabling technologies in AI and the blockchain that continue to surprise detractors and outperform expectations when it comes to practical use cases. Why not quantum computing?

First, credit where credit is due: Day One of FinovateEurope featured Amal Nazar, Head of GTM at Wultra, a firm that provides post-quantum authentication solutions to financial institutions around the world. Nazar’s Special Address emphasized that it was important for banks and other financial institutions to transition to post-quantum cryptography in order to secure long-term digital operations. With regulators urging firms to complete this shift by 2030, it is clear that whatever conversations we are not yet having with regard to quantum computing will likely begin sooner than we think.

But not quite yet. Unlike AI and blockchain-based technologies like stablecoins, quantum computing is still significantly “pre-commercial,” meaning that while there is considerable investment interest, practical commercial applications in financial services have yet to materialize. There are a number of reasons for this, but essentially the issue is developmental (read: hardware) rather than software or regulation-related in the cases of AI and stablecoins, respectively. Arguably, when it comes to quantum computing, this technology as it applies to financial services is about where AI and stablecoins were seven to ten years ago: long on hype and promise, but short on use cases. Those use cases are developing; as Nazar’s presentation suggests, cryptography is one of the primary areas where we should anticipate quantum computing use cases emerging. But compared to AI and stablecoins, quantum computing may experience the “always a bridesmaid, never a bride” syndrome for a few more seasons, at least.


“Nobody Here But Us Cloud Companies …”

If you suspected that the inclusion of “cloud” as a theme that was underrepresented at FinovateEurope was little more than a ruse to talk about AI, then I confess to being guilty as charged. But the comparison between the “cloud revolution” and the “AI revolution” was one I heard from Finovate delegates and on-stage experts alike, and an interesting notion to add to this conversation on fintech trends.

No company demoing declared themselves a cloud company this year. That’s because, in a sense, they are all “cloud companies.” The ubiquity of cloud technology in fintech has rendered the descriptor almost obsolete. And increasingly something similar is happening with AI. While we did go through the obligatory period when companies felt the need to append “ai” to their names, we are nevertheless seeing an impressive urgency with which companies are seeking to leverage AI to improve efficiency for both their own workers as well as for their customers. Perhaps not since the early days of digital banking has as much attention been paid and innovation devoted to both sides of the customer experience at the same time.

What this means, as Senior Finovate analyst Julie Muhn remarked to me in the run-up to FinovateEurope this year, is that there is less and less a conversation about “AI,” and more and more a conversation about generative AI, or explainable AI, or agentic AI, or ethical AI … You get the point. The evolution in our way of talking about AI reflects nothing more than our growing understanding of the diverse ways AI technology can be deployed, as well as the myriad responsibilities involved in deploying it. So while we won’t stop hearing about “AI” anytime soon, we should be prepared for a new way of talking about the technology as our relationship to it evolves.


Photo by Anoir Chafik on Unsplash
Three Fresh Lending Tools that Are Redefining Credit Decisioning

Three Fresh Lending Tools that Are Redefining Credit Decisioning

As banks digitize their lending processes and seek to expand credit access across borders, it is becoming increasingly difficult to make fast, accurate credit decisions. To mitigate risk, lenders need real-time insights into spending habits, automated functionality, and visibility into a broader set of data, especially as they seek to improve speed, enhance the customer experience, and maintain compliance.

At FinovateEurope 2026, a new group of fintechs will showcase how they are addressing these challenges by bringing intelligence and automation directly into the lending process. From sourcing alternative credit data to deploying AI-driven lending agents, the companies below are helping banks and lenders modernize credit decisioning while keeping risk in check.

FinovateEurope 2026 will take place at London’s InterContinental O2 on February 10 and 11. Tickets are available now. Visit our FinovateEurope hub today and save your spot!


Intuitech

Intuitech brings live AI agents into lending workflows to automate manual, time-consuming processes across origination and servicing. The company helps lenders streamline tasks including data collection, validation, and borrower interactions. This automation helps reduce operational burden while improving speed and consistency.

By embedding AI agents directly into clients’ lending operations, Intuitech enables them to scale their lending activity without requiring additional talent in-house. The automated approach helps bring modern credit delivery to lenders of all sizes.

Mifundo

Mifundo’s technology enables customers to assess cross-border credit risk by sourcing and standardizing credit data from across European markets. The company helps lenders better evaluate borrowers with international financial histories by assess creditworthiness for mobile, expatriate, and cross-border customers. Mifundo enables banks to reach more borrowers, as many are underserved by traditional credit systems and therefore are overlooked.

With remote work becoming more popular and the potential for cross-border lending increasing, firms are realizing that there is a gap in data for European credit markets. Mifundo closes this gap by expanding access to reliable credit information, ultimately helping lenders minimize risk while unlocking new lending opportunities across borders.

Sea.dev

sea.dev provides real-time risk insights designed to help lending teams make better credit decisions across the loan lifecycle. The company’s platform aggregates and analyzes borrower, portfolio, and market-level data to offer lenders clearer visibility into risk exposure, ultimately supporting faster approvals.

sea.dev enables lending teams to continuously monitor risk and adapt decisions as inputs change. The company’s more dynamic, insight-driven approach helps lenders explore more products and serve new borrower segments.

Why banks should care

With more consumer data available than ever before, lenders can now underwrite loans more effectively, especially for customers who were once considered risky or had limited credit histories. This abundance of data also introduces new challenges, including inaccurate, unclean, or cross-border information that can complicate analysis and require specialized expertise. Fortunately, new tools are emerging to help automate data collection, filtering, and validation. These tools have the potential to enable lenders of all sizes to expand their reach and better serve a broader customer base.


Photo by RDNE Stock project