Embedded Finance Platform Array Acquires Penny Finance, Chimney, EarnUp

Embedded Finance Platform Array Acquires Penny Finance, Chimney, EarnUp

Embedded finance platform Array has been on a truly remarkable acquisition pace in recent weeks. The company, which won Best of Show in its Finovate debut at FinovateFall 2021 and again in its return to the Finovate stage for FinovateSpring 2022, acquired fellow Finovate alum—and fellow Best of Show winner—Penny Finance in late February. This move came just a few days after Array announced its acquisition of another Finovate alum and Best of Show winner, Chimney.

And just to show that Array’s appetites are not limited to Best of Show-winning Finovate alums, the company also announced its acquisition of paytech EarnUp less than a month ago.

What do these acquisitions mean for Array? Overall, these deals represent the company’s strategy to provide its financial institution partners with modular, embeddable tools and data that enable them to boost engagement, improve retention, and secure measurable value. Designed to complement the solutions currently offered by fintechs, financial institutions, and digital brands, Array’s embedded, invisible-by-design approach allows consumers to enjoy a wider range of financial solutions and services while still relying on the brands they know and trust.

Consider Penny Finance. Penny Finance is an online financial planning engine that enables credit unions and community banks to provide personalized education, resources, and services to their members and customers. Headquartered in Boston, Massachusetts, and founded in 2020 by CEO Crissi Cole, Penny Finance helps individuals and families pay off debt, begin investing, and build wealth—all within a unified, integrated solution. Array Founder and CEO Martin Toha said that acquiring Penny Finance will enable Array to serve consumers the same way that they experience financial challenges and responsibilities: “as part of a single, ongoing journey.”

“Penny Finance strengthens our ability to support that full picture,” Toha said, “enabling our partners to deliver more holistic, consumer-first financial experiences directly within the products people already use.”

The acquisition will empower Array to help its clients address a broader range of consumer needs and complements the company’s current credit, identity, and privacy offerings with solutions to help consumers enhance their financial wellness through better savings behavior and financial planning.

“Penny was built to give people confidence in how they spend, save, and plan—without judgment or complexity,” Penny Finance’s Cole said. “By joining Array, we can scale that mission and integrate financial education and planning tools into trusted experiences that already play a meaningful role in people’s financial lives.”

Array’s acquisition of Chimney will add the fintech’s modern financial calculators and home value tracking tools to its platform offerings. Founded in 2020 and based in Brooklyn, New York, Chimney helps more than 160 financial institutions in the US leverage real-time property data and predictive analytics to engage homeowners and grow loans. Chimney’s technology identifies high-propensity opportunities for home equity, refinancing, new mortgages, and more, enabling financial institutions to target the right customers and members at the right time with personalized offers delivered inside their banking apps and platforms. In his statement, Chimney CEO and Co-Founder Matthew Covi underscored this last point, highlighting the value of embedded finance in helping consumers get the resources they need while remaining engaged with the brands they trust.

“Traditional financial institutions are where the majority of Americans manage their finances,” Covi said. “By empowering these institutions with personalized, data-driven solutions that modernize the banking experience, we’ve realized our mission of helping millions of Americans live healthier financial lives.”

Lastly, EarnUp is a payments technology firm that helps consumers better manage debt and bills by aligning mortgage, loan, and bill payments with pay cycles. By enabling them to disaggregate large, inflexible monthly payments into smaller contributions aligned with their paychecks, EarnUp helps lower the amount of missed payments to creditors and financial stress for debtors. Headquartered in San Francisco, California, and founded in 2015, EarnUp has completed 50 million transactions with a cumulative value of $43 billion since inception. Brad Woodcox is CEO.

“EarnUp is a long-standing proven product in the home loan space, having supported millions of US mortgage borrowers through deep integrations with leading mortgage servicing platforms,” Toha said. “We hope to use this distribution and product to extend Array’s reach into the home loan payments space. This acquisition strengthens our ability to help financial services providers deliver more practical, consumer-centric experiences—especially for households managing tight margins and multiple debt obligations.”

Founded in 2020 and headquartered in New York City, Array most recently demoed its technology at FinovateSpring 2023. At the conference, the company demonstrated two of its latest financial solutions—HelloPrivacy (now Privacy Protect) and Subscription Manager—to help banks and other financial institutions generate noninterest income and boost engagement while providing customers with resources to help them stay safe online and save money. Privacy Protect helps defend users from identity theft and privacy risks by monitoring and removing personal information from the web. Subscription Manager helps users manage their subscriptions better, canceling unused subscriptions and negotiating lower rates on select subscriptions.

FinovateSpring 2026 will take place at The Sheraton San Diego on May 5-7. Register today using this link and save 20%.


Photo by Toomas Tartes on Unsplash
Mastercard Launches Virtual C-Suite to Offer Small Businesses Executive-Level Insight

Mastercard Launches Virtual C-Suite to Offer Small Businesses Executive-Level Insight

Mastercard is launching a Virtual C-Suite for small business customers this week, introducing agentic AI agents that act as digital executives to provide strategic insights and decision-making support.

The new Virtual C‑Suite is a set of agentic AI-powered tools that are specifically focused on small and medium-sized businesses, which represent roughly 90% of enterprises across the globe and more than half of global employment. By introducing AI agents that mimic executive roles such as CFO, Mastercard is aiming to close the gap between the resources available to large enterprises and those accessible to small businesses.

Mastercard is using its vast experience in payments, data, and security to bring a deeper understanding of how a customer’s money moves. Virtual C-Suite brings intelligence into small businesses’ accounting systems, business software, and banking applications to analyze business performance, identify risks and opportunities, predict likely outcomes, and recommend actions. The tool relies on insights from the billions of transactions processed on Mastercard’s network annually, combined with a business’ financial activity to provide relevant, trusted recommendations on how businesses pay, get paid, and manage working capital.

“Small businesses are the cornerstones of communities, but it’s easy for owners to lose sight of the passions that inspired them when they’re buried in spreadsheets and stretched across multiple roles,” said Mastercard Global Head of Small and Medium Enterprises Mark Barnett. “We hear these pressures from entrepreneurs every day. With Virtual C-Suite, we are bringing the innovative technology, quality data at scale, and strategic expertise usually available to large enterprises to small business owners. Our goal is to turn operational complexity into clarity—helping entrepreneurs regain time, make smarter decisions, and translate their ambition into measurable growth.”

After integrating the new tool, business users and their teams will have access to dashboards and natural language conversational platforms through which they can ask agents direct questions about their accounts, trends, or recommended actions.

Virtual C-Suite will initially launch with a Virtual CFO capability. Mastercard will make additional executive-function roles over time, delivered through financial institutions, accounting platforms, and software providers.

The launch is part of Mastercard’s broader push into agentic AI. The company’s Virtual C-Suite is an advancement beyond basic analytical capabilities, recommending and executing actions across the commerce lifecycle. The new offering highlights how payments networks are adding value by bringing AI intelligence layers to small businesses, combining transaction data with agentic AI to deliver financial insights that traditionally required dedicated finance teams.

Virtual C-Suite’s small business focus is among a series of Mastercard’s recent initiatives aimed at SMEs. In 2024, the company introduced Biz360, a platform designed to help entrepreneurs consolidate and manage the digital tools they rely on to run their operations. Mastercard also rolled out Small Business Navigator to connect business owners with productivity services and remote talent resources, and introduced an SME credit card with built-in cybersecurity protections to help small businesses defend against growing digital threats.


Photo by Pavel Danilyuk

Ripple Payments Now Handles More of the Payments Lifecycle

Ripple Payments Now Handles More of the Payments Lifecycle

Digital asset company Ripple is expanding its digital payments platform, Ripple Payments, to create a single, end-to-end platform that consolidates the payments stack.

The California-based company aims to speed up settlement and reduce friction with a full payments infrastructure platform that allows fintechs to operate in the onchain economy by supporting payments made on both fiat and onchain rails. Using the new platform, organizations can collect money, hold it, convert it from fiat to stablecoin and back, manage liquidity, and pay it out.

Bringing all of these capabilities into a single place allows fintechs to manage their entire payments operation. Instead of using one provider for wallets, another for custody, another for FX, and another for payouts, fintechs can now do all of this through Ripple Payments.

Prompting this change are two acquisitions made in 2025. In November of last year, Ripple acquired digital asset custody company Palisade for an undisclosed amount. In August, the company purchased stablecoin-powered global payments platform Rail for $200 million. The added capabilities offer the ability to provision named virtual accounts and wallets, automate collection flows, and exchange and settle funds into operational accounts. Overall, Ripple Payments has processed more than $100 billion in total volume, with Rail adding another $10 billion annually.

“For the global financial system to evolve, fintechs and financial institutions need infrastructure that treats digital assets with the same rigor as traditional finance,” said Ripple President Monica Long. “Success in this space requires enterprise-grade infrastructure, extensive licensing, and deep liquidity—capabilities few can match. Ripple has built the blueprint for blockchain-based enterprise solutions designed to operate at global scale for regulated finance.”

By adding these new capabilities, Ripple can now handle the entire payment lifecycle. The company is positioning itself as more of a regulated global payments infrastructure provider that supports both fiat and stablecoins instead of simply a crypto rails provider. This new role places Ripple in competition with traditional cross-border payment processors and infrastructure vendors such as SWIFT, Visa Direct, Mastercard Cross-Border Services, and large correspondent banking networks, as well as fintech infrastructure players like Stripe, Adyen, and Airwallex.

By combining custody, liquidity management, FX, and payout orchestration into a single platform that supports both fiat and stablecoins, Ripple is positioning itself as a direct challenger to well-established incumbents.

Founded under the name OpenCoin in 2012, Ripple debuted at FinovateSpring the following year. The company provides blockchain-based solutions across traditional and digital finance. Its solutions span global payments, custody, liquidity, prime brokerage, and treasury management tools for banks, fintechs, payment service providers, and crypto businesses.

Ripple offers a stablecoin, RLUSD, that is designed to be used for settlement, liquidity management, and digital dollar transactions within its platform. RLUSD has surpassed $1 billion in market cap since launching in December 2024. Ripple’s cryptocurrency, XRP, is often used as a bridge asset to move value between currencies in cross-border payments.


Photo by Dan Cristian Pădureț

Finovate Celebrates Black and African-American History Month

Finovate Celebrates Black and African-American History Month

February is Black and African-American History Month. As the month draws to a close, we wanted to take a moment to recognize and celebrate the Black and African-American executives, founders, and analysts who have shared their ideas, insights, and experiences with Finovate audiences in 2025.

From the keynote podium to the demo stage, these Black and African-American fintech, banking, and financial services professionals are a reflection of the growing diversity and inclusion that continues to shape and transform our industry today.


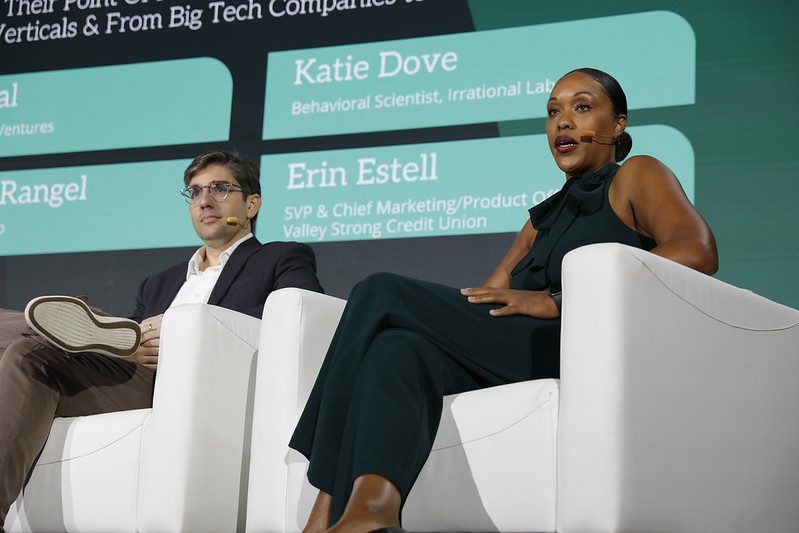
Erin Estelle—SVP, Chief Marketing Officer—Valley Strong Credit Union

Estelle participated in FinovateSpring 2025, sharing her insights as part of our Power Panel on the Customer Experience Revolution.

Estelle brings more than 15 years of experience in strategic marketing and brand management, leveraging innovative data-driven strategies to drive growth, engagement, and retention. At Valley Strong Credit Union, Estelle oversees digital marketing, consumer insights, communications, public relations, field marketing, and community outreach.

Based in Bakersfield, California, Valley Strong Credit Union offers checking and savings accounts, credit cards, personal and auto loans, mortgage and home loans, investing and retirement services, and more to 35,000+ members.


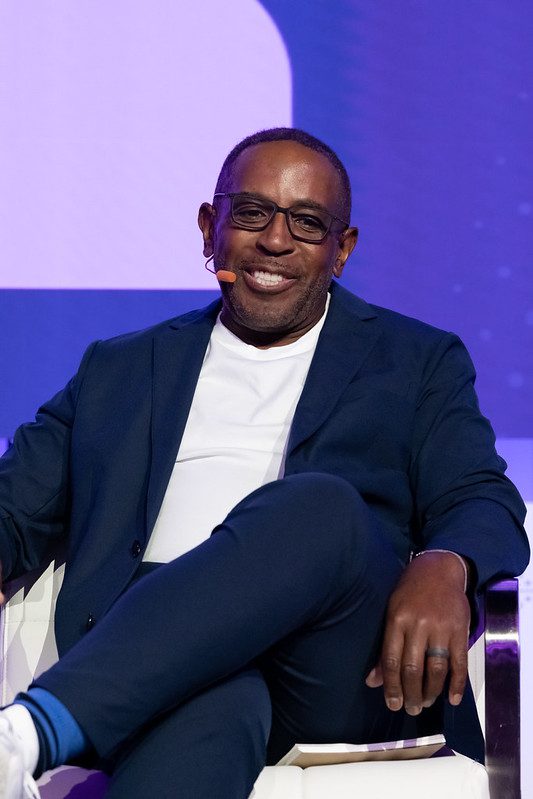
Nate Gibbons—Chief Experience Officer—QuickFi

Gibbons co-led the live demonstration of QuickFi’s self-service, embedded finance platform for business equipment financing at FinovateSpring 2025 in San Diego. The demo showed how QuickFi can enable borrowers to quickly complete onboarding, authentication, credit underwriting, and document signing on a highly secure lending platform.

A regular conference speaker and strategist as well as Chief Experience Officer at QuickFi, Gibbons was previously an executive with First American Equipment Finance. He has an MBA from the Simon Business School at the University of Rochester, and earned the Blue Ladder Award for extraordinary achievement from the City National Bank.

A Finovate alum since 2021, QuickFi has won Best of Show on three separate occasions, most recently at FinovateSpring 2024. The company offers an embedded finance platform for secured commercial equipment financing, enabling business borrowers to initiate and complete equipment financing in minutes.


Deola Habeeb—Head of Global Tech Operations—Vanguard

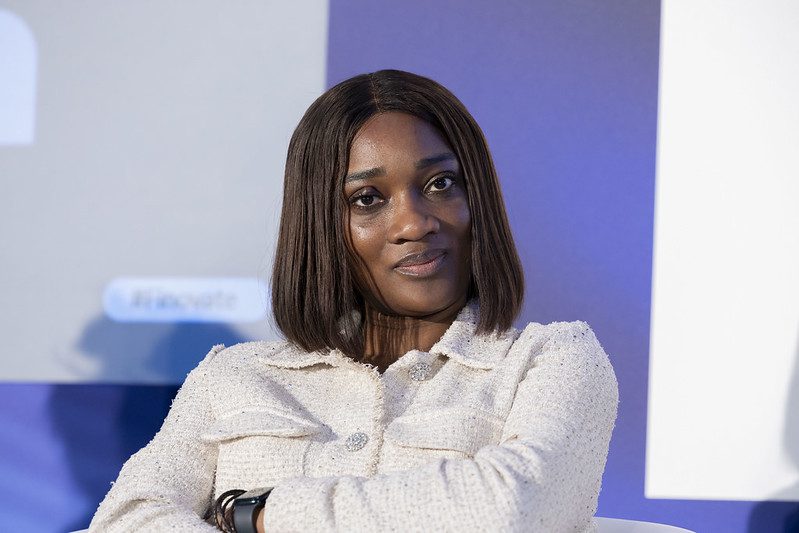
Habeeb joined Finovate at FinovateEurope 2025 to share her thoughts and experiences as part of our Women in Fintech panel.

Head of Global Tech Operations for Vanguard, Habeeb is a technology leader, entrepreneur, investor, and strategist with more than two decades of experience building enterprise operations and driving business growth. Habeeb combines technical acumen and business acuity across professional services, engineering, and business operations.

Vanguard is one of the largest investment management companies in the world. The firm offers investments, advice, and retirement services to tens of millions of individual investors directly, through workplace programs, and via financial intermediaries.


Christopher Hollins—Head of Global Product Sales and Delivery—SVB, a Division of First Citizens Bank

Hollins most recently spoke at FinovateSpring 2025 as part of our Power Panel on balancing the balance sheet and winning the battle for deposits.

Head of Global Product Sales and Delivery at SVB, a division of First Citizens Bank, Hollins is instrumental in transforming the platform’s solution delivery model to ensure that SVB’s Commercial Bank innovation economy clients can access the best partners and solutions to solve their business challenges.

Based in Santa Clara, California, SVB provides commercial and private banking services to founders, entrepreneurs, and companies in the technology, life science, private equity, venture capital, and related industries. The bank specializes in serving the unique needs of clients in dynamic, transformative businesses, providing deep sector expertise, insights, and connections.


Priscilla O-Iyari—Regional Marketing and Communications Outreach Officer—FACE Coalition

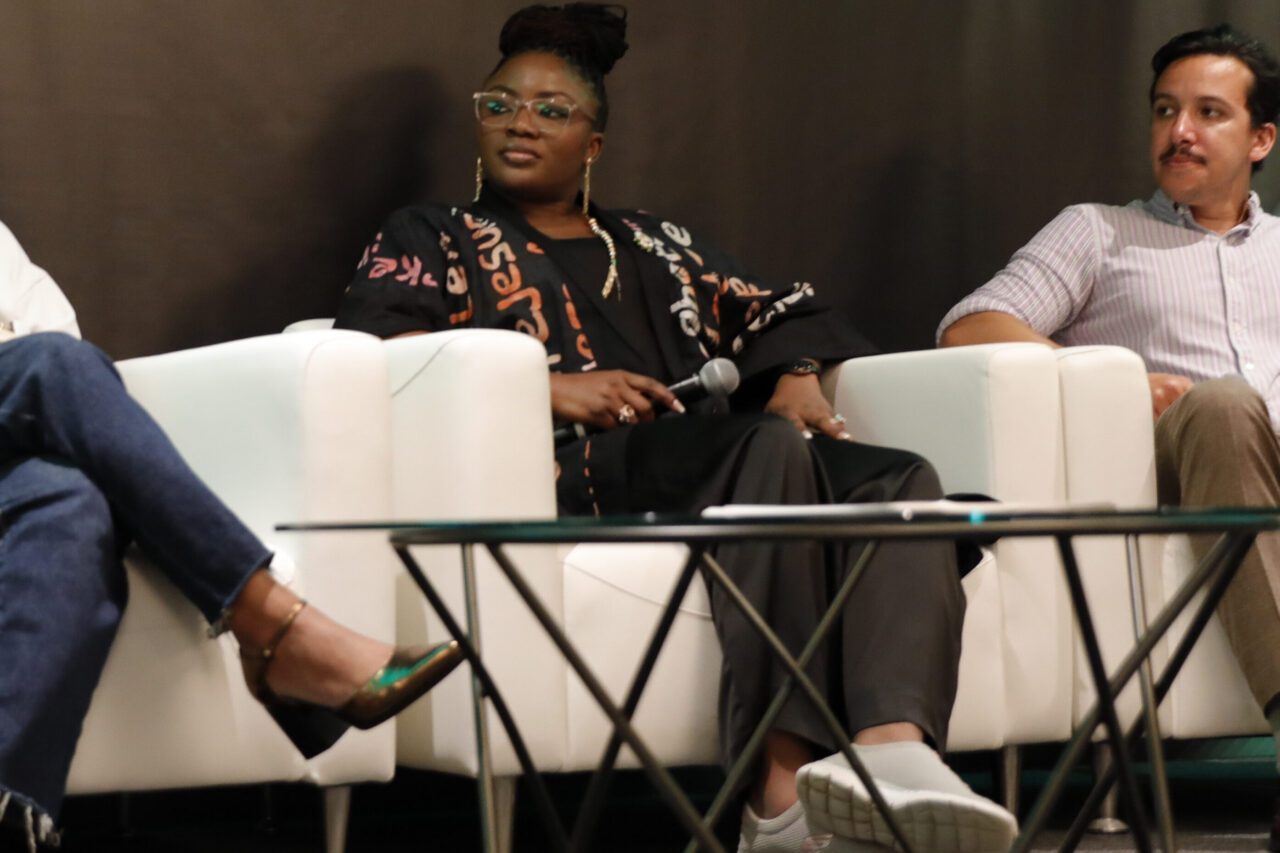
O-Iyari, in her recent capacity with FACE Coalition, joined FinovateSpring 2025 as part of our Executive Briefing on Financial Inclusion: “How can banks capture the huge growth opportunity offered by this new customer base?”

With more than 14 years of experience developing and executing strategies that have built successful brands in industries ranging from financial services to healthcare, O-Iyari came to Finovate via her role at FACE Coalition where she connected Black entrepreneurs with funding sources, human resources, and other support to help them scale their businesses and facilitate generational wealth creation.

O-Iyari is currently Associate Marketing Manager with TD where she is responsible for global brand management, education, and governance for the TD enterprise across countries and lines of business.


Mary Joseph—Senior Vice President, Strategic Investments, Treasury & Trade Solutions—Citi

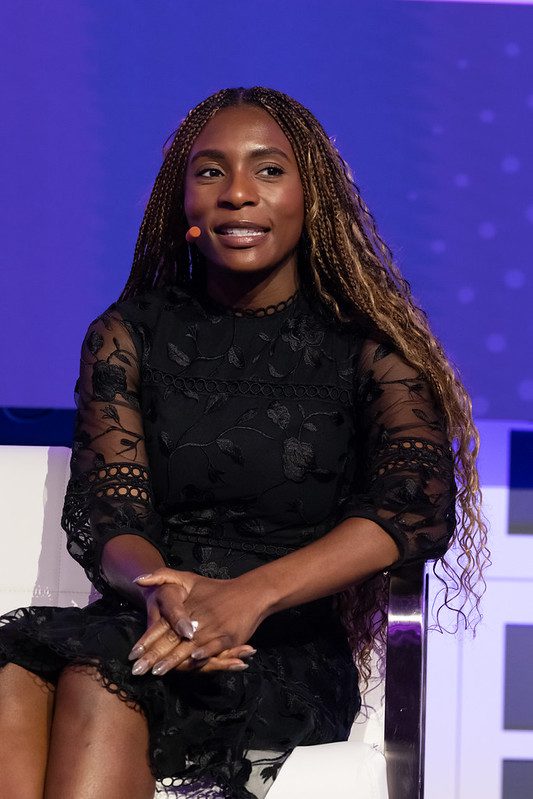
Joseph participated in our Investor All Stars panel at FinovateFall 2025, discussing the current outlook for the market, valuations, and the future of financial services.

Focusing on opportunities that enhance Treasury and Trade Solutions and expand Citi’s technology ecosystem, Joseph leads the bank’s global investments in fintech and B2B SaaS startups. She brings expertise from her tenure in fintech and M&A advisory from within Citi’s Investment Banking group and as an investor at venture capital firm, GreenHouse Capital.

Citi provides financial services that enable growth and economic progress, safeguarding assets, lending money, making payments, and ensuring access to the capital markets. The institution does business in more than 180 countries and jurisdictions, serving corporations, governments, investors, institutions, and individuals.


Tobiloba Oyetoke—Chief Executive Officer—Bitpowr Technologies

Oyetoke introduced his company, Bitpowr Technologies, to Finovate audiences a year ago as part of FinovateEurope 2025 in London.

Founded in 2021 and headquartered in Delaware, Bitpowr Technologies helps businesses and developers manage digital asset operations and build financial products. The company provides modular, critical infrastructure to issue digital wallets and process global payments safely and securely, while meeting regulatory requirements.

At the conference, Oyetoke demonstrated Bitpowr’s latest solution, Powr Finance, which enables fintechs and companies to offer embedded stablecoin banking, payments, digital wallets, and card products in a safe and compliant way.


Photo by Monstera Production

Sumsub Partners with Fireblocks to Ensure Travel Rule Compliance

Sumsub Partners with Fireblocks to Ensure Travel Rule Compliance

Compliance and fraud prevention platform Sumsub has teamed up with digital asset infrastructure solutions provider Fireblocks to provide Travel Rule compliance.

The Travel Rule is a regulation mandated by the Financial Action Task Force (FATF) designed to fight money laundering and terrorist financing. The rule requires financial institutions and Virtual Asset Service Providers (VASPs) to share specific information about the sender and receiver of funds during certain transactions. Enacted to defend traditional financial transactions from money laundering and terrorist financing, the rule has been extended to cover cryptocurrencies and digital assets.

Courtesy of the partnership, Sumsub’s Travel Rule solution will be natively integrated into the Fireblocks platform. This will provide both financial institutions and VASPs with real-time, automated, and dynamic verification for virtual asset transactions. Fireblocks users will benefit from complete control over compliance workflows, enabling them to customize these workflows to fit their preferred risk profiles. The integration features automated and encrypted Travel Rule data exchange between VASPs, supporting faster and more secure stablecoin payments.

“We’re excited to partner with Fireblocks to bring native Travel Rule compliance directly into one of the world’s leading digital asset infrastructure platforms,” the company noted on its X page. “Together we’re setting a new standard for Travel Rule compliance—secure, automated, and designed for scale—helping businesses power faster, safer, and fully compliant stablecoin payments.”

The Sumsub/Fireblocks partnership comes at a time of increased interest in stablecoins, with stablecoin volumes nearing $1 trillion per month in 2025, twice the levels of the previous year. The rise of stablecoins has put pressure on the fragmented settlement rails and compliance workflows of VASPs and other financial institutions. Further, evolving regulations—from MiCA in the European Union to the latest moves from the FATF—are driving firms to improve their ability to manage financial risks associated with virtual assets, including both implementation and operationalization of the Travel Rule.

“As digital asset payments and stablecoin adoption accelerate, our customers need compliance solutions that are robust and operationally seamless,” Fireblocks SVP of Corporate Development & Partnerships Adam Levine said. “By integrating Sumsub’s Travel Rule solution directly into the Fireblocks platform, we’re giving institutions the flexibility to meet global regulatory requirements while maintaining efficient, streamlined transaction workflows.”

Per the partnership, Fireblocks will remain the hub for transaction processing. Sumsub will provide secure, real-time Travel Rule data exchange to enrich the transaction workflow, facilitating access to 1,800+ VASPs across top protocols including GTR, CODE, Sygna, the Sumsub protocol, and more. The data sharing between counterparties in virtual asset transfers is fully embedded in the Fireblocks platform to ensure scalable, friction-free compliance.

New York-based Fireblocks is a digital asset infrastructure company that helps organizations build, manage, and scale their businesses on the blockchain. The company streamlines stablecoin payments, settlement, custody, tokenization, and trading operations across a large ecosystem of banks, payment providers, stablecoin issuers, exchanges, and custodians. Fireblocks counts 2,200 organizations among its customers including Finovate alums like Worldpay and Revolut. The company secures more than $10 trillion in digital asset transactions across 100 blockchains.

Founded in 2015 and headquartered in London, Sumsub (“Sum & Substance”) made its Finovate debut at FinovateEurope 2020 in Berlin, Germany. At the conference, the company demonstrated its all-in-one technical and legal solution to help firms meet KYC/KYB/AML requirements. The company’s technology helps accelerate verification, reduce costs, and detect fraud, and is used by more than 4,000 companies around the world. Andrew Sever is company Co-Founder and CEO.


Photo by Pixabay

Fiserv Brings BNPL Capabilities to Debit Cards with Affirm

Fiserv Brings BNPL Capabilities to Debit Cards with Affirm
  • Fiserv and Affirm are bringing BNPL to debit cards, enabling banks and credit unions to offer pay-over-time capabilities through existing debit programs without building new lending infrastructure.
  • Offering BNPL with bank-issued debit cards shifts installment lending from the merchant checkout to bank-owned channels, allowing financial institutions to retain customer relationships, data, and engagement within their own apps and card programs.
  • The model positions banks as the primary gateway for flexible payments, placing BNPL distribution within core payments infrastructure.

Core banking platform and payments player Fiserv is bringing buy now, pay later (BNPL) capabilities to its debit cards.

The Wisconsin-based company is collaborating with Affirm to bring pay-over-time capabilities to its debit card programs, empowering Fiserv clients, including community banks and credit unions, to offer their end customers flexible payment options without having to build new lending products.

According to Fiserv, the move is designed to help smaller financial institutions compete more effectively while keeping customer relationships anchored to their own debit products. “Community and regional banks and credit unions want to meet evolving consumer expectations around greater flexibility in how they pay for purchases all the while building a strong relationship with their primary financial institution,” said Fiserv Head of Card Services Erik Wichita. “This partnership gives our clients a practical, scalable way to offer such payment flexibility through their existing debit products—helping them compete effectively, deepen customer and member relationships, and drive top-of-wallet engagement with their products.”

Today’s announcement comes four years after Affirm and Fiserv first teamed up, integrating Affirm’s Adaptive Checkout to Fiserv’s Carat global commerce hub. The move allowed merchants using Carat to offer BNPL to their shoppers.

Adding pay-over-time capabilities to debit cards instead of just offering the option at the point-of-sale moves the payment from a merchant-led experience to a bank-centric one. Instead of being offered only at checkout with participating retailers, debit-based BNPL allows shoppers to access installment payments across a wider range of purchases and merchants, using their preferred payment card. For banks and credit unions, this model retains the customer relationship, data, and engagement within their own debit programs and mobile apps.

Affirm, for its part, sees the partnership as a way to bring pay-over-time options directly into the primary banking relationship, rather than positioning BNPL as a standalone checkout experience. “Millions of consumers depend on their local financial institutions, including for their top-of-wallet debit cards,” said Affirm CRO Wayne Pommen. “By partnering with Fiserv, we’re helping these institutions offer transparent pay-over-time options so customers can get the flexibility they need from the banks and credit unions they already depend on, rather than having to look elsewhere. We’re excited to enable this co-branded offering for Fiserv’s partners, allowing them to natively offer Affirm’s flexible payments through their existing debit cards.”

Fiserv and Affirm are aiming to make an easy transition for banks by managing all of the technical aspects, including real-time underwriting, loan origination, and funding. As a further benefit, consumers can use Affirm anywhere their debit cards are accepted. Additionally, Affirm’s 420,000 merchant partners give cardholders access to custom financing offers.

The companies are enabling banks and credit unions to participate in BNPL economics without giving up customer ownership to third-party point-of-sale providers. This could reshape how flexible payments are delivered and position banks as the primary gateway for installment lending.

Fiserv has been involved in the payments space since it was founded in 1984. The company serves merchants, banks, and fintechs with payments tools, customer analytics, and fraud prevention technology. Fiserv is publicly listed on the NYSE under the ticker FI and has a market capitalization of $35.39 billion.


Photo by Marek Piwnicki

Jet Bank and Backbase to Launch Albania’s First Digital-Only Bank

Jet Bank and Backbase to Launch Albania’s First Digital-Only Bank

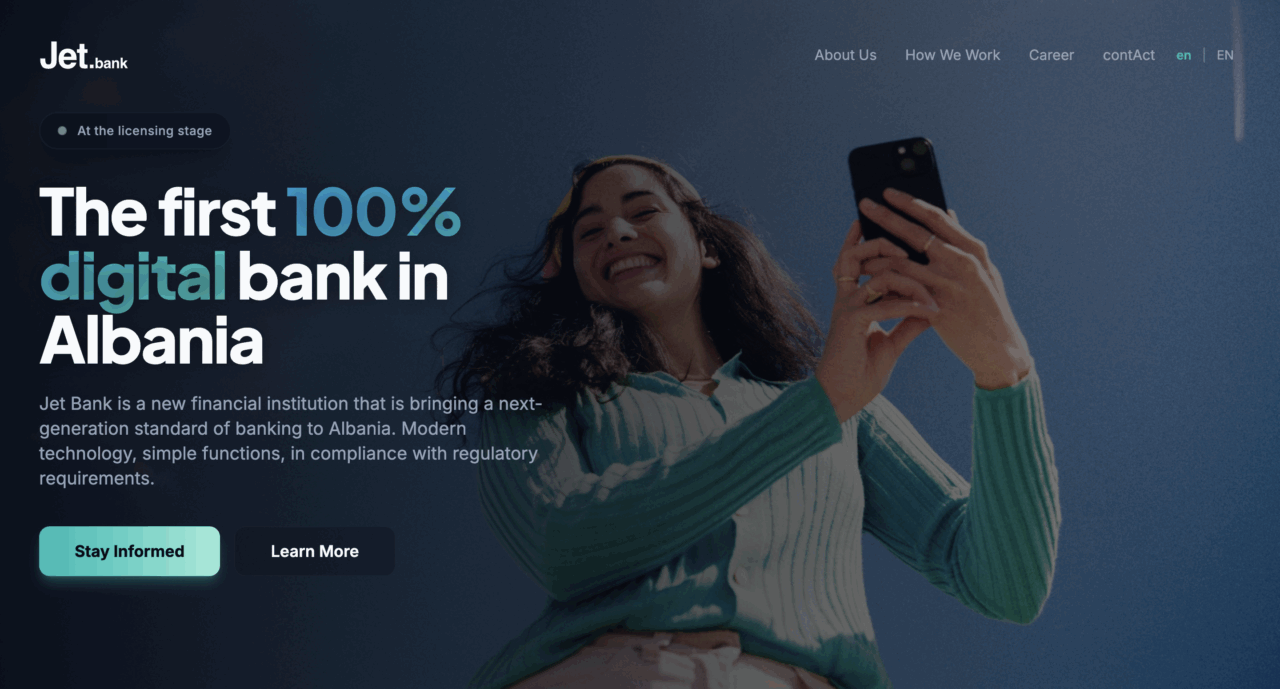
A strategic partnership between Jet Bank and banking platform Backbase will power the launch of Albania’s first digital-only bank. A greenfield digital bank able to leverage modern, enabling technologies, Jet Bank chose Backbase to serve as its digital engagement layer, orchestrating customer interactions across channels while integrating with core banking, card processing, and third-party services.

“Our ambition is to set a new standard for digital banking in Albania by building a bank that feels intuitive, reliable, and relevant in everyday use,” Jet Bank CEO Fatbardha Rino said. “This partnership with Backbase gives us the digital foundation to launch quickly while maintaining the trust and discipline expected from a licensed bank. We’re not just launching an app—we’re building a platform that can continuously evolve with our customers.”

So far, the collaboration between Backbase and Jet Bank has enabled the institution to transition from setup to User Acceptance Testing in three months, and gain full operational capability as a licensed digital bank within six months. The platform also supports monthly product releases, enabling Jet Bank to launch new products and services based on actual customer demand while ensuring uninterrupted customer journeys.

The solution provides end-to-end banking capabilities ranging from customer onboarding and lending to wealth management and intelligent assistance—all orchestrated via a single unified experience. Additionally, Jet Bank noted that Backbase’s marketplace-driven approach was a major reason why the institution sought out the collaboration. Specifically, the bank pointed to the ability to quickly launch new products and third-party services within a consistent digital experience, a critical capability for a digital bank.

“Jet Bank represents the future of digital banking—fast to market, built for continuous innovation, and designed around customer needs from day one,” Backbase Regional Vice President Robert Mihaljek said. “Their strategic choice to partner with a single, unified platform rather than assembling disconnected channels demonstrates the discipline required to build a truly scalable digital bank. We’re proud to support their vision and help them bring world-class digital banking to Albania.”

A Finovate alum since 2009, Backbase is a four-time Finovate Best of Show award winner, most recently securing top honors at FinovateEurope 2018. Founded in 2003 and headquartered in Amsterdam, Backbase offers an AI-powered banking platform that unifies all servicing and sales journeys into an integrated suite. Backbase’s technology enables banks to modernize operations across retail, SME, commercial, and private banking, as well as wealth management. More than 150 financial institutions around the world use Backbase’s solutions and services.

This week’s collaboration is not the first between Backbase and an Albanian bank. Last spring, Backbase announced that Albania’s Tirana Bank would deploy Backbase’s Engagement Banking Platform to power its digital transformation. The five-year strategic partnership will enhance Tirana Bank’s suite of solutions including new capabilities for web and mobile banking, digital lending, and other services.

Founded in 1996 as the first bank in Albania launched entirely with private capital, Tirana Bank surpassed total assets of €1.5 billion ($1.6 billion) in 2024. The institution is located in Tirana, Albania’s capital city with an estimated 542,730 residents—more than 800,000 in the greater metropolitan area.


Photo by Mario Beqollari on Unsplash

Nationwide Selects Moneyhub for Consumer Spending Insights

Nationwide Selects Moneyhub for Consumer Spending Insights
  • Nationwide has selected Moneyhub to enrich and categorize card and direct debit transaction data using AI-driven analysis.
  • The partnership enables deeper transaction-level insights that support better personal finance management for customers, alongside improved fraud detection, risk monitoring, and personalization for Nationwide.
  • The deal highlights how transaction data is becoming a strategic differentiator for banks competing on insight-led products and customer experience.

UK financial services company Nationwide has selected open data platform Moneyhub to help categorize, enrich, and better understand consumer transaction data.

Nationwide will leverage Moneyhub’s AI-driven Categorization and Enrichment engine to analyze consumer transactions made on cards and with direct debits. The transaction analysis will allow Nationwide to see details such as contact and location data for the website or store where the purchase was made.

This deep understanding of transaction details will benefit both customers as well as Nationwide. The additional data will help customers better manage their personal finances and quickly identify fraudulent transactions. For Nationwide, the granular insights support more accurate transaction categorization, improved risk detection, and the ability to deliver more personalized products and services. By working with Moneyhub, Nationwide is positioning itself to turn raw transaction data into actionable insights that can power smarter products, clearer customer experiences, and more proactive financial support.

“At Nationwide our tech teams work to deliver fairer, more rewarding, and more convenient banking, so selecting the right partners is crucial, to make sure we’re giving our customers the best experience possible,” said Nationwide Chief Data and Analytics Officer Sri Kanisapakkam. “Moneyhub’s AI-driven tech will help enrich the data we’re giving back to our customers and set us up for success with even more personalized products and services in the future.”

Moneyhub was founded in 2014 and offers personal finance technology tools, open data APIs, decisioning solutions, and payments capabilities. Its platform is designed to empower financial institutions, employers, and technology providers to deliver more tailored financial experiences through real-time data access and intelligent analysis. Regulated by the FCA, Moneyhub’s infrastructure supports a wide range of use cases, including budgeting tools, affordability assessments, wealth insights, and financial wellness programs.

“Moneyhub exists to help our financial services clients build services that improve their customers’ digital experience and deliver better financial outcomes,” said Moneyhub CEO Alastair McGill. “Presenting retail customers with a fine-grained understanding of their income and expenditure is an essential part of this journey, so we’re delighted that Nationwide selected our Categorization and Enrichment engine. We look forward to working with Nationwide as they continue to further enhance their customer engagement.”

Across the globe, transaction data is becoming a strategic asset for banks. As competition heats up in the traditional banking space, financial institutions face growing pressure to improve personalization, fraud prevention, and customer trust. Fortunately, the broad availability of AI tools combined with open banking regulations such as PSD2 make it easier than ever for firms to gain insights from transactions.

Moneyhub demoed its enterprise platform at FinovateEurope 2017. Last year, the company formed a partnership with Lloyds, deepened ties with Experian, and appointed a new CEO.


Photo by Xi Qiao

Cobalt Credit Union Teams Up with Eltropy to Deploy AI Voice

Cobalt Credit Union Teams Up with Eltropy to Deploy AI Voice

Eltropy, an AI-powered conversations platform for community financial institutions (CFIs), announced this week that Nebraska-based Cobalt Credit Union has deployed its Eltropy AI Voice solution. This has enabled the credit union to secure an 83% session containment rate while maintaining high member satisfaction.

Session containment rates refer to the percentage of customer interactions that are successfully resolved by the AI without the participation of a human agent. Typically, these rates range between 60% and 80%, and are lower than those for text-based systems due to the greater complexity of voice-based AI systems and the nuances of natural language processing (NLP) in spoken conversations. For Cobalt to achieve session containment rates exceeding 80% with its voice-based system is a significant achievement.

“From day one, our AI-powered contact center assistant, Coby, has delivered measurable results and positive feedback from both members and staff,” Cobalt Credit Union VP of Digital Banking Chasmine McIntosh said. “What Coby does is handle routine inquiries 24/7, which frees up our team to focus on the complex situations where members really need that human touch. We consider him a vital member of our contact center team, handling high volume with empathy and accuracy.”

Formerly SAC Federal Credit Union, Cobalt CU is no stranger to AI-enabled technology. The institution implemented its first AI agent in August 2024: an intent-based system that ran alongside the credit union’s new digital banking platform. Before the end of the year, Cobalt CU had added generative AI capabilities to enable its contact center assistant, Coby, to respond to an even broader range of queries. The implementation of AI Voice represents the completion of Cobalt CU’s multi-channel AI strategy, enabling members to engage with the institution via the channel of their choice.

“The key to effective AI Voice is that it goes beyond just understanding member requests—it takes action,” Eltropy VP of Product, AI, Saahil Kamath said. “Members calling to check balances or transfer funds don’t want to work through phone menus and hold times. Our AI handles authentication conversationally, processes transactions in real-time, and provides confirmation—maintaining a natural, human-like interaction throughout. Cobalt members are experiencing this firsthand.”

Founded in 1946 as SAC Federal Credit Union, the institution rebranded as Cobalt Credit Union in 2018. Cobalt CU is headquartered in Papillion, Nebraska—part of the Omaha metropolitan area—and has more than 20 branches serving approximately 120,000 members throughout Nebraska and Iowa. The credit union has $1.3 billion in assets under management. Robin Larsen is President and CEO.

A Finovate alum since 2017, Eltropy most recently demoed its technology at FinovateFall 2022 in New York. Headquartered in Santa Clara, California, Eltropy offers a unified conversations platform that enables more than 700 credit unions and community banks to transform the member and customer experience. With more than 40 use cases ranging from straightforward 1:1 texting and video banking to appointment and lobby management, Eltropy integrates AI at every step to automate processes and streamline complexity. Financial institutions using Eltropy’s technology have seen reductions in delinquency and fraud rates, as well as up to a 20% acceleration in lending processes.


Photo by John Matychuk on Unsplash

Coinbase Bridges TradFi, DeFi Gap; Empowers Retail, Institutional Clients

Coinbase Bridges TradFi, DeFi Gap; Empowers Retail, Institutional Clients

As interest in digital assets and decentralized finance grows among both retail and institutional users, offering a platform that caters to both communities is a major point of differentiation for companies in the DeFi space. Further, companies that provide services that bridge the gap between traditional finance (TradFi) and decentralized finance will be best positioned to serve those retail and institutional users who increasingly need to efficiently manage both traditional and digital assets.

This context helps understand two recent announcements from digital asset platform Coinbase. First, this week, the company announced that it had selected Chainlink CCIP as the exclusive bridging solution for its Coinbase Wrapped Assets. “We chose Chainlink because they are an industry leader for cross-chain connectivity,” Coinbase Senior Director, Product Management, Josh Leavitt said. “Their infrastructure provides a reliable means to expand Coinbase Wrapped Asset offerings.”

A leading oracle platform, Chainlink connects blockchain-based smart contracts with real-world, external data, events, and systems. Integrated with numerous blockchains—including Ethereum, Binance Smart Chain, Avalanche, and more—Chainlink powers thousands of decentralized applications and protocols across DeFi, NFT, and enterprise use cases. The company’s CCIP leverages the same decentralized oracle networks that secure more than 70% of DeFi around the world, and has enabled more than $27 trillion in transaction volume.

Coinbase Wrapped Assets are tokenized versions of cryptocurrencies issued and managed by Coinbase. A 1:1 equivalent of the underlying digital asset, Coinbase Wrapped Assets are built to operate on a blockchain other than its native blockchain. For example, a Coinbase Wrapped Bitcoin can be used on a blockchain, such as Ethereum, that does not natively support Bitcoin.

Coinbase Wrapped Assets include cbBTC, cbETH, cbDOGE, cbLTC, cbADA, and cbXRP. Combined, they have a market capitalization of $7 billion. In partnering with Chainlink, Coinbase will use Chainlink CCIP to provide a foundation for bridging Coinbase Wrapped Assets across and beyond ecosystems.

“CCIP was selected by Coinbase for their cross-chain needs due to CCIP’s security and reliability,” Chainlink Head of Strategic Initiatives William Reilly said. “As the leading publicly-listed firm for digital assets, Coinbase takes security and reliability for their products seriously. I am excited about accelerating the growth of Coinbase’s wrapped assets and look forward to helping bring global finance onchain.”

Coinbase’s partnership announcement with Chainlink comes just days after the company reported that it was expanding its institutional collaboration on digital assets with international banking group Standard Chartered. “By leveraging Standard Chartered’s global banking expertise and Coinbase’s leadership in the digital asset space, we are creating a secure and seamless framework for institutions to access and manage digital assets with confidence,” Coinbase Institutional Co-CEO Brett Tejpaul said. “Together, we are driving the evolution of the financial ecosystem and enabling institutions to unlock new opportunities in this rapidly growing market.”

The partnership builds on an existing relationship between the two firms in which Standard Chartered provides banking connectivity to facilitate real-time SGD transfers for Coinbase customers. Standard Chartered has a reputation as a “pro-crypto” financial institution that was among the first major global banks to offer deliverable crypto trading for institutional clients. In addition to its collaboration with Coinbase, the bank has also partnered with crypto platform Crypto.com to enable users in 90+ countries to deposit and withdraw in major currencies through Crypto.com’s app.

Founded in 2012, Coinbase made its Finovate debut at FinovateSpring 2014. Today, the company has $516 billion in assets on its platform and facilitates $295 billion in quarterly trading volume. Co-Founder Brian Armstrong is Chief Executive Officer.

Coinbase also recently published its State of Crypto Q4 2025 report: “Younger investors are rewriting the investing playbook.” The cross-generational report surveyed 4,350 US adults, including 2,005 with investment accounts, on their thoughts about the financial markets and what role digital assets played in their own investing strategies.


Photo by Tim Umphreys on Unsplash

eToro Brings Stock Lending to the UK

eToro Brings Stock Lending to the UK

Social trading and investment network eToro unveiled that it will begin rolling out its stock lending program in the UK. The capability, which is available in Europe and the UK, enables eligible users to lend out their stocks.

Stock lending isn’t new. In fact, it has long been a passive revenue generator for large brokers and hedge funds. Bringing this capability to an alternative platform like eToro gives the fintech a competitive edge as it brings more transparent, value-added services to the retail trading market. As investor expectations increase, platforms that provide passive-income engines, improved liquidity, and greater control over their portfolios may gain more interest in an ever-crowded market.

Facilitating the launch are global financial services company BNY and stock lending program EquiLend. Under these partnerships, BNY is acting as custodian and clearing provider, while EquiLend identifies borrowers and facilitates the lending process. eToro anticipates that the new program will allow its investors to put their portfolios to work while retaining their investments.

As with most stock lending programs, borrowers post collateral, and investors can still sell their positions at any time. By partnering with institutions such as BNY and EquiLend, eToro aims to ensure operational safeguards that offer retail users institutional-grade risk management.

“Launching stock lending in the UK is a key step in our mission to make passive income opportunities available to every investor,” said eToro VP of Execution Services Yossi Brandes. “With the ability to lend not just US but also global stocks, we are maximizing the potential for our clients to generate additional revenues, and this rollout sets the stage for further expansion into new markets.” 

Launching in the UK expands eToro’s partnership with BNY, which it leverages for clearing and custody services for its stock and ETF offering across 19 global exchanges.

“We are delighted to extend our relationship with eToro, delivering an integrated solution encompassing clearing, settlement, custody, foreign exchange and cash management to UK investors,” said BNY Executive Platform Owner of Global Clearing Victor O’Laughlen. “By combining the capabilities of eToro and EquiLend with the scale and deep expertise of BNY’s leading Global Clearing platform, this initiative aims to equip retail investors with an institutional-grade solution to support their investing journey.”

Israel-based eToro said that the move marks the next step in the company’s plan to expand stock lending access to retail investors worldwide.

For eToro, today’s launch is more than a feature. The expansion is a signal of the company’s strategic move into deeper monetization and institutional-grade services. Leveraging BNY’s clearing and custody infrastructure places eToro closer to the operational standards of traditional brokers while maintaining its core social-trading product. Adding features like these in partnerships with traditional financial institutions could help eToro attract more sophisticated retail investors looking for passive-income tools and greater flexibility.

Founded in 2007, eToro has since raised $693 million in funding. With more than 35 million registered users and investors on its trading and investing platform, the company offers trading and investing tools that are more accessible and collaborative. eToro launched in the US market in 2019, entering a space where Robinhood had already established a six-year presence.

eToro began 2025 with its public debut in May. The company is now listed on Nasdaq Global Select Market under the ticker ETOR. eToro has a current market capitalization of $3.5 billion.


Photo by John Angel on Unsplash

ID-Pal Acquires KYB Specialist, NorthRow

ID-Pal Acquires KYB Specialist, NorthRow

ID-Pal’s strategic acquisition of NorthRow, a specialist in compliance solutions, will enhance the Irish company’s compliance intelligence for Know Your Business (KYB), Know Your Customer (KYC), and Anti-Money Laundering (AML) operations. The move will combine ID-Pal’s AI-powered verification platform with NorthRow’s expertise in KYB and business due diligence, enabling ID-Pal to offer a single solution for ensuring one perpetual risk view for both individuals and organizations.

Terms of the transaction were not disclosed, but post-acquisition, NorthRow’s services and operations will operate without interruption under ID-Pal. The acquisition comes at a time when new regulations in the UK, and the US Corporate Transparency Act, are putting pressure on compliance teams and making strategies like continuous KYC, AML, and KYB monitoring essential features.

In a statement on the company’s website, ID-Pal Founder and CEO Colum Lyons put the acquisition in the context of his own firm’s founding. “Alongside co-founders James O’Toole and Robert O’Farrell, ID-Pal was created to support businesses with accurate identity verification built on privacy preservation,” Lyons said. “As the financial services space becomes more regulated, and with AI-driven document fraud becoming the biggest threat our industry has faced, it is essential that businesses have a unified view of the risks ahead and how to manage them. Our acquisition of NorthRow allows ID-Pal to unify this process with one comprehensive platform that defends businesses against fraud at every entry point and avoids noncompliance fines.”

The acquisition builds on ID-Pal’s identity verification tools, adding native end-to-end KYB checks to provide continuous monitoring of changes in a business’s status, structure, or directors. The deal also helps ID-Pal deliver on its goal of providing scalable, AI-powered solutions that can tackle ever-evolving compliance challenges. NorthRow’s technology will help companies adapt to regulatory changes worldwide by providing real-time data on companies, from ownership structure to financial health.

ID-Pal will also benefit from expanding its portfolio with major financial services companies such as Caxton, Equifax, and Hargreaves Lansdown. Caxton COO Alana Parsons praised the strategic acquisition for creating “a powerful platform for the future.” Parsons added, “We’re excited to start working with ID-Pal and to benefit from the innovation in KYC and KYB risk intelligence that this partnership will deliver.”

ID-Pal most recently demoed its technology at FinovateFall 2025 in New York. At the conference, the company showed how its ID-Detect solution provides an additional layer of verification designed to detect evidence of document fraud. ID-Detect is a standard feature of ID-Pal’s identity verification, helping businesses deal with the growing challenge of AI-generated fake identification cards and other documents. ID-Pal’s technology is used in more than 250 jurisdictions, covering more than 16,000 document types and accessing 400+ trusted data sources.


Photo by Caio Cardenas