FinovateFall 2026 Best of Show Winners Announced!

FinovateFall 2026 Best of Show Winners Announced!

The demos are done and the votes have been counted: congratulations to the winners of Best of Show at FinovateFall 2026!

It is true that AI continues to be the most enabling technology in fintech, bringing new capabilities to payments, fraud prevention, lending, wealth management, and more. As one demoing company representative noted from the FinovateFall stage this week, there may not have been a single demo that did not in some way acknowledge the role that AI—and increasingly agentic AI—is playing in helping banks and other financial institutions become more efficient and more effective in serving individuals, families, businesses, and communities.

That said, if there is one commonality among the companies that won Best of Show at this year’s FinovateFall, then that commonality might be a laser-focus on what matters most to financial institutions large and small: growing deposits, boosting customer and membership growth, creating new revenue opportunities, and simplifying and streamlining operations that have been historically hindered by manual processes, siloed systems, and an inability to transform data into the kind of insights that lead to better experiences for financial services customers. Viewed through this lens, AI is just the latest technology to help bridge the gap between what customers want and what financial institutions can safely, compliantly, and consistently deliver.

With one more day to go in this year’s FinovateFall conference, we want to thank all of our demoing companies, our sponsors and partners, our top-notch AV team, and—perhaps most of all—our attendees for their continued support of what we believe is still one of the most unique events on the fintech calendar.

Our next conference will be FinovateSpring 2027 in San Diego, California, at the Gaylord Pacific Resort and Conference Center, from May 3rd through the 5th. Tickets are on sale now and you can save up to $600 if you register by November 6th.


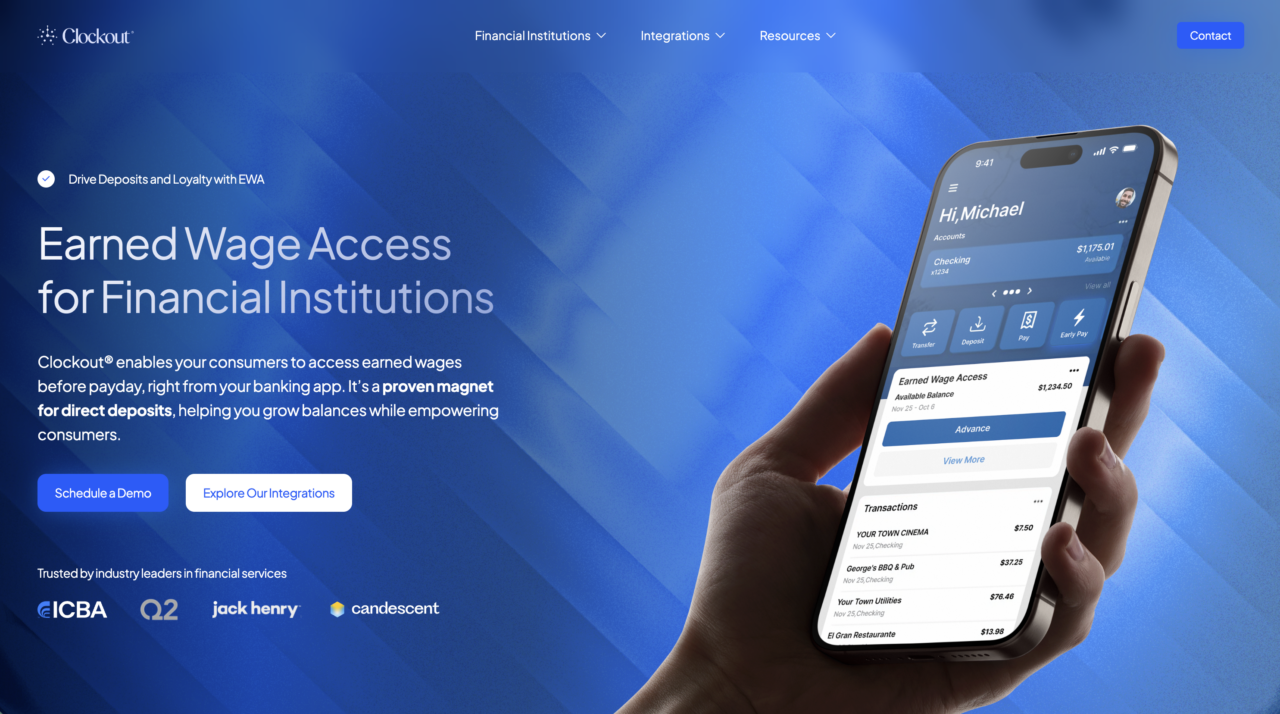
Clockout for its solution that drives member and customer growth, increases direct deposits 10%-25%, generates $16-$50 monthly per-user revenue, and creates competitive differentiation through embedded financial wellness.

equipifi for its technology that enables banks and credit unions to offer flexible payments and Buy Now, Pay Later as a native capability within their digital banking platforms.

Goodbuy for its solution that transforms local small business engagement into a new growth channel—enabling financial institutions to drive account activation, deposits, and interchange through connected community commerce.

Neural Payments for its Payments Hub that connects banks and credit unions to every major US payment rail and wallet through a single, fully branded integration.

ScreenSteps for its performance enablement platform that helps financial institutions turn complex procedures into simple, real-time guidance employees can find and follow.

Tweezr for its technology that helps organizations transform and grow by accelerating TTM and increasing developer productivity for both legacy system maintenance and modernization—or even obviating modernization all together.

Vertice AI for its OPTIMIZE solution that transforms institutional growth goals into optimized, AI-executed marketing campaigns with human approval at the strategic level.

Young Early Starters for its investing and education app that gives children real stock ownership, guided by learning and approved by parents.
Notes on methodology:
1. Only audience members NOT associated with demoing companies were eligible to vote. Finovate employees did not vote.
2. Attendees were encouraged to note their favorites during each day. At the end of the last demo, they chose their three favorites.
3. The exact written instructions given to attendees: “Please rate (the companies) on the basis of demo quality and potential impact of the innovation demoed.”
4. The eight companies appearing on the highest percentage of submitted ballots were named “Best of Show.”
5. Go here for a list of previous Best of Show winners through 2014. Best of Show winners from our 2015 through 2026 conferences are below:
FinovateEurope 2015
FinovateSpring 2015
FinovateFall 2015
FinovateEurope 2016
FinovateSpring 2016
FinovateFall 2016
FinovateAsia 2016
FinovateEurope 2017
FinovateSpring 2017
FinovateFall 2017
FinovateAsia 2017
FinovateMiddleEast 2018
FinovateEurope 2018
FinovateSpring 2018
FinovateFall 2018
FinovateAsia 2018
FinovateAfrica 2018
FinovateEurope 2019
FinovateSpring 2019
FinovateFall 2019
FinovateAsia 2019
FinovateMiddleEast 2019
FinovateEurope 2020
FinovateFall 2020
FinovateWest 2020
FinovateEurope 2021
FinovateSpring 2021
FinovateFall 2021
FinovateEurope 2022
FinovateSpring 2022
FinovateFall 2022
FinovateEurope 2023
FinovateSpring 2023
FinovateFall 2023
FinovateEurope 2024
FinovateSpring 2024
FinovateFall 2024
FinovateEurope 2025
FinovateSpring 2025
FinovateFall 2025
FinovateEurope 2026
FinovateSpring 2026

Six Fintechs Creating Smarter Lending, Credit, and Financing Tools

Six Fintechs Creating Smarter Lending, Credit, and Financing Tools

Lending has always depended on a financial institution’s ability to assess risk, make informed decisions, and deliver capital efficiently. But many of the systems supporting that process remain slow, fragmented, and heavily manual. Commercial lenders still spend days gathering documents and spreading financials, while consumers and small businesses increasingly expect faster decisions, flexible payment options, and seamless digital experiences.

The companies demoing at FinovateFall 2026, taking place on September 9 through 11 in New York, are approaching these challenges from several angles. Some are using AI to accelerate underwriting and automate operational work. Others are embedding financing and flexible payment options directly into digital banking, helping institutions identify household opportunities, or rebuilding commercial lending around borrower self-service. Together, these six companies demonstrate how smarter technology can help financial institutions improve speed, efficiency, and access to financing.


ALoan

ALoan uses AI to automate commercial underwriting and help lenders move from borrower documents to a completed credit memo in less than 30 minutes. The platform spreads financial information from tax returns, bank statements, and borrower financials, applies the lender’s credit policies, and links each figure and conclusion back to its original source. By automating document collection, financial spreading, and credit memo preparation, ALoan enables commercial lending teams to increase throughput and reach term sheets faster without adding staff or replacing existing systems.


Clockout

Clockout helps banks and credit unions embed financial wellness and liquidity tools into their customer experiences. The platform is designed to increase direct deposit relationships, generate new fee revenue, and strengthen customer engagement by providing users with more ways to manage short-term financial needs. For financial institutions seeking to deepen primary account relationships, Clockout offers a way to combine financing access with broader financial wellness.


equipifi

equipifi enables banks and credit unions to offer Buy Now, Pay Later (BNPL) and flexible payment options directly within their digital banking platforms. Its technology allows financial institutions to present personalized purchasing power and financing offers based on customer behavior and purchase intent, including through real-time mobile notifications. By bringing BNPL inside the banking relationship, equipifi helps financial institutions participate more directly at the point of sale rather than ceding that interaction to third-party providers.


OptimaFI

OptimaFI’s Household Insights platform gives community banks and credit unions a household-level view of customer accounts and performance. The platform benchmarks institutional data against more than 14 billion private peer data points and provides segment-level recommendations related to growth and risk. Because it does not require a core integration, financial institutions can begin using the platform in a matter of days to identify opportunities across deposits, lending, and broader household relationships.


QuickFi

QuickFi offers an end-to-end digital platform for commercial equipment financing that allows borrowers to self-serve from application through final payment. The company replaces manual, paper-heavy lending processes with a digital experience that can deliver financing decisions and documentation in minutes, 24 hours a day. QuickFi helps banks and equipment manufacturers serve small business borrowers more efficiently while reducing the staffing and operating costs associated with traditional commercial lending models.


Voyager AI

Voyager AI brings personalization and intelligence to complex commercial lending workflows. The platform unifies document collection, financial spreading, underwriting, compliance, and credit memo preparation while learning an institution’s specific lending policies and standards. By automating manual steps and identifying missing information earlier in the process, Voyager AI helps lenders deliver faster, more consistent experiences while allowing employees to spend more of their time on borrower relationships, structuring, and credit judgment.


Why banks should care

Speed has become a competitive advantage in lending. Borrowers are less willing to wait weeks for a credit decision when another provider can deliver an answer in hours or minutes. At the same time, banks and credit unions are under pressure to grow loan portfolios without proportionally increasing headcount or operational expense. Technologies that automate underwriting, document collection, reconciliation, and servicing can help institutions make faster decisions while preserving the judgment and oversight required for responsible lending.

The definition of lending is also expanding. Flexible payments, embedded financing, household intelligence, and digital self-service are blurring the lines between traditional loans, payments, and financial wellness. Financial institutions that treat these capabilities as part of a broader customer relationship may be better positioned to capture more borrowing activity, deepen engagement, and compete with nonbank providers. The companies demonstrating at FinovateFall 2026 show how institutions can modernize both the front-end borrower experience and the operational infrastructure that supports the lending process.


Photo by Monstera Production