4 Companies Bringing Agentic AI to Checkout

4 Companies Bringing Agentic AI to Checkout

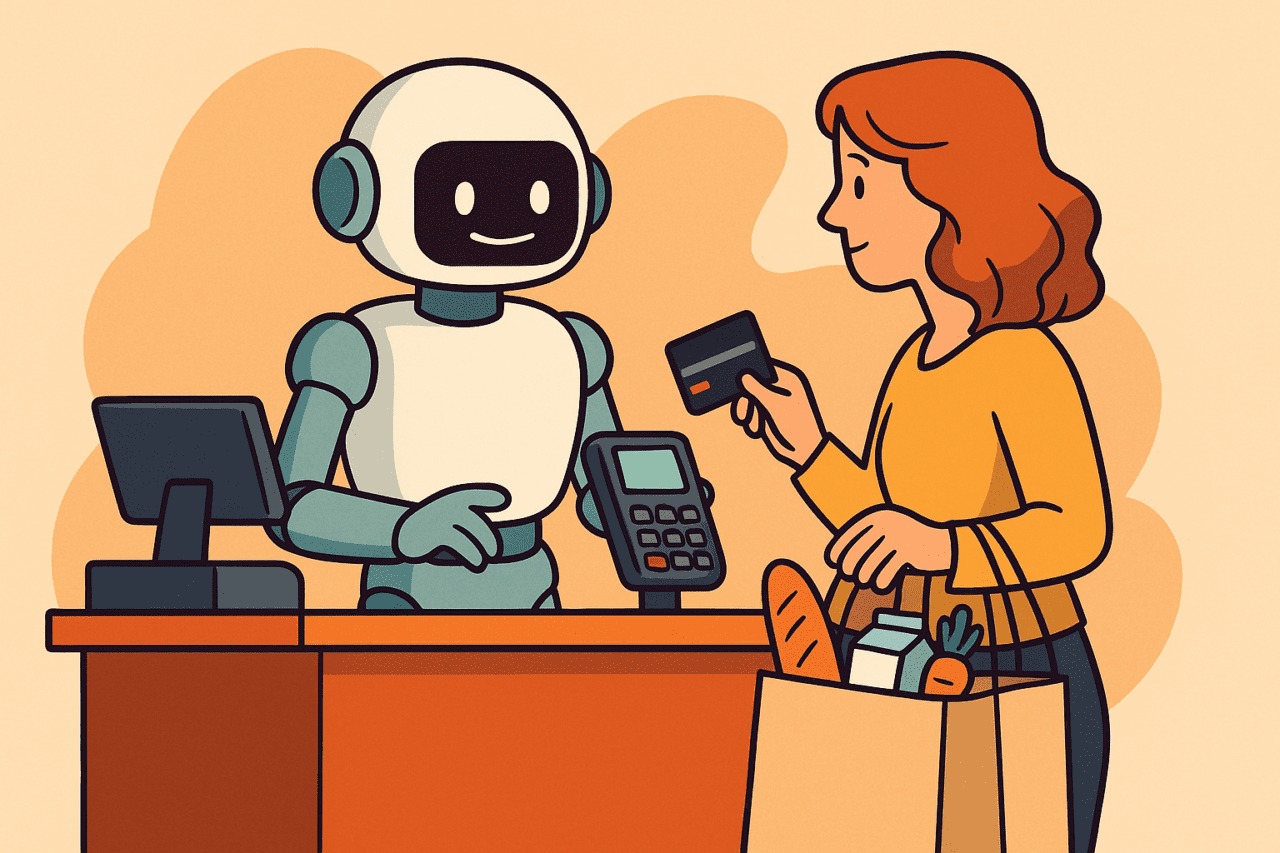
Agentic AI agents, autonomous agents that act on behalf of users with minimal input, are not just coming to financial services. They’re already here. One of the most compelling use cases for Agentic AI is at checkout, where commerce, AI, and payments converge at the point where consumers make their purchase decisions.

In the past few weeks, three Agentic AI shopping and checkout announcements from major payments and technology players have made news headlines. So far, Google, Visa, and Mastercard are leading the Agentic AI payments charge, with PayPal and Perplexity not far behind. Here’s a look at what each company is doing.

Google’s AI-powered shopping agents

Google announced its AI Shopping Mode yesterday, a new online shopping experience that allows users to browse 50 billion product listings and buy the item they want using Google’s new agentic checkout at a price that fits their budget. Shoppers set their preferences by selecting “track price” on a preferred product listing and set the right size, color, and the amount they want to spend. If the item’s price drops into the user’s pre-selected price range, they receive a push notification and can have the agentic shopping agent buy the item for them with the push of a button.

Google is embedding an AI assistant into every step of the purchasing process, from browsing to payment, and is making the checkout experience hyper-personal, with less friction.

Visa’s intelligent commerce and agentic AI

Visa unveiled its Visa Intelligent Commerce tool last month. The new initiative will empower AI agents to deliver personalized and secure shopping experiences for consumers at scale. The program will equip AI agents to seamlessly manage key phases of the shopping journey, from product discovery, to purchasing, to post-purchase product management.

Unlike Google, Visa will offer APIs and SDKs that will provide third parties a suite of payments tools, including tokenization, authentication, and transaction controls, to embed into their own apps. In this sense, Visa is not just planning to launch a new checkout tool, it is building infrastructure for a world where the AI agent is the end customer.

Mastercard’s agentic payments through Agent Pay

Mastercard announced Agent Pay, a payment framework for agent-driven commerce, 24 hours before Visa’s agentic AI announcement hit the wires. Mastercard’s tool aims to make payments smarter, more secure, and more personal by embedding them directly into the product recommendations generated by GenAI platforms.

When paired with Mastercard’s tokenization technology, Agent Pay will not only add security, but will also help retailers identify and validate customers to offer a more meaningful and consistent shopping experience. Overall, Mastercard is pioneering a payment model where AI, not the consumer, initiates the purchase.

Perplexity x PayPal

Earlier this month, GenAI-powered search engine Perplexity partnered with PayPal to enable in-chat shopping. Shoppers will be able to check out instantly with PayPal or Venmo when they ask Perplexity to find a product, book travel, or buy tickets. The entire process will be powered by PayPal’s account linking, secure tokenized wallet, and emerging passkey checkout flows, which could eliminate the need for passwords.

While it is not a formal “agentic” platform, the move shows that large language models (LLMs) are starting to transact directly and the partnership is a good example of how chat interfaces are evolving into commerce platforms. The announcement serves as a preview of agentic commerce where LLMs initiate and complete purchases in a single conversational flow.

Overall, these announcements signal a major shift in ecommerce. The online point-of-sale is moving from a consumer-initiated process to an AI-initiated transaction. At the outset, regulation, identity, fraud, and explainability will be a large challenge. Still, the shift to agentic commerce is well underway, and the companies building today’s infrastructure are setting the rules and structure for how agentic AI commerce will work in the future.
Pinpointing Regulation Amid Uncertainty

Pinpointing Regulation Amid Uncertainty

FinovateSpring wrapped up earlier this month, and one of the main discussion topics I heard repeatedly was how to proceed during an era of economic uncertainty combined with regulatory freedom. The US is taking a vastly different approach to regulation than Europe, which seems to be tightening its grip on compliance.

In the US, there are four major moves that have indicated the new administration’s stance toward regulation in banking and finance. Among the regulations that are shifting are:

The Consumer Financial Protection Bureau (CFPB)

The key rulemaking activity of the CFPB has been paused. Employees have been instructed to stop work on regulations involving overdraft fees and open banking.

Crypto enforcement actions

The Securities and Exchange Commission (SEC) and Commodity Futures Trading Commission (CFTC) have pulled back on enforcement actions in crypto, giving more clarity on stablecoin classification and providing more room for decentralized finance projects to operate.

Capital requirement rollbacks

Capital requirement rollbacks have reduced regulatory pressure on traditional banks. Key elements, like the supplementary leverage ratio and stress testing thresholds, have been softened or delayed, especially for regional banks. These rollbacks are designed to free up capital for lending and investment, but critics argue they increase risk by removing safeguards that were put in place after the 2008 financial crisis.

Basel III changes

Discussions of finalizing Basel III, which aims to require banks to maintain sufficient capital buffers and improve liquidity management, are still ongoing. However, lobbying has delayed its final implementation and resulted in a watered down version of some of its core provisions. A return to Basel II-style flexibility would prioritize bank competitiveness and profitability over strict capital adequacy.

While the current regulatory environment may give companies more room to innovate, most of the fintechs and banks I spoke with at FinovateSpring emphasized that they are still operating well within traditional regulatory boundaries, many of which are more stringent than today’s US standards. In fact, with AI now playing a major role across financial services, one compliance specialist noted that it’s increasingly common for firms to involve data scientists early in the compliance process to ensure new technologies meet regulatory expectations from the start.

Another focal point was third-party risk management, especially in today’s BaaS-driven banking environment. During my conversation with Christina Tetreault, Deputy Commissioner, Officer of Financial Technology Innovation at the California Department of Financial Protection and Innovation, she made it clear that bank-fintech partnerships are more than just IT projects. If the fintech’s technology fails, the bank will be held responsible for the issue.

As fintechs and financial institutions navigate this evolving landscape, the message from regulators and industry leaders is clear: regulatory freedom does not equal regulatory absence. Even as rules shift or stall, expectations remain high, especially when it comes to emerging technologies and third-party partnerships. In today’s environment, staying ahead means embedding compliance into innovation from the start of the project, proactively managing risks, and recognizing that regulatory clarity is still a moving target.


Photo by Gül Işık

8 Key Trends to Watch at FinovateSpring 2025

8 Key Trends to Watch at FinovateSpring 2025

This year at FinovateSpring, we’re seeing a strong convergence of fresh technologies and real-world financial use cases. From embedded finance to AI-powered risk management, the innovation that will be on display during the event, which takes place May 7 through 9 in San Diego, is a signal of the rapidly evolving needs of both financial institutions and their customers. We analyzed the key themes across this year’s 40+ participating demo companies and uncovered eight standout trends shaping the future of fintech.

AI and Machine Learning Are Everywhere

AI is evolving from a nice-to-have feature into a foundational technology. This year, 15 companies are showcasing solutions powered by AI or machine learning to drive personalization, automation, and real-time decision-making. Whether it’s fraud detection, customer engagement, or operational efficiency, companies like APIMatic, Casca, Cinareo Solutions, Cratoflow, Crosswise, Crux Analytics, Illuma, Layerup, Parcha, Quavo Fraud & Disputes, QuickFi, Quivly AI, Solda.ai, Stack AI, and Winnow are showing that AI is the engine behind scalable, modern finance.

Digital Transformation Goes Deeper

As financial institutions continue to modernize, digital transformation is expanding beyond the basic front end changes we saw in 2020. Tools supporting the developer experience, infrastructure, and process redesign are now in the spotlight. Companies like APIMatic, Anonybit, Cinareo Solutions, Illuma, Intellect Design, Kaian, Layerup, Penny Finance, QuickFi, ReSight, Solda.ai, and Stack AI are helping banks shift to cloud-based, API-driven, and future-ready environments.

Consumer Banking is Getting Smarter

Consumer-focused solutions are trending with 10 companies offering innovations in retail banking. From improved digital experiences to smarter customer onboarding, companies such as Anonybit, Bits of Stock, CoHome, Hive Technologies, Instarails, Kaian, Parcha, Penny Finance, SuperMoney, and Winnow are reimagining how consumers interact with their banks.

Embedded Finance Gains Momentum

Embedded finance is enabling a broader range of companies– both financial and non-financial– to provide an increasingly diverse range of financial services. Nine companies, including APIMatic, BankShift, Casca, CoHome, DashDevs, Express Wages, Félix, QuickFi, and TAPP Engine are enabling financial services to be embedded within broader customer journeys in areas ranging from e-commerce to payroll to enterprise tools.

Payments Innovation Is Accelerating

From real-time disbursements to smarter infrastructure, payments remains a top priority. Companies like APIMatic, Cratoflow, DashDevs, Express Wages, Félix, Hive Technologies, Instarails, Intellect Design, and Quavo Fraud & Disputes are focusing on speed, transparency, and compliance across the payments stack.

Customer Acquisition Is Being Reimagined

Nine firms are focusing specifically on helping financial institutions attract, convert, and retain customers more effectively. Expect to see data-driven onboarding tools, personalized product recommendations, and engagement platforms from innovators like BankShift, Cinareo Solutions, CoHome, Covet, Crux Analytics, Layerup, Penny Finance, Solda.ai, and SuperMoney.

Business Banking Is Getting a UX Overhaul

Small and mid-sized businesses have historically been underserved when it comes to having an elegant banking user experience. This year, companies like Anonybit, Casca, Crux Analytics, Instarails, Intellect Design, Parcha, Winnow are presenting tools built to streamline onboarding, lending, and money movement for the business banking segment.

Security, Identity & Compliance Stay Front and Center

As fintech grows more sophisticated, so do fraudsters. Six companies—including Anonybit, DashDevs, Herd Security, Illuma, Solda.ai, Stack AI, Crosswise, Quavo Fraud & Disputes, ReSight, and Winnow—are focusing on identity verification, AML, and regulatory compliance to ensure security doesn’t fall behind innovation.

FinovateSpring is more than a showcase of new technology, it’s a preview of where the industry is headed. These trends reflect the real challenges and opportunities facing financial services, and the companies listed are among the ones leading the way. Register today to see what they bring to the demo stage.


Photo by Maximalfocus on Unsplash

4 Reasons Why Credit Unions are Top Fintech Adopters

4 Reasons Why Credit Unions are Top Fintech Adopters

Credit unions are entering a new era, fueled by a combination of necessity, opportunity, and partnership. As the pace of the digital world accelerates, these community-focused organizations have increased their willingness to lean in and adopt new technologies. They are no longer simply seeking to compete with banks, but they are instead seeking to deliver the personalized, community-driven service that has always differentiated them. New fintech partnerships are helping credit unions modernize operations, meet rising member expectations, and stay resilient in a rapidly evolving financial landscape.

This collaborative approach isn’t new to credit unions, rather, it’s part of their DNA. “Credit Unions have always been collaborators,” said Ami Iceman Haueter, Chief Research and Digital Experience Officer at Michigan State University Federal Credit Union. “We’ve had to be creative and scrappy to stay relevant and competitive in a crowded market. Fintech partners are a natural fit for this collaboration. Many allow us to personalize our service or products to our members and create a custom mix of solutions to go all in for our members. That’s what we do best. Having partners that are equally committed to that vision is invaluable. It’s what will carry us forward as an industry allowing us to continue showing up for our communities.”

The environment today is ripe for credit unions to take full advantage of this collaborative mindset. The combination of heightened member expectations, accessible new technologies, and a fintech community eager to partner has created a unique moment of opportunity. Below, we’ve highlighted four key reasons why credit unions have become some of the most active adopters of fintech innovation.

Tech integration is now compulsory

Credit unions now have to engage because involvement in certain technologies has become table stakes in the banking world. Over the past few years, the baseline expectations for banking services have shifted dramatically. Real-time payments, mobile-first experiences, and frictionless, digital onboarding are no longer differentiators, they’re requirements. If credit unions want to remain competitive and retain younger members, they must adopt similar digital tools that big banks and fintechs have. In 2025, falling behind on technology isn’t just a risk to growth; it’s a risk to survival.

More credit union-specific fintechs

The fintech ecosystem has matured immensely since the first bank launched online in 1994. Today, many providers are now creating solutions designed specifically for the unique needs of credit unions. From specialized digital lending platforms to member-centric financial wellness tools, fintechs are recognizing credit unions as an important, underserved market. This tailored approach makes partnerships more attractive and accessible, helping credit unions stay up-to-date on the latest tech trends.

Embedded finance is the ultimate enabling force

Embedded finance has made it easier for credit unions to leverage third-party technologies without needing in-house technical expertise. Gone are the days when integrating new technology required a complete overhaul of a credit union’s core system. Today’s embedded banking models allow credit unions to “plug and play” fintech solutions into their existing infrastructure. Because of this, these smaller players can offer services like buy-now-pay-later, upgrade their digital account opening workflows, or launch a new mobile app with a fresh look. Overall, embedded solutions allow credit unions to deliver tech-forward experiences without the burden of in-house development.

Regulatory clarity has eased pressure

Regulatory clarity and eased regulatory scrutiny has reduced barriers to forming partnerships with fintechs. As regulators have become more familiar with fintech partnerships, clearer guidelines and frameworks have emerged to support innovation in the credit union space. New charters, sandbox programs, and cooperative frameworks help credit unions explore partnerships more confidently. With better guidance in place, credit unions can engage with fintechs without facing the regulatory uncertainty that once made these partnerships seem too risky.

All of these aspects, and more, will be on full display at FinovateSpring, which takes place May 7 through 9 in San Diego.

If you’re attending next month’s event, don’t miss a special session designed exclusively for your credit union. The Credit Union Spotlight: Closed Door Session will take place on Wednesday, May 7, from 3:20 to 4:50, and will offer the opportunity to meet companies that are building technology specifically for the credit union ecosystem. Each company will provide a short introduction, followed by roundtable discussions where you can dive deeper into their solutions. If you’re interested in joining, please email [email protected]. Please note that space is limited and subject to approval.

Want to know more about what you can expect at FinovateSpring? Check out our blog content, the event agenda, and don’t forget to register and save $200 when you book by April 18, 2025.


Photo by Jonathan Cooper on Unsplash

Robinhood’s New Private Banking Offering is Missing One Key Element

Robinhood’s New Private Banking Offering is Missing One Key Element
  • Robinhood announced Robinhood Strategies, Robinhood Cortex, and Robinhood Banking, introducing AI-powered investment insights and premium banking services for Gold members.
  • Robinhood Banking, launching this fall, will offer private banking perks such as global currency transfers, luxury benefits, and up to $2.5 million in FDIC insurance, challenging established private banking providers.
  • Currently lacking a banking charter, Robinhood partners with Coastal Community Bank. Obtaining its own banking license could help it directly control offerings, reduce costs, and compete more effectively with legacy financial institutions.

At an event in San Francisco last night, digital stock brokerage app Robinhood unveiled plans for a new method of portfolio management, an AI investment tool, and a private banking offering. The new offerings come with exclusive benefits for Robinhood Gold members.

“Our goal is for Robinhood to give you a world-class financial team in your pocket, with cutting-edge tools you can’t find elsewhere,” said Robinhood CEO Vlad Tenev.

The three new products announced include Robinhood Strategies, Robinhood Cortex, and Robinhood Banking. Robinhood Strategies is a wealth management tool that offers investors more control, managed accounts, and an interactive portfolio. Robinhood Cortex is an investing tool that leverages AI to provide real-time analysis to help navigate the markets, identify opportunities, and stay up to date on news.

Much of the buzz surrounding the event seems to be focused on Robinhood Banking, and for good reason. Set to launch later this year, the new offering aims to bring the private banking experience to Robinhood Gold members. Along with traditional checking and savings accounts, members can also expect to receive “luxury benefits.” Among the differentiating factors of the new accounts, which offer up to $2.5 million in FDIC insurance, are the ability to send money across the world in 100+ currencies, access estate planning and professional tax advice, receive a physical delivery of cash to your doorstep, and access exclusive perks such as tickets to events like the Met Gala, Oscars, F1 Monaco Grand Prix, The Masters, and more, as well as private jet travel, private chauffeurs, luxury helicopter rides, and members-only vacation clubs. 

Robinhood Banking will launch this fall and will offer individual and joint accounts with the option to add children’s accounts with allowances and spending limits. When the banking services go live, the Robinhood Credit Card app will become the banking app and the credit card, checking, and savings will all live in one place. 

The launch of Robinhood Banking will place the company in competition with Morgan Stanley, Charles Schwab, and others that provide private banking services for a fee. And while Robinhood charges just $5 per month for its service, the fintech is missing one crucial element to becoming a fully-fledged bank: a banking license. Robinhood withdrew its application with the OCC for a bank charter in 2019 and has since partnered with Coastal Community Bank to provide banking services behind the scenes.

If (or perhaps when) Robinhood does prioritize obtaining its banking license, it will benefit by gaining more direct control over its banking operations, significantly reducing reliance on third-party banks. This move would allow Robinhood to cut costs, offer a wider range of banking products, and quickly adapt and innovate its offerings in response to market demands or customer feedback. Most importantly, having a banking charter would strengthen Robinhood’s credibility and competitive positioning among legacy financial institutions, empowering it to potentially expand beyond its current target demographic of younger investors into the broader retail banking market.

Today’s announcement comes two years after Robinhood acquired credit card company X1 for $95 million and one year after the California-based company unveiled its own credit card, the Robinhood Gold Card. Since then, the waitlist for the card has grown to nearly three million people. The company has rolled out the card to more than 100,000 people, and plans to launch it to another 100,000 people on the waitlist.

“With Robinhood Banking, we’re trying to solve many of the challenges presented by legacy banks,” said Robinhood Money GM and VP Deepak Rao. “Robinhood Banking is thoughtfully designed to be as easy to use as possible, while still delivering cutting-edge features historically reserved for the ultra-wealthy. We’re pushing the boundaries of what you should expect from your bank.”


Photo by Thirdman

5 Key Takeaways from Trump’s Payments Modernization Initiative

5 Key Takeaways from Trump’s Payments Modernization Initiative

Yesterday, Donald Trump signed an Executive Order (EO) to modernize the U.S. payments system by phasing out paper checks. The EO mandates that the Federal government will stop issuing paper checks for all disbursements starting September 30, 2025.

The EO, which is targeting waste, fraud, and abuse, will offer both banks and fintechs opportunities and challenges as they seek to bring digital banking to underbanked consumers who need to send payments to and receive payments from the federal government.

So as you begin your second quarter planning initiatives, here are a few things you’ll need to know about this week’s Executive Order.

Real time payments become solidified

Banks’ adoption of FedNow and The Clearing House’s RTP is increasing, and so are consumer expectations for faster fund transfers. This week’s EO stipulates the move to “fast, electronic payments,” which will change the expectations of even underbanked and elderly populations that rely on government monetary benefits.

Heightened emphasis on payment security and fraud prevention

The Fact Sheet detailing the EO specifically cites security and fraud prevention as major reasons for modernizing US payments. “President Trump is cracking down on waste, fraud, and abuse in government by modernizing outdated paper-based payment systems that impose unnecessary costs, delays, and security risks,” the Fact Sheet said. The move will ultimately bring stricter standards to government payments and will help foster consumer trust.

A shift toward digital identity verification

As payments digitize, reliable identity verification methods will become increasingly crucial. While bringing payments into the digital space will help boost KYC and AML verifications, it will also offer opportunities for fraudsters to create new scams. As an example, non-digitally native consumers may be more likely to fall victim to phishing attacks that they perceive to be payments from the federal government.

Not everyone is required to make the change

The EO states that exceptions will be made for people without banking or electronic payment access, in specific emergency payments cases, for certain law enforcement activities, and for other special cases that qualify for an exception.

Consumer awareness is key

The EO explains that, prior to the September 30 deadline, the government will initiate a comprehensive public awareness campaign to inform federal payment recipients of the shift to electronic payments. Banks should work alongside these campaigns with public awareness initiatives of their own to offer guidance on setting up digital payments and mitigating fraud.

Overall, this new EO represents a significant opportunity for banks and fintechs. By accelerating the shift to digital payments, the EO underscores the value of digital-first strategies and positions banks in a great place to attract new customers who previously relied on paper checks.

Banks and fintech companies that proactively support consumers during this transition—through seamless onboarding, education, fraud prevention, and robust digital identity verification—can strengthen their market position, deepen customer relationships, and foster long-term trust. Ultimately, the shift away from paper checks will reinforce existing efforts toward financial inclusion, drive consumer adoption of digital tools, and encourage innovation across the payments landscape.


Photo by Money Knack on Unsplash

As it Preps for IPO, Klarna Takes the Throne as Walmart’s BNPL Provider

As it Preps for IPO, Klarna Takes the Throne as Walmart’s BNPL Provider
  • Klarna is replacing Affirm as Walmart’s exclusive BNPL provider, marking a major shift in the BNPL space.
  • Walmart shoppers will soon be able to use Klarna’s installment loans in-store and online, with OnePay handling the user experience and Klarna underwriting the loans.
  • The deal strengthens Klarna’s U.S. presence ahead of its IPO, giving it access to millions of Walmart shoppers and increasing its loan volume, brand recognition, and potential investor appeal.

Klarna has big news today, and it’s not just that the company filed its IPO prospectus with the SEC. The buy now, pay later (BNPL) company announced that it has struck an agreement with Walmart to serve as the retail giant’s exclusive partner for BNPL installment loans.

Klarna is replacing BNPL provider Affirm, which secured the BNPL provider partnership with Walmart last January. Under the agreement, Klarna will provide the BNPL loans for Walmart shoppers in-store and online.

The online BNPL loans will be extended through Walmart-owned fintech OnePay (formerly known as ONE). OnePay will handle the user experience, while Klarna will be in charge of loan underwriting. The BNPL loans through One will range from three-month to 36-month terms and will charge interest rates ranging from 10% to 36%. Leveraging Klarna’s BNPL tool will add installment loans to OnePay’s suite of existing financial tools, which include banking, credit, and payments products. 

“This is a game changer,” said Sebastian Siemiatkowski, Co-founder and CEO, Klarna. “Millions of people in the U.S. shop at Walmart every day—and now they can shop smarter with OnePay installment loans powered by Klarna. OnePay choosing Klarna as their exclusive installment loans partner at Walmart in the U.S. is a huge vote of confidence as we pursue our goal of being available everywhere for everything. We look forward to helping redefine checkout at the world’s largest retailer—both online and in stores.”

This deal is a significant customer acquisition opportunity for Klarna. Walmart serves millions of shoppers daily, and Klarna’s presence at checkout will significantly increase its U.S. loan volume.

According to CNBC, Walmart will initiate the launch with Klarna in the coming months and will roll out to all Walmart channels later this year. It is likely that Klarna will serve as the only BNPL option for Walmart shoppers by the end of 2025.

​Walmart launched OnePay, its fintech startup, in January 2021 through a partnership with Ribbit Capital. In January 2022, Walmart expanded One’s capabilities by acquiring two fintech platforms, Even and ONE, which helped Walmart create a more comprehensive financial services app. One launched with a checking account product for Walmart employees, as well as some select customers, in 2022.

“It’s never been more important to give consumers simple and convenient ways to access fair credit at the point of sale—and that’s especially true for the millions of people who turn to Walmart every week for everything,” said OnePay CEO Omer Ismail. “We’re incredibly excited to partner with Klarna to give consumers easier and more seamless ways to shop with OnePay at Walmart.”

Notably, today’s partnership comes days after Klarna filed its F-1 prospectus with the U.S. Securities and Exchange Commission. While this is a much-anticipated move in the fintech community, the official valuation figures won’t come out until Klarna prices its shares, which may take around a month. That said, Klarna hopes to raise at least $1 billion at a $15 billion valuation.

This deal signifies two major things. First, it indicates a major shift in the BNPL landscape. Affirm’s stock dropped by more than 10% in pre-market trading following Klarna’s announcement, which highlights just how significant a BNPL partnership with Walmart is. Additionally, Walmart’s move to switch its BNPL provider after a little over a year shows that retailers are not afraid to reevaluate their BNPL strategies, and that no single player is untouchable.

Second, Walmart’s move indicates that the retailer is positioning OnePay to compete with traditional banks and fintechs. By adding Klarna’s BNPL tools to its roster of banking services, Walmart is positioning OnePay as a more comprehensive financial platform for its customers, which tend to be financially underserved individuals.


Photo by Cristian Cativo

Navigating the Shift: Four Key Financial Policy Changes Under the New Administration

Navigating the Shift: Four Key Financial Policy Changes Under the New Administration

Is anyone else having difficulty keeping up with all of the changes that have taken place since the new administration took office last month? Over the course of the last 18 days, sweeping shifts have reshaped regulations, agency leadership, and key financial policies— creating both uncertainty and opportunity for businesses navigating this evolving landscape.

While many of these changes will have broad implications for U.S. citizens and organizations operating in the country, I’ve distilled the most significant updates on the White House’s website impacting financial services. Below, I break down the four most critical developments that banks, fintechs, and other financial institutions need to watch closely.

Imposing a regulatory freeze

On January 20, President Trump signed an executive order to halt new rulemaking and review pending regulations across federal agencies. It also calls for the withdrawal of any rules that have been sent to the Office of the Federal Register but not published yet. The administration plans to use the pause to reassess both existing and proposed regulations so that they align with its policy objectives.

For banks and fintechs, this makes it challenging to prepare for future regulatory requirements. It may impact firms’ compliance timelines and will likely confuse financial services companies’ strategic planning efforts.

Strengthening hold on digital assets

On January 23, President Trump issued an executive order titled “Strengthening American Leadership in Digital Financial Technology.” The order prohibits the establishment of US central bank digital currencies (CBDCs). It also establishes a working group to propose a regulatory framework for digital assets within 180 days and allows individuals and entities to access and use open public blockchain networks.

This may present opportunities for banks and fintechs to engage in the stablecoin economy, especially when it comes to cross-border transactions and digital payments. Additionally, governmental protection of an open blockchain may spark the creation of new blockchain-based products and services.

Removing barriers to AI

Also on January 23, President Trump issued an Executive Order titled Removing Barriers to American Leadership in Artificial Intelligence that aims to enhance the US’s position in AI. The order removes existing AI policies and directives that are considered barriers to innovation. Within 180 days, officials are tasked with creating a plan to sustain and enhance America’s global AI dominance.

This emphasis on reducing regulatory barriers may lead to both banks and third party fintechs adopting AI technologies at a faster rate. However, as AI is a double-edged sword, the relaxed regulatory environment may create uncertainty as organizations wait for new guidelines to develop.

Implementing the DOGE workforce optimization initiative

On February 11, President Trump issued an Executive Order titled Implementing The President’s ‘Department of Government Efficiency’ Workforce Optimization Initiative, which intends to streamline the federal workforce and enhance operational efficiency. Controversially, the order gives Elon Musk and his team direct access to data held at the US Treasury Department. As a result, a coalition of more than a dozen US states is planning to file a lawsuit to block access in order to protect the personal data of US citizens.

By reducing staffing at federal agencies that oversee financial institutions, the order may impact the efficiency and thoroughness of regulatory examinations and compliance enforcement. The instability could also cause uncertainty for banks, disrupting strategic planning and compliance efforts.

Other actions

There are two other actions not yet listed on the White House’s official news release page, but each is significant.

Earlier this week, the Associated Press unveiled that the Trump administration ordered the Consumer Financial Protection Bureau (CFPB) to suspend all of its activities. Finovate Analyst David Penn reported on the details of the situation, including what the CFPB can still do and who may take over the agency if it continues to exist.

Today, the Wall Street Journal exclusively reported that the Trump administration is also considering folding the FDIC into the Treasury Department. Experts cited that this is unlikely to transpire, however, as Congress is unlikely to pass such a measure. “This idea would pose an enormous risk of terrifying Americans about the safety of their deposits and triggering bank runs,” Former Federal Regulator Patricia McCoy told CNN.


Photo by René DeAnda on Unsplash

Key Regulatory Changes in Europe for 2025: What You Need to Know

Key Regulatory Changes in Europe for 2025: What You Need to Know

When regulatory changes are a moving target, it can be difficult for financial services companies to keep up. In 2025, several key regulatory updates across Europe will demand attention, from changes to MiFID II and PSD3 to new directives on anti-money laundering (AML) and artificial intelligence (AI). These shifts vary in scope by country, but all require companies to adapt to ensure compliance.

While many of these updates are an inconvenience and require organizations to implement new processes and workflows, they will ultimately improve transparency, security, innovation, and enhance the end user experience. Financial services companies that stay ahead of the curve will be better positioned to meet these challenges.

For deeper insights, FinovateEurope, which is taking place in London on February 25 and 26 (register today and save!), will host a diverse group of experts who will explore the region’s regulatory shifts in detail, offering valuable guidance on how firms can best prepare for 2025. Below, we’ve highlighted some of the most important changes that are likely to impact financial services organizations this year.

ESG compliance

The Sustainable Finance Disclosure Regulation (SFDR), which was introduced in 2021, required firms to complete more detailed and standardized reporting on sustainability practices. As a result, many needed to invest in systems to track and report ESG metrics more accurately and transparently. In 2025, the European Commission and European Supervisory Authorities (ESAs) is expected to update the legislation to improve definitions, simplify disclosures, add more mandatory disclosures, and more.

Additionally, in 2025, the Corporate Sustainability Reporting Directive (CSRD) is expected to see a significant expansion to its scope. More companies will be required to report under the CSRD, firms will be required to disclose detailed information about their sustainability impacts, the reporting measure will need to be fully integrated into a company’s business strategy and decision-making processes, and more.

While these shifts may be challenging, many organizations will likely benefit from improving their ESG transparency because it will help attract investors who prioritize sustainability and may improve their firm’s reputation.

Digital Operational Resilience Act (DORA)

The Digital Operational Resilience Act (DORA) went into effect in January of 2023 and began to require compliance last month. DORA aims to enhance the IT security of financial services companies including banks, insurance companies, and investment firms. The regulation requires firms to regularly test their systems, create contingency plans, and ensure that their third-party providers are also in compliance with security standards. The three European Supervisory Authorities– the European Banking Authority (EBA), the European Insurance and Occupational Pensions Authority (EIOPA) and the European Securities and Markets Authority (ESMA)– anticipate that DORA will reduce the risk of systemic disruptions and improve financial stability.

EU AI Act

Established in 2024, the European AI Office is implementing the EU AI Act to create regulatory framework for artificial intelligence in Europe. Ultimately, the regulation seeks to ensure that AI applications are transparent, accountable, and ethical. The first requirements under the EU AI Act went into effect earlier this month to ban the use of AI systems that involve prohibited AI practices. There are eight categories of prohibited practices, as law firm DLA Piper details in the graphic below.

European Data Governance Act (DGA)

The European Data Governance Act is designed to enhance consumer trust in voluntary data sharing to help businesses innovate and grow. The act establishes a framework for data sharing and sets standards for data altruism and data intermediaries.

In 2025, the primary update to the EU DGA is the upcoming enforcement of the Data Act, which will impact how businesses manage and share data and their personal information, by specifying data access and usage. The new legislation will take effect in September of 2025.

AML compliance

Anti-money laundering (AML) regulations are set to become even stricter with the introduction of new directives in 2025. Specifically, the EU AML Package, which is launching this year, establishes a new supervisory authority called the Anti-Money Laundering Authority (AMLA). Based in Frankfurt, the AMLA will implement stricter compliance measures for financial institutions, especially high-risk firms, to help combat money laundering and terrorist financing across the EU. 

While complying with the AML regulations will require firms to rework their existing strategy and perhaps create new systems, it will help reduce financial crimes, protect firms from reputational damage, and reduce regulatory penalties.

Payment Services Directive 3

Payment Services Directive 3 (PSD3) is the third iteration of the EU’s Payment Services Directive. Changes to the directive coming in 2025 are expected to further enhance open banking capabilities and offer third-party providers greater access to consumer financial data while improving security and user consent mechanisms. The new iteration will also further protect consumers by providing clearer guidelines on payment methods, transaction rules, and dispute resolution processes. The updated standards are expected to increase the speed, transparency, and security of payments, while providing customers with a more seamless and trustworthy payment experience.

Crypto regulation and the MiCA framework

2025 will bring the full implementation of the Markets in Crypto-Assets (MiCA) framework, which will introduce regulation for cryptocurrencies and digital assets across the European Union. Financial services companies that engage with crypto will need to comply with new licensing and operational requirements.

Originally drafted and proposed by the European Commission in September 2020, MiCA aims to provide clarity for businesses and investors by establishing clear rules around the trading, issuing, and holding of crypto assets. This transparency is expected to provide stability and foster trust in the crypto market.

Anti-Tax Avoidance Directive (ATAD III)

The Anti-Tax Avoidance Directive (ATAD III), which aims to reduce tax avoidance by implementing stricter rules to combat aggressive tax planning and ensure that companies pay taxes, is slated to go into effect in 2025. The new directive requires financial services companies to adjust to their tax structures and increase their scrutiny of cross-border transactions. Ultimately, ATAD III should help promote fairness in the EU’s tax system by addressing loopholes used for tax avoidance.


Photo by Anastasia Shuraeva

Why “AI Agents” is the Catchphrase of 2025

Why “AI Agents” is the Catchphrase of 2025

At FinovateFall last year, we heard plenty of analysts and industry experts say that AI agents are going to replace generative AI on the hype scale. That’s because AI agents, or agentic AI, have the capability to perform tasks, not just generate information. It is this differentiator that has the potential to create a great amount of value for both banks and fintechs, so much so that it has become the newest buzzword in financial services.

Fueling the rise of AI agent hype is the launch of Operator, Open AI’s new AI Agent. “Operator is a system that can use a web browser– in this case, a web browser in the cloud– to accomplish tasks that you give it,” said Open AI CEO Sam Altman during the launch. “Just like you would use a web browser… Operator can do that and control all sorts of things.” Operator has already gone live for ChatGPT Pro users and will soon be available to Plus users.

Open AI isn’t the only tech company launching an AI agent, and the use cases aren’t limited to making a restaurant reservation or buying groceries. Agentic technology is already live and in-use at some financial institutions.

The new technology has a number of potential use cases, five of which I’ve listed below. Keep in mind that some of these are not possible with current AI agent tools, and most are not able to be achieved fully autonomously, and require human-in-the-loop during some stages. However, the technology is moving fast, and AI agents will likely reach this level of autonomy soon.

Customer service and support

Banks and fintechs have used all forms of AI to improve and automate their customer service for years. They can now use AI agents to understand customer queries and analyze the conversations to identify the root cause of an issue, then offer customers the appropriate reply.

Potential prompt: “When a customer contacts you seeking an agricultural loan, contact the county in which the property is located to verify the legal property boundaries.”

Content marketing and copywriting

AI agents can be deployed to research and analyze all available information on a specific topic. Banks can then use another AI agent to transform all of that information into a blog post or marketing copy for a webpage.

Potential prompt: “Research new budgeting websites and capabilities, then write a five-part blog post series and email it over the course of five weeks to customers with less than $5,000 in assets held at the bank.”

Loan and credit underwriting

While generative AI is able to analyze customer profiles to assess creditworthiness, AI agents can take the process a step further by completing tasks in a workflow analyzing credit histories, transaction patterns, and market analysis to make instant, accurate decisions about potential borrowers.

Potential prompt: “For every new small business loan inquiry that comes in, analyze the individuals’ credit and overdraft histories. For small businesses with a physical location, analyze foot traffic of similar businesses in the same region and make a credit decision based on this information.”

Administrative tasks

Because AI agents are able to “think” for themselves and operate independently, they can easily complete tasks such as organizing and making a reservation for a client dinner, placing an order for a new computer keyboard, or placing a catering order for an office party.

Potential prompt: “Make a dinner reservation at a restaurant my client would like, given their Instagram account, for 10 people on May 2 at 7 p.m. Tell the restaurant that two people in the party have a gluten allergy.”

Customer communication

Banks can deploy AI agents to communicate with customers to send personalized messages about their preferences, needs, or simply to autonomously notify them of account changes. They can also reply to customer responses. And because AI agents can generate answers without being trained, they can even reply to customers in cases where they do not have a specific, canned response template.

Potential prompt: “Email all of my wealth management clients that have been with me for over three years asking them to update their risk tolerance. Use their replies to update their portfolios.”


While it is fun (and a bit spooky) to think about all of the potential use cases of agentic AI, we are far from the reality of putting most of these potential prompts to use in a seamless manner. Operator and other AI agent technologies are still in their early stages; even OpenAI CEO Sam Altman admitted they still have “a lot of improvements to do” on Operator.

Because of how new the technology is, there still needs to be a manual confirmation for most of the use cases, especially when it comes to making transactions. Similarly, even though there is no current AI regulation for banking operations, banks should use caution and keep humans in-the-loop, especially when making underwriting decisions and communicating with customers.


Photo by cottonbro studio

2025 is the Year of Fintech Spring: 5 Trends to Watch at FinovateEurope

2025 is the Year of Fintech Spring: 5 Trends to Watch at FinovateEurope

If you haven’t heard, 2025 is the year of fintech spring. The chill has been taken out of the industry as investors regain confidence, new startups can launch with less risk, and established players are doubling down on new technologies to meet evolving customer demands. From fresh AI applications to the new uses for embedded finance, fintech is experiencing a renewed momentum.

Fortunately, catching up on what’s new and what’s next is as easy as attending FinovateEurope, which is taking place 25 through 26 February in London. The agenda not only features keynote presentations from the region’s top thought leaders, it will also showcase the latest technology available on the market today with live demos from more than 30 fintechs. Register today to get a discount and secure your spot!

To maximize your time spent, each session will highlight some of the newest themes and trends in the industry today. Here are some of the major trends you can expect to see unfolded and explained on stage.

Embedded finance matures

Why it matters:
Embedded finance has been trending upward in fintech over the past few years, and for good reason. It helps organizations add seamless, contextual financial experiences for their customers, but it has also added the potential for banks and financial services companies to add a new revenue stream through Banking-as-a-Service (BaaS). Best of all, it allows both companies and banks to focus on their core competencies while enriching the user experience.

What’s happening:
Embedded finance has proven its utility in the payments and lending worlds, allowing businesses to embed payments tools and lending capabilities into their existing website or mobile app. Now, embedded finance is moving beyond payments and lending into sectors like insurance, healthcare, and logistics.

Where you’ll see it:
Over the course of the two-day FinovateEurope conference, multiple conversations on embedded finance and BaaS will take the stage. Be sure to check out:

  • This executive briefing on embedded finance titled, “How financial institutions can capture the huge opportunity of embedded finance & embedded banking in both retail & commercial banking.” The session will discuss opportunities for banks to expand their distribution footprint at a relatively low cost, consider risks in BaaS, how to find a competitive strategy, and more.
  • This power panel titled, “BaaS powered embedded lending is on the rise and is moving beyond buy now pay later – how can financial institutions capture the opportunity?” The panel will look at the rise of lending integrations, the role of AI in risk assessment, embedded finance regulation, and more.

Organizations navigating the impact of the EU AI Act

Why it matters:
The EU AI Act is set to be one of the most comprehensive AI regulations in any region. The regulation went into force in August of 2024 and is poised to shape how banks and fintechs develop and deploy artificial intelligence. The act focuses on transparency, accountability, and controlling risks, especially when it comes to AI’s applications in areas such as credit scoring and fraud detection.

What’s happening:
Fintechs leveraging AI are finding that they need to adapt (and quickly) in order to comply with the new rules while continuing to create and develop new, AI-centric products. While the new requirements might lead to an increase in operational costs, they also might bring new opportunities for organizations to build trust and differentiate their offerings by incorporating ethical AI practices.

Where you’ll see it:
FinovateEurope is sure to be packed with fresh AI use cases and regulatory guidance. Here are just a few of the sessions that will inform and educate on AI application:

  • This keynote presentation titled, “Artificial intelligence – are we overestimating the short term impact & underestimating the long term impact?.” During the keynote, Tracey Follows will discuss how AI is a long-term trend line and will look at what this means for financial services.
  • This session titled, “What is the state of play for GenAI in financial services? Assessing leading use cases, challenges, barriers to adoption and how to navigate the roadblocks.” Forrester Analyst Aurélie L’Hostis will help organizations break down practical steps to get started in AI.
  • This AI power panel titled, “Strategies for successful AI adoption & digital transformation and why achieving success will go beyond the tech.” The panel will bring insight into how the EU AI Act may guide future thinking on the topic. It will also discuss governance, data privacy, security, compliance, and ethical implications about the application of AI.

The rise of AI-powered personalization

Why it matters:
Fintech has sought to help banks personalize the user experience for over a decade. By applying AI and machine learning, firms can help drive hyper-personalized financial products and services.

What’s happening:
Fintechs and banks are enhancing the user experience to help boost engagement and retention, differentiating themselves in a crowded market.

Where you’ll see it:
Just as personalization permeates various subsectors of fintech, the topic will also be present among multiple sessions at FinovateEurope. There will also be a couple of sessions dedicated exclusively to the topic of personalization, including:

  • This keynote address titled, “Enabling hyper-personalization: fusing functionality, data, and strategic partnerships” that discusses how to deliver hyper-personalized experiences. The conversation will also explore how banks can leverage data, advanced API integrations, and AI-driven insights to offer the right products to the right customers at the right time.
  • This power panel titled, “The CX revolution – how can FIs compete in a hyper personalized world?” in which panelists will talk about how customers view the world, what lessons can be learned from other verticals, and how to keep up with customer expectations.

Payments get faster and smarter

Why it matters:
Payments are not only getting cheaper, but they are also happening faster, which means that fraud is happening at an increasing rate.

What’s happening:
Global trade and personal remittances, along with everyday transactions, are being shaken up by stablecoins and CBDC experiments, which may help create more transparent payment solutions.

Where you’ll see it:
At this year’s FinovateEurope conference, payments will permeate many of the conversations on stage. Here are two particular panels that will address the top concerns:

  • Payments power panel titled, “The payments market is estimated at $2.85 trillion in 2024 and is expected to reach $4.78 trillion by 2029 – how can banks reimagine payments and capture this growth opportunity?” The panelists will consider the opportunity available in payments, as well as regulatory concerns and risk.
  • Keynote address titled, “Authorized push payment fraud losses across Europe may be as high as €2.4 billion, increasing by 20% to 25% annually; how are regulators addressing it?” The presentation will look at payment fraud risk and potential regulatory changes that may address authorized push payment fraud.

Regtech redefined by real-time compliance

Why it matters: Without regtech, banks and fintechs would be on their own to figure out and comply with an ever-changing set of rules. Leveraging a third party regtech provider not only helps organizations reduce compliance costs, it also facilitates faster adherence to new rules.

What’s happening: Regtech solutions can create real-time monitoring tools to keep up with evolving regulations. This is particularly important around crypto and AI regulations as they are very fast-moving fields.

Where you’ll see it:
FinovateEurope will host an entire stage dedicated to discussing banking regulation and risk. Among the presentations taking place are:

  • Keynote Address titled, “A whistlestop tour of EU regulation – what financial services providers need to know about DORA; FiDA; eIDAS, and DMA?” that will brief the audience on these current and future regulations and look at how regulators are cracking down on risk management.
  • Power Panel titled, “Banking risk and resilience: meeting the challenges of new regulations, emerging tech, rising banking fraud and new cyber security threats” that will consider digital identity, risks of using AI and cloud risks, managing third party risks, and more.

Photo by Fer Troulik on Unsplash

Why Youth Banking is Set to Surge in 2025

Why Youth Banking is Set to Surge in 2025

The youth banking market has seen growth over the past decade, but it still has a long way to go. Throughout the years, banks have focused much of their efforts on chasing the customers with the most money. Higher net worth customers can increase a bank’s deposits, be willing to take advantage of more of the bank’s product offerings, and often come with lower risk of default. Children and teens, however, are less appealing of a market, as they generally do not add a lot of assets and can come with additional headaches, such as special regulatory requirements.

That said, 2025 may be a breakout year for youth banking, which is set to experience significant growth as enabling technologies, evolving customer needs, and market opportunities create a perfect storm.

FinTok is making finance cool

Short form video platforms like TikTok, YouTube, and Instagram have evolved from places to post fun dance videos to become hubs for financial education and empowerment. This is especially true for Gen Z users, who spend a lot of time on these social platforms. The financial niche of TikTok, FinTok, has turned into a channel in which influencers simplify financial concepts, share savings and investing tips, and make financial education entertaining.

Banks and fintechs have yet to fully embrace this style of communication, largely because of the regulatory implications. Whether or not they are trying to reach out to clients on the social platforms, however, the fresh content is working to promote new interest in finance among younger generations. In 2025, banks that embrace the FinTok trend could stand out as financial partners for a new generation of financially curious consumers.

Financial education is on an upswing

The U.S. historically has been poor at integrating financial literacy in education systems, but that is rapidly changing. Schools, nonprofits, fintechs, and banks have increasingly prioritized financial education, integrating it into curricula and offering free resources to both parents and children. We’ve also seen a rise in apps that gamify learning about savings, budgeting, and investing. For banks, this means that now in 2025, young consumers not only have interest in the financial ecosystem, but they are also starting off with a strong foundation and a greater appetite for digital financial tools.

Youth-centric features are increasingly common

Gone are the days when “youth banking” meant a basic savings account with parental oversight. In 2025, you can expect to see these platforms include a wider range of features, including gamified savings goals, allowance management, safe spending controls, and even investment tools tailored to teenagers.

Banks and fintechs that prioritize these youth-centric tools with intuitive design elements will create stickier products. Many are doubling down on youth-friendly offerings via partnerships with companies such as Greenlight, which partners with a wide range of banks, including U.S. Bank, to empower families with financial tools.

Youth banking tools offer a means of differentiation

With the fintech landscape becoming increasingly crowded, youth banking tools provide an opportunity for differentiation. By offering new, unique features for traditionally underserved kids and teens, firms can stand out while capturing an untapped market segment.

Youth-focused offerings also serve as a way to engage the entire family, as parents will likely appreciate tools that not only educate their children about money, but also offer a starting point for them to establish their financial standing. As the banking landscape becomes more crowded in 2025, we can expect to see more youth tools that serve as a differentiator.

The great wealth transfer is already underway

The great wealth transfer, the impending movement of $84 trillion in wealth from Baby Boomers to Millennials and Gen Z is one of the most significant financial shifts of our time. In fact, the funds transfer is already underway as some Millennials and Gen Z have already started receiving inheritance. As organizations seek to capture this wealth, marketing to children and teens will allow firms to capture some of the wealth from those who are just starting their financial journeys.

Millennial parents are seeking to break the cycle

Millennials experienced financial hardship during the 2008 recession and some are still reeling from a combination of that downturn and burdensome student loans. The majority of Millennials are now parents, and because many feel like they were shortchanged in financial education and opportunities, they are are determined to equip their children with better financial habits.

Unlike previous generations, many Millennials are actively seeking to teach their kids about money management from a young age. Youth banking platforms, with features like savings goals and educational resources, align well with this parental mindset.

For banks and fintechs, 2025 is a great time to take advantage of dual opportunity. Not only can they capture the next generation of customers, but they can also strengthen relationships with their existing customer base of Millennial parents.


Photo by Kindel Media